
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
General Electric (GE) After The Turkish Airlines Deal And Castings Buy Looks Near Fair Value
General Electric (GE) is back in focus after GE Aerospace secured an engine deal with Turkish Airlines and moved to buy castings supplier Consolidated Precision Products, reshaping expectations around its long-run aviation earnings profile.
For context, General Electric’s share price has edged higher over the past week and month, while the 90 day share price return is down about 10%, yet the 1 year total shareholder return of roughly 5% and very large 5 year total shareholder return near 4x still point to long haul momentum as investors weigh deals like Turkish Airlines, the castings acquisition and continued interest from large holders such as XLI against recent profit taking.
Spot 41 power grid technology and infrastructure stocks that, like General Electric, are tied into long-term aviation and infrastructure spending themes and could benefit as engine demand and grid upgrades move together.General Electric now trades only slightly below one intrinsic value estimate, yet at a roughly 25% discount to the average analyst target. Is this recent pullback already fair, or still generous, for the Turkish Airlines and castings deal story?
Most Popular Narrative: 2% Overvalued
On the narrative view, General Electric screens as slightly expensive, with a fair value of about $307 against the last close of $313.83, which leaves only a small gap for investors to debate.
GE is a classic high-conviction, wide-moat infrastructure asset. The company correctly anticipated that reliability and time-on-wing would become the ultimate physical bottlenecks of the modern aviation era. While the stock commands an undeniable premium and carries genuine operational friction tied to its airframe partners, its technological moat and multi-year backlog make it one of the most compelling infrastructure bets on global execution.
See why 31 investors see General Electric as 2% overvalued.
Result: Fair Value of $307 (OVERVALUED)
Still, this bullish GE Aerospace story can unravel quickly if Boeing’s production setbacks deepen or if supply chain strains slow the delivery of critical castings and materials.
Find out about the key risks to this General Electric narrative.
Another View: Cash Flows Paint A Softer Picture
Price ratios say General Electric looks a touch expensive, yet the SWS DCF model points the other way. At $313.83, the shares sit slightly below an estimated future cash flow value of about $319.80. That frames the stock as modestly undervalued instead of stretched. Which lens do you trust more, earnings multiples or cash flows?
For a closer look at how those projected cash flows translate into that $319.80 figure, and what would need to change for that estimate to move, Look into how the SWS DCF model arrives at its fair value.
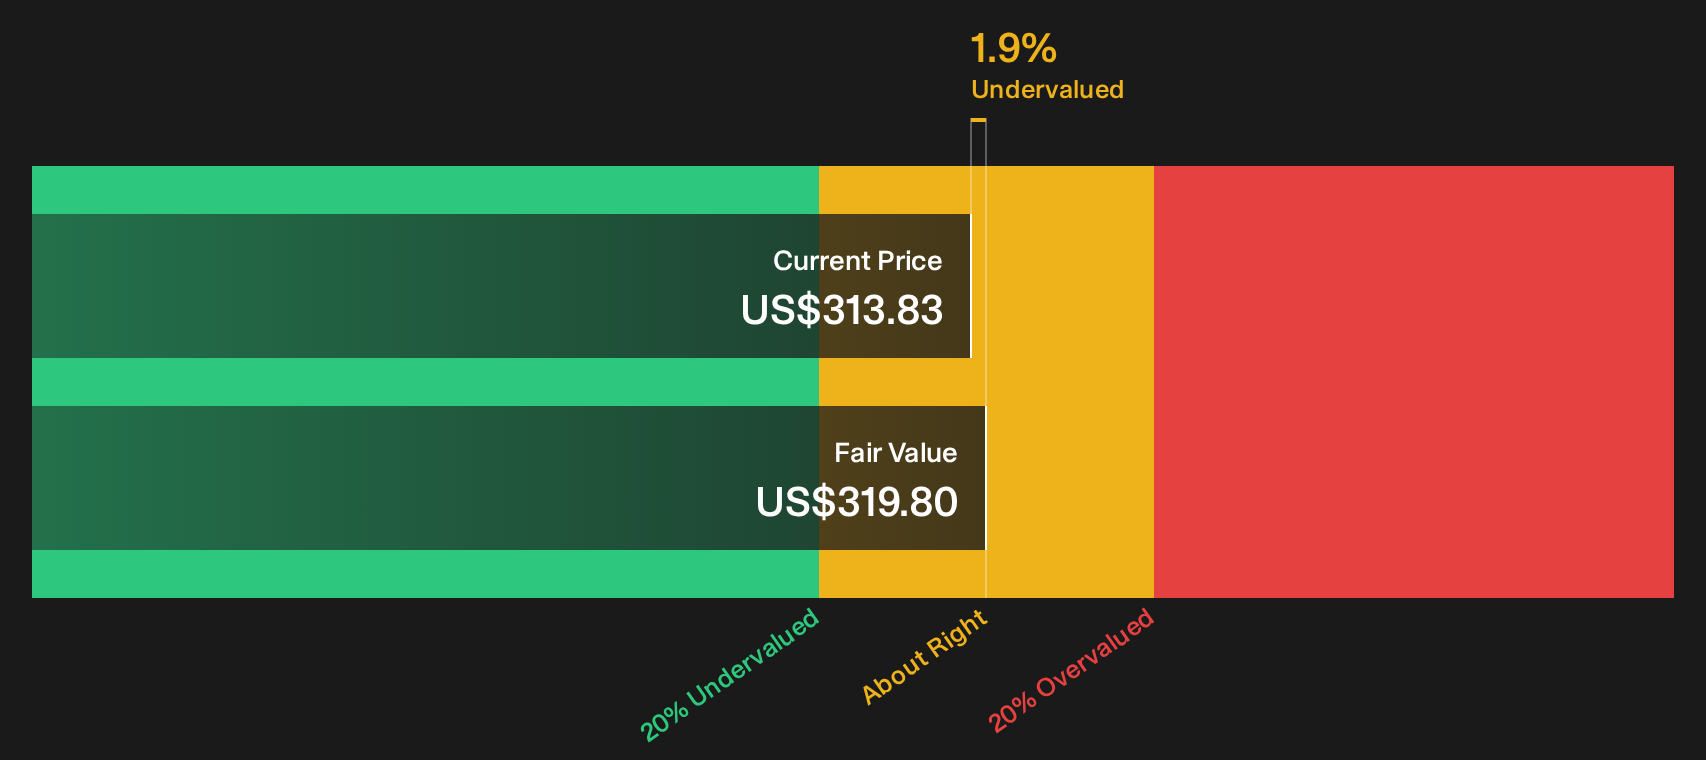
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out General Electric for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around General Electric’s valuation and deal pipeline will not resolve themselves. Look through the numbers, weigh the trade offs, and check the 4 key rewards and 1 important warning sign.
Hunting For More Ideas Beyond General Electric?
If you stop with General Electric, you risk missing other setups that may fit your style even better. Use a few focused screens and widen your opportunity set.
- Target resilient income by zeroing in on companies that behave like cash machines with strong payouts through 8 dividend fortresses.
- Spot quality at a discount by filtering for businesses that pair solid fundamentals with compressed valuations using the 33 high quality undervalued stocks.
- Secure a calmer ride by focusing on financially sound, lower risk profiles with the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com