
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Charles River Laboratories International (CRL) Earnings Beat Puts Fair Value Back In Focus
Charles River Laboratories International (CRL) drew fresh attention after quarterly revenue of US$1.00b came in 2.5% above analyst expectations, with organic sales and EPS also beating estimates and the share price climbing 31.5% since the report.
The recent earnings beat has come on top of a sharp share price move. Charles River Laboratories International has posted a 90 day share price return of 33.8% and a year to date gain of 48.3%, while the 1 year total shareholder return is 68.1%. This is despite a 5 year total shareholder return that is still down 28.6%. This suggests momentum has picked up recently as investors reassess both growth prospects and risk after the quarterly result and new partnerships in cell therapy and digital lab execution.
Scan beyond Charles River Laboratories International and see which peers are also attracting fresh interest after earnings and partnership news with our curated 20 high quality undiscovered gems
Bulls see Charles River Laboratories International as a quality compounder at work in cell therapy and digital lab infrastructure. Bears point to a loss and a sharp re-rating. Which story do the current valuation markers back up?
Most Popular Narrative: 4.9% Undervalued
On the numbers, the most followed narrative sees Charles River Laboratories International’s fair value at $315.53, a touch above the $300.15 last close. It links that gap directly to mix shift and cost programs rather than momentum alone.
The main thing that has to go right is that higher value services such as bioanalysis and Manufacturing Solutions, supported by AI enabled workflow changes and internal primate sourcing, continue to shift the mix toward later stage and recurring testing while offsetting softer areas like RMS and government or academic demand.
See why 4 investors see Charles River Laboratories International as 5% undervalued.
Result: Fair Value of $315.53 (UNDERVALUED)
Still, the story can change quickly if the shift toward non animal testing accelerates, or if tighter government and academic budgets drag on RMS demand.
Find out about the key risks to this Charles River Laboratories International narrative.
Another View: Charles River Laboratories International Through A Cash Flow Lens
The analyst target of $315.53 presents Charles River Laboratories International as modestly undervalued. A different lens tells a cooler story. The SWS DCF model estimates future cash flows at $293.93 per share, which is below the current $300.15 price and suggests a slight premium instead of a discount.
That gap is not large, yet it raises a simple question. Are you more comfortable focusing on earnings projections out to 2029 or on what the cash flow math indicates today.
Look into how the SWS DCF model arrives at its fair value.
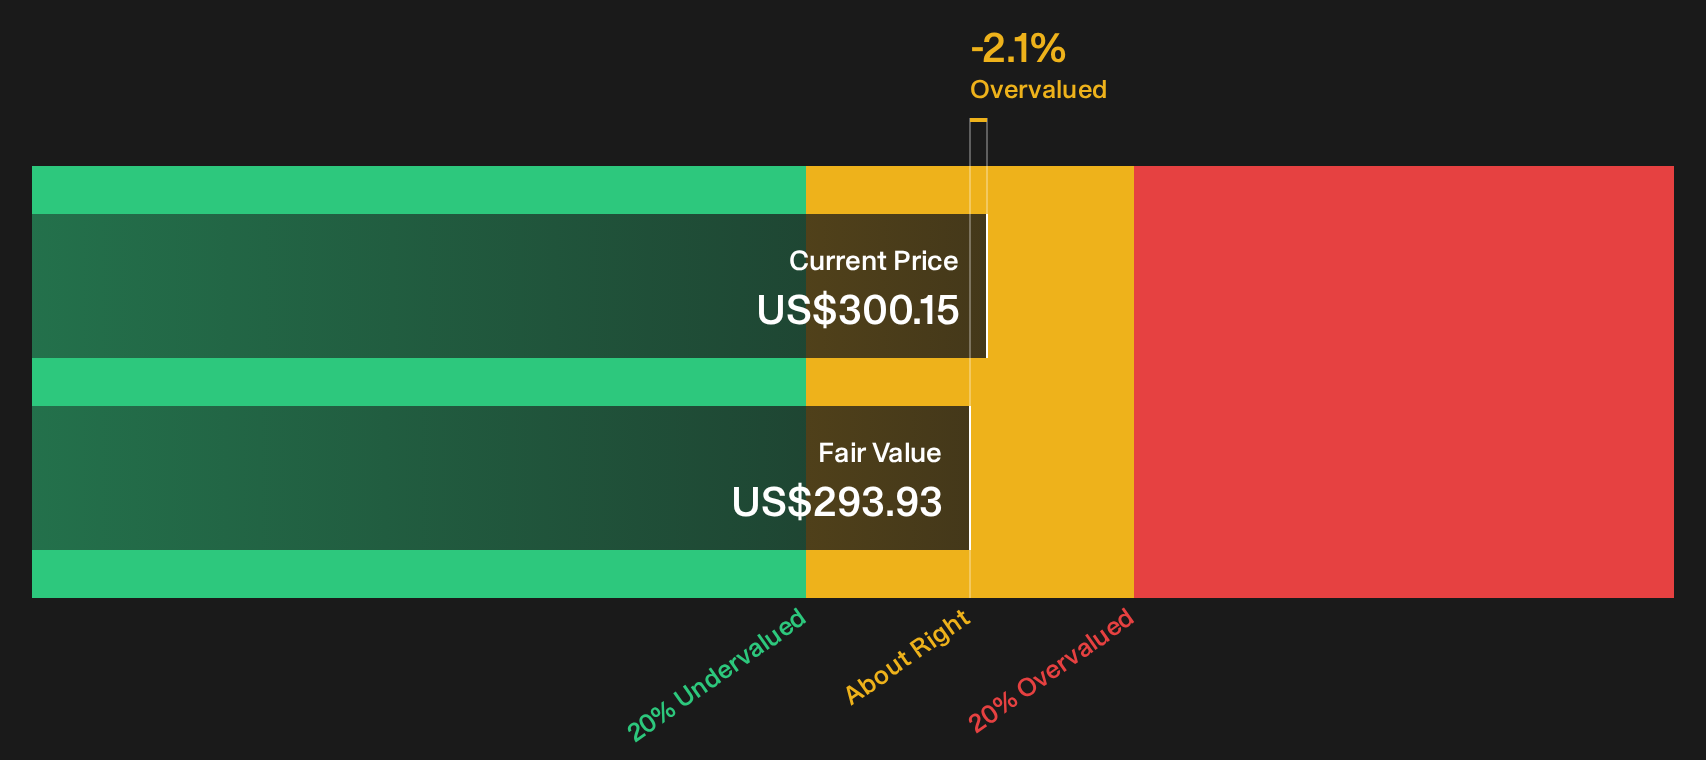
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Charles River Laboratories International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mix of optimism and caution around Charles River Laboratories International feels finely balanced, it may be worth moving quickly to inspect the numbers, examine the assumptions, and consider both the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Charles River Laboratories International?
Do not stop with one stock. Use this momentum to scan wider, compare different opportunities, and pressure test your thesis against fresh data driven ideas.
- Target resilient balance sheets by reviewing companies in the list of solid balance sheet and fundamentals (25 results) that pair financial strength with more predictable cash positions.
- Hunt for value opportunities with the 33 high quality undervalued stocks that screens for quality businesses trading below their assessed worth.
- Prioritize stability and income potential through the 8 dividend fortresses that focuses on higher yielding payers with defensive profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com