
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Marathon Petroleum Earnings Preview: What to Expect
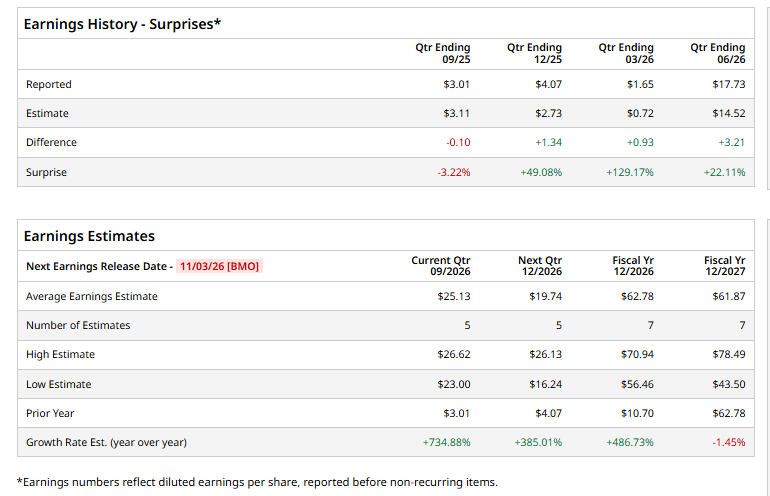
Based in Findlay, Ohio, Marathon Petroleum Corporation (MPC) is a prominent integrated downstream energy company. Valued at $139.2 billion by market cap, the company refines, supplies, markets, and transports petroleum products. The refining giant is expected to announce its fiscal third-quarter earnings for 2026 before the market opens on Tuesday, Nov. 3.
Ahead of the event, analysts expect MPC to report a profit of $25.13 per share on a diluted basis, up 734.9% from $3.01 per share in the year-ago quarter. The company beat the consensus estimates in three of the last four quarters while missing the forecast on another occasion.
For the current year, analysts expect MPC to report EPS of $62.78, up 486.7% from $10.70 in fiscal 2025.
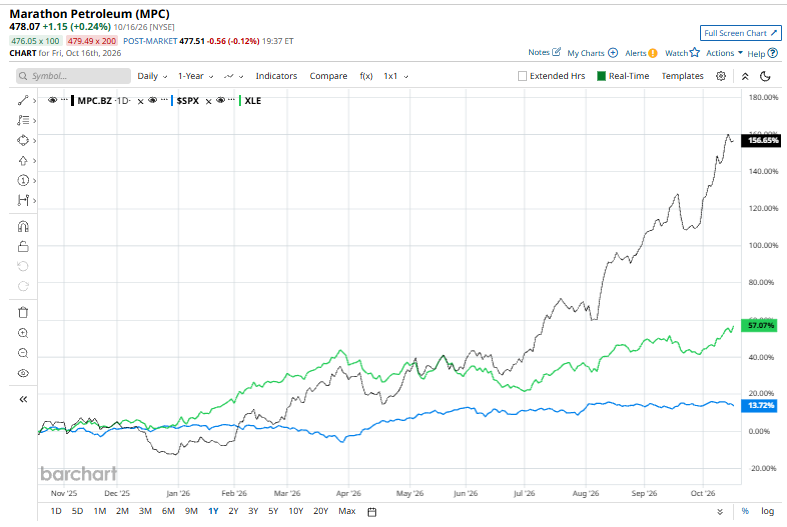
Marathon Petroleum stock has delivered a stellar performance over the past 52 weeks, with shares soaring 163.9% and comfortably outpacing both the S&P 500 Index’s ($SPX) 15.5% gainsand the State Street Energy Select Sector SPDR ETF’s (XLE) 60% returns.
Marathon Petroleum has benefited from favorable refining market conditions, strong demand for refined products, and improved refining margins, supporting earnings and investor sentiment over the past year. Its integrated operations and midstream business, primarily through MPLX, also provide diversified cash flows, while disciplined capital allocation, share repurchases, and dividend payments have strengthened shareholder returns. A key catalyst was a sharp rebound in refining profitability, as geopolitical disruptions tightened global fuel supplies and boosted margins on gasoline, diesel, and jet fuel.
Analysts’ consensus opinion on MPC stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of 19 analysts covering the stock, eight advise a “Strong Buy” rating, three suggest a “Moderate Buy,” and eight give a “Hold.” While the stock currently trades above the mean price target of $443.56, the Wall Street price target of $560 implies an upswing potential of 17.1% from the current market price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.