
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Invesco Stock And 2 ETF Issuers Worth Watching As Treasury Yields Stay High
When U.S. interest costs top US$1.05 trillion and the 10 year Treasury yield sits above 5%, long duration debt stops being background noise and starts rewriting the rules for risk. Higher refinancing costs, fatter risk premia and talk of future tax hikes can punish some sectors while creating fresh demand for others. This article walks through three stocks exposed to that story and explains why their reaction to today’s rate reality deserves attention.
The stocks that follow are just a sample set, and the full screen on Simply Wall St surfaced 14 more issuers with equally focused long-duration ETF narratives that do not fit into this short article. To see the complete field and quickly identify which asset managers align with your own rate view, head straight into the U.S. Long-Duration Treasury and TIPS ETF Issuers screener.
Marygold Companies (MGLD)
Overview: Marygold Companies provides fund management for ETFs and exchange traded products across the U.S., Canada and the U.K., alongside smaller security systems, beauty and fintech operations.
Operations: Marygold generates most of its revenue from related-party fund management at about $21 million, with smaller contributions from beauty products at $3 million and financial services at $1 million.
Market Cap: $85 million
Marygold Companies gives you direct exposure to ETF management at a time when higher Treasury yields are leading some investors to reconsider long-duration bond wrappers. Its ETF advisory activity is closely linked to demand for specialized fixed-income products. The business also has funding and profitability challenges that could change significantly if a single ownership outcome alters the cost and flexibility of its ETF ambitions.
If a single ownership shift could reshape Marygold Companies’ funding playbook, the Marygold Companies financial health report might show how that balance sheet risk is really wired.
Victory Capital Holdings (VCTR)
Overview: Victory Capital Holdings runs a multi-boutique asset manager and ETF platform that offers debt and inflation-hedging strategies directly tied to long-duration themes.
Operations: Victory Capital Holdings generates about $1.6 billion in revenue from providing investment management services and related products across its platform.
Market Cap: $6.7 billion
Victory Capital Holdings matters for this long-duration ETF screen because its growing ETF platform, fixed income heritage and acquisitive model can all funnel fresh assets into products built for higher rate volatility and inflation concerns.
Victory Capital Holdings is pursuing the acquisition of First Eagle Investments for about US$7b. This transaction is expected to add roughly US$3.2b in annual revenue and expand the combined asset base to around US$571b, creating scope for a larger earnings pool once integrated and contributing to future EPS.
What investors will be watching next is how one pressure point on funding costs and leverage reshapes the room for long-duration growth.
That funding squeeze is exactly why the full narrative for Victory Capital Holdings digs into how Victory Capital Holdings could keep compounding through integration risk, capital intensity, and long-duration ETF momentum.
Invesco (IVZ)
Overview: Invesco is a global investment manager that runs mutual funds and ETFs, including U.S. Treasury and TIPS products, for a wide range of clients.
Operations: Invesco generates about $6.9b from investment management, with revenue concentrated in the Americas at roughly $5.2b and supported by EMEA and APAC.
Market Cap: $12.7b
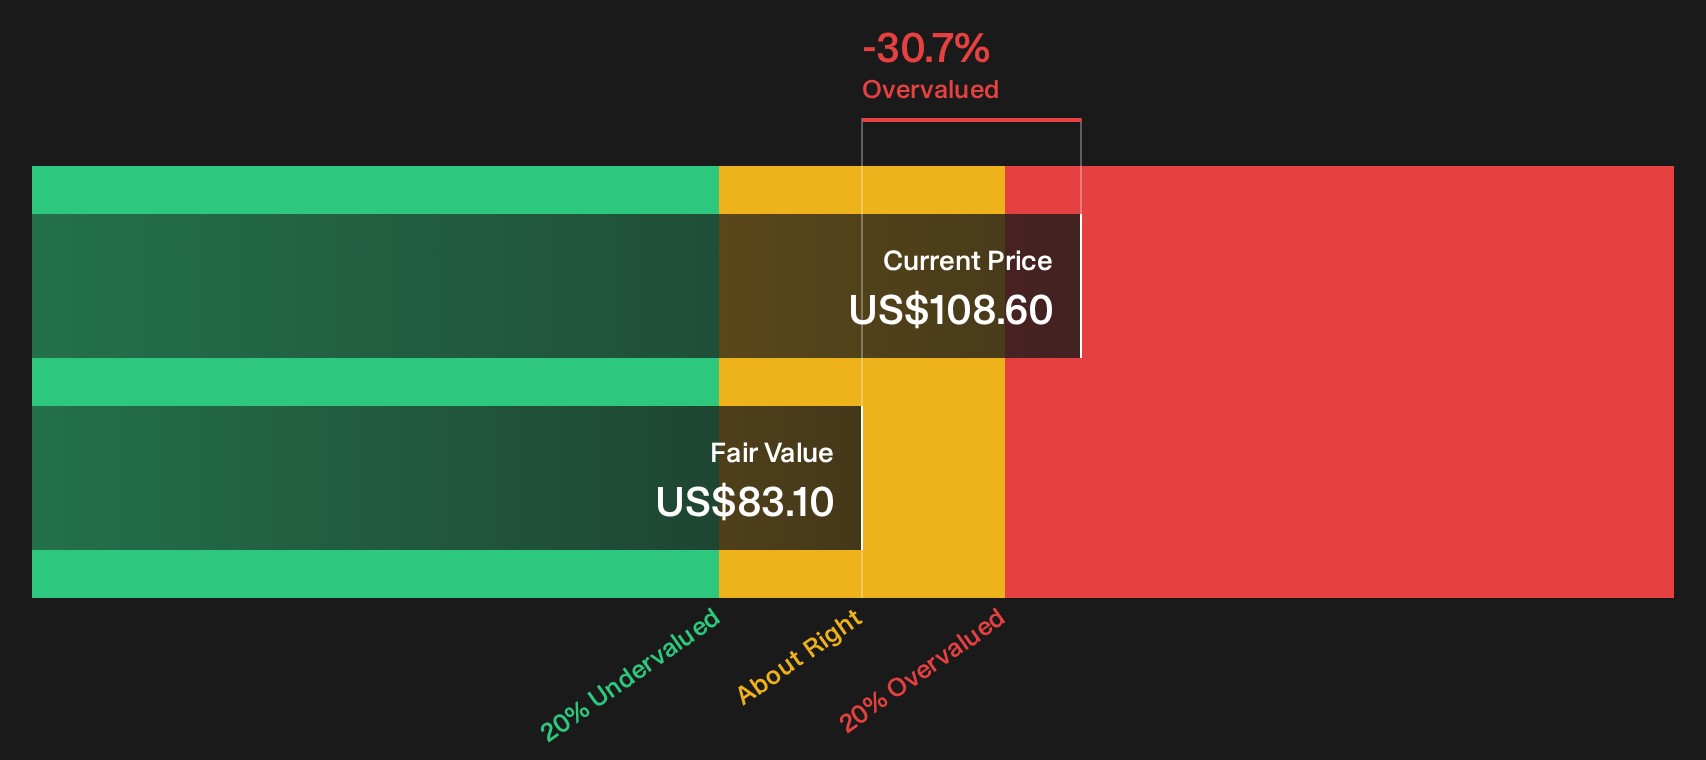
Invesco matters for this long-duration ETF theme because its Treasury and TIPS products sit inside a broad ETF and index platform that directly converts investor demand into fee income when bond duration and inflation protection move back into focus.
"Invesco's strong growth in global ETF and index products (notably QQQ and QQQM) and ongoing innovation in both active and passive strategies position the firm to benefit from the continued investor shift towards low-cost, scalable investment options, supporting asset growth and potentially higher fee-based revenue and operating margins."
The real swing factor is how one persistent pressure on fixed income demand ultimately feeds through to fee rates and operating leverage.
That fee pressure question is exactly what the full narrative for Invesco unpacks, highlighting where Invesco’s ETF engine could still accelerate despite duration angst and shifting inflation bets.

Seeking Fresh Alternatives Before They Fly
Markets move fast and the next breakout theme rarely stays under the radar for long. Track fresh momentum, spot what others miss and get in early.
- Target robust income streams by scanning companies in the 8 dividend fortresses and see which yields still look sustainable before prices start reacting.
- Spot early trend leaders with the 55 AI infrastructure stocks and focus on businesses building the picks and shovels behind the next leg of AI spending.
- Track future-facing industrial demand using the 32 best rare earth metal stocks and identify miners that could become more important if electrification continues to pull these metals into focus.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com