
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Emerson Electric (EMR) Stock Still Looks Stretched On Current Earnings
Emerson Electric has delivered a powerful share price run in recent years, which naturally puts the spotlight on whether the current market value lines up with what its earnings can support. With the stock recently closing at US$161.47, the key issue is whether that level is grounded in the business it earns today rather than the story around it.
- The share price has climbed 86.1% over the past 3 years, which raises the question of how much future profit strength is already reflected in the valuation.
- Emerson Electric’s focus on industrial automation and process control can support expectations for relatively durable earnings and cash generation, which feeds directly into how much investors are prepared to pay for each dollar of profit.
- The analysts covering Emerson Electric have run their own numbers. See what analysts think Emerson Electric's shares could be worth.
For investors, the debate is whether Emerson Electric’s current share price is justified by the level and quality of its earnings today.
If you are weighing whether Emerson Electric’s P/E still makes sense after an 86.1% three year run, it can help to compare it with a focused list of 33 high quality undervalued stocks.
Has Emerson Electric Run Too Far on Earnings?
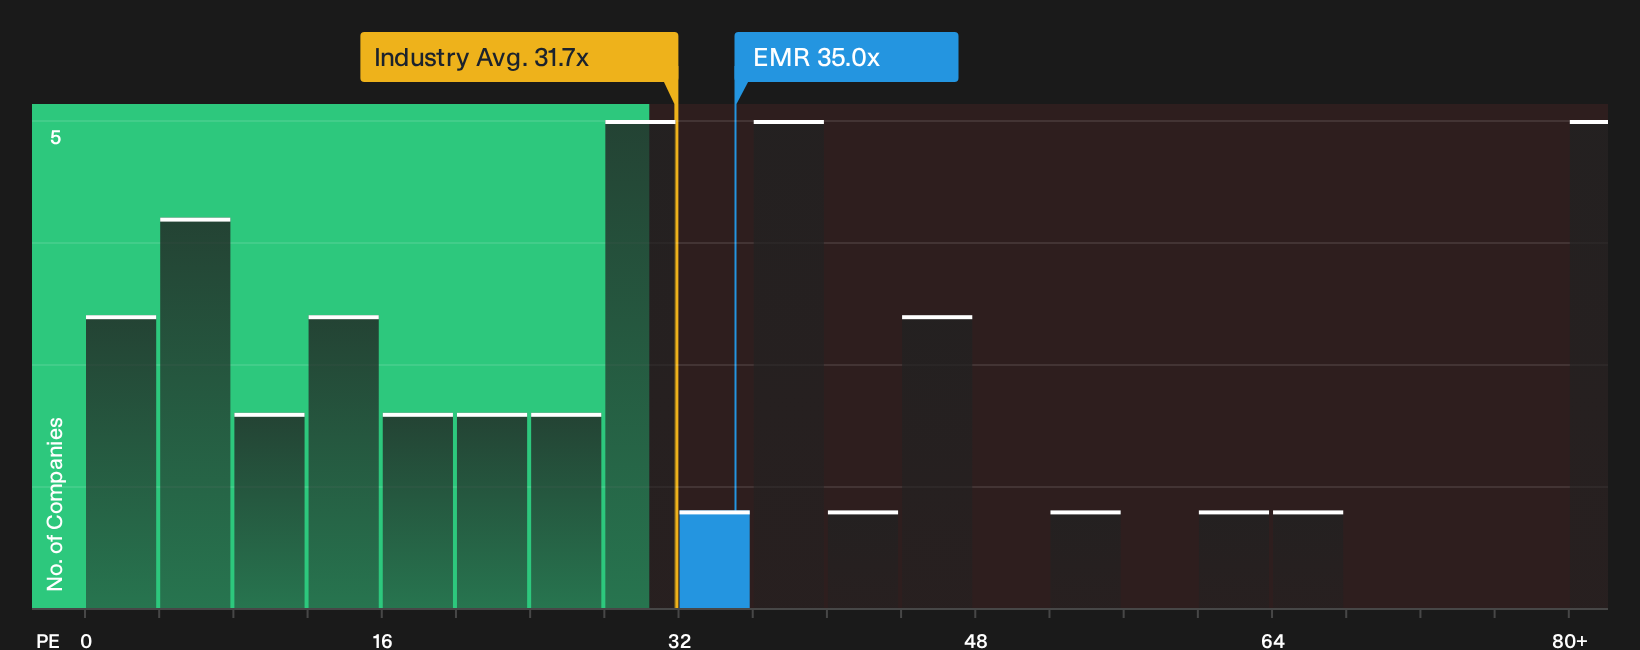
The P/E ratio suits Emerson Electric because earnings are a key anchor for how investors weigh a mature industrial automation group. On this measure, the shares trade at about 35.0x earnings, which is above the Electrical industry average of roughly 31.7x, yet below a peer group closer to 40.3x. That places the stock at a premium to the broader sector, but not the richest option in its immediate competitive set.
A tailored fair P/E that adjusts for Emerson Electric’s growth profile, profitability, size and risk points to a lower multiple than where the shares change hands today. The current valuation is therefore higher than what this framework would normally attach to the business, which means buyers are paying up for the quality and perceived resilience of its earnings stream. Whether that premium feels acceptable depends on how much weight you put on the durability of its industrial automation cash flows and the consistency of its future profit delivery relative to other Electrical stocks. Explore the numbers behind Emerson Electric's P/E valuation.
The Emerson Electric Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Emerson Electric valuation puzzle leaves off. They spell out which expectations for growth, margins and earnings would need to hold for the stock to be worth materially more or less than today's price. Each Narrative treats fair value as a thesis about the business that you can watch evolve over time, rather than a single frozen snapshot, all hosted on Simply Wall St's Community page.
The Simply Wall St community is split on Emerson Electric, with one camp seeing upside from software and project funnels while the other worries that long cycle bets and renewals are already fully priced in.
Bull case: 7% undervalued
"Emerson Electric's focus on subscription-based software and recurring revenue streams is reinforced by software annual contract value of about US$1.64b to US$1.68b, which grew 9% year over year in recent quarters…"
Discover why this Narrative puts Emerson Electric at 7% undervalued.
Bear case: 19% overvalued
"While the company reports 9% software annual contract value growth to about US$1.68b and reiterates a 10% plus ACV goal, the recent software renewal headwind cut Software & Systems margins by 150 basis points in Q3 and 300 basis points year to date…"
Explore why this Narrative puts Emerson Electric at 19% overvalued.
One more angle on Emerson Electric that could change the picture
Share price, earnings and P/E only tell part of the story, because the people setting Emerson Electric’s priorities and how they are rewarded can push outcomes in very different directions. See who runs Emerson Electric and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com