
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Tractor Supply (TSCO) Faces A Mixed Spending And Pet Growth Story Following Fair Value Debate
Recent concern around slowing same store sales and cautious rural spending has put Tractor Supply (TSCO) under the microscope as investors weigh inflation and higher Treasury yields against its automation and pet care expansion plans.
The share price story reflects that mixed backdrop. Tractor Supply’s stock has fallen about 35% on a year to date share price basis, and the 1 year total shareholder return is down about 38%. This is even after a roughly 9% share price gain over the past 90 days as investors reassess automation, pet care growth and inflation risks.
Compare Tractor Supply’s setup with a hand picked 33 high quality undervalued stocks that also face inflation pressure and shifting consumer demand but score better on value and balance sheet strength.
Tractor Supply still runs a sizable rural retail operation and a growing pet ecosystem, yet the share price has been hit hard this year. After that drop and recent rebound, does the current price genuinely offer value?
Most Popular Narrative: 6.5% Undervalued
On the most followed view, Tractor Supply’s fair value estimate of about $35.48 sits modestly above the recent $33.16 close. This puts the focus squarely on whether its pet ecosystem, automation plans and capital allocation choices can justify that gap.
The growing pet ecosystem that now links assortment resets, over 200 new pet products, Freshpet coolers, subscriptions projected above US$200 million in 2026, and the acquisition of VIP Petcare with access to about 1 million pets annually may support steadier pet category revenue and earnings contribution.
See why 44 investors see Tractor Supply as 7% undervalued.
Result: Fair Value of $35.48 (UNDERVALUED)
Still, if comparable sales keep slipping and tariff refunds run out before freight and fuel ease, the current Tractor Supply narrative could come under pressure.
Find out about the key risks to this Tractor Supply narrative.
Another View: Multiples Paint A Tougher Picture For Tractor Supply
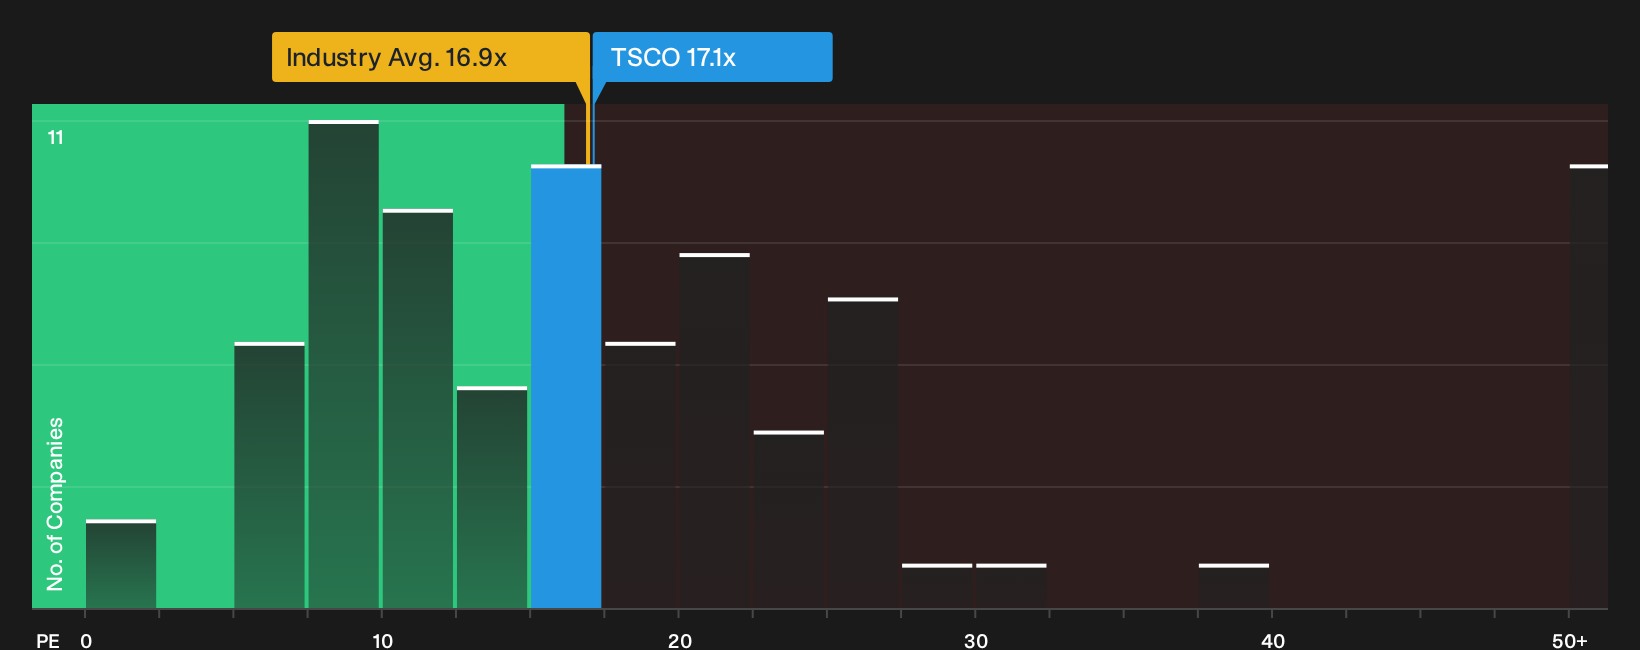
The first story leans on a fair value of $35.48 and an 18.6% discount to that estimate. On plain P/E maths, Tractor Supply looks less generous. The stock trades at 17.1x earnings, slightly above the US Specialty Retail industry at 16.9x and above a fair ratio of 15.4x, which points to some valuation risk if sentiment cools again.
Those gaps are not huge, but they matter. A move toward the 15.4x fair ratio would mean the share price doing more work to justify the premium over peers rather than the multiple expanding for free. It is therefore worth asking which story you trust more when you line it up with your own expectations for pet services, automation and comparable sales trends.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Tractor Supply story so far. If you want to move fast and judge the risk reward trade off directly, start with the 2 key rewards and 2 important warning signs.
Looking for more Tractor Supply investment ideas?
If Tractor Supply has your attention, do not stop here. Broaden your watchlist with fresh opportunities that match different risk levels, income needs and quality filters.
- Target higher income potential by scanning for resilient payers in the 8 dividend fortresses that may suit a regular cash flow focus.
- Hunt for quality at a discount using the 20 high quality undiscovered gems that highlight under-followed companies with strong underlying fundamentals.
- Dial down portfolio stress by checking the 32 resilient stocks with low risk scores that filters for businesses with more defensive risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com