
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Corteva (CTVA) Stock Trades At A Premium Despite Its 3% Dip
Corteva has just been reshaped into a pure crop protection and digital agriculture business after spinning off its seed arm, and the share price has eased 2.7% over the past week. That combination of restructuring and a softer short term move leaves an open question around whether the current valuation lines up with the earnings power of the refocused company.
- The stock slipped 2.7% over the past seven days, which puts the current earnings based valuation debate front and center for anyone tracking Corteva.
- The Vylor spin-off and refocus on crop protection, with an $11b product pipeline and projected EBITDA of about $1.4b next year, can reshape how investors think about Corteva's profit mix and the sustainability of its earnings stream.
- There is a second opinion on Corteva worth weighing. See what analysts think Corteva's shares could be worth.
The issue now is whether Corteva's current share price is adequately supported by its earnings when set against the industry average.
If you are weighing Corteva on its earnings against the rest of the crop chemicals space, it can help to stack it up beside 33 high quality undervalued stocks
Does Corteva Look Pricey on Earnings?
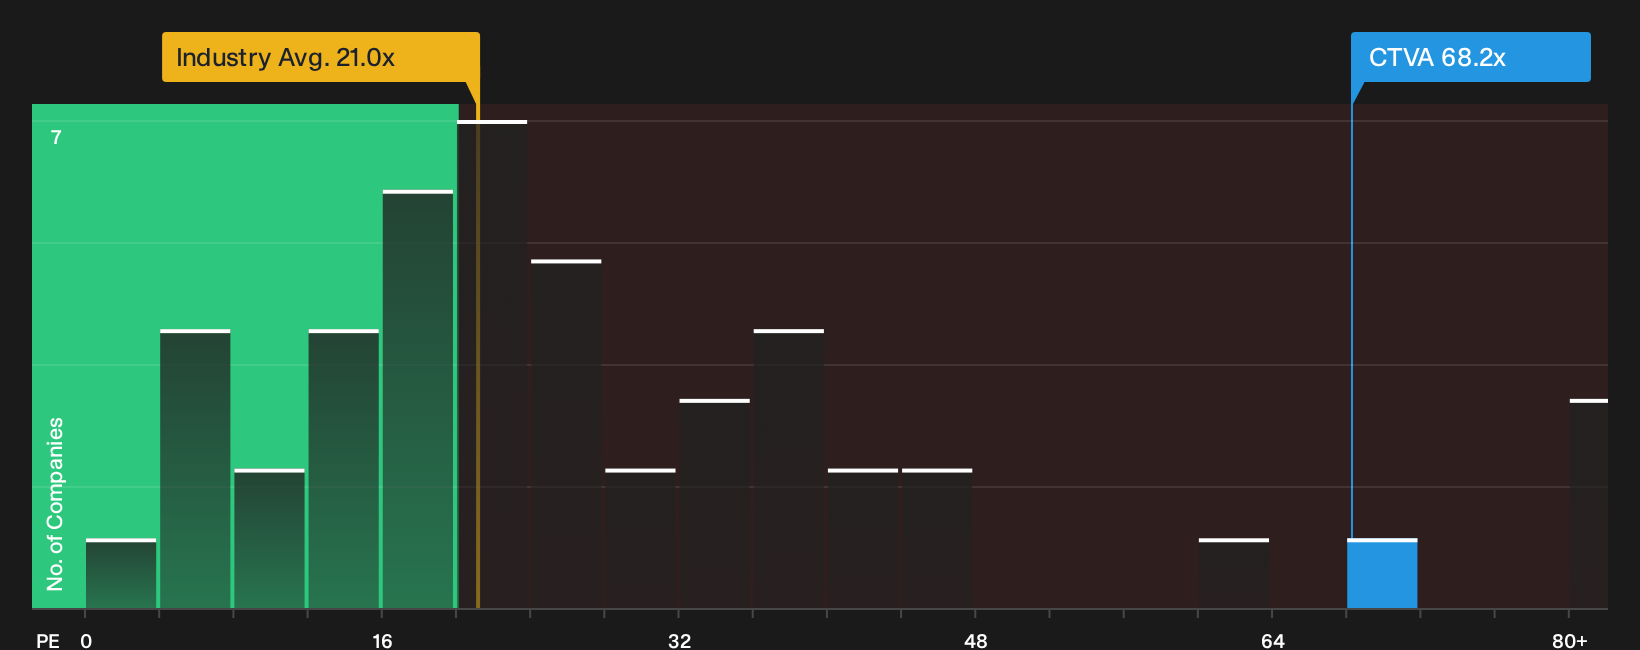
The P/E lens suits Corteva because the business is now reshaped around earnings from crop protection products rather than seed royalties. On this measure, Corteva trades at about 68.2x earnings, which is more than three times the broader chemicals industry average of roughly 21.0x. Against a peer group sitting nearer 14.6x, the stock also prices in a much richer earnings tag per dollar of profit.
Because the recent Vylor spin-off has reset Corteva as a focused crop protection and digital platform, that premium P/E multiple leaves very little room in the headline ratio itself before the shares screen as overvalued against sector yardsticks. Despite the projected EBITDA targets and talk of earnings growth after 2027 in recent coverage, the current earnings multiple already bakes in a lot of optimism relative to both the industry and closer peers. Explore the numbers behind Corteva's P/E valuation.
The Corteva Narrative: What Would Justify Today's Price?
Narratives on Corteva pick up exactly where this valuation puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to play out for the stock to look meaningfully cheap or expensive relative to today's price. Each one sets out Corteva's implied fair value as a specific business thesis that you can track over time, rather than a single frozen estimate, and they live on Simply Wall St's Community page.
A written, number driven view on Corteva helps pin down what would need to happen for the refocused crop protection business, including its US$11b pipeline and projected US$1.4b EBITDA, to line up with the current P/E premium. It also gives you a clear way to track whether developments like the Vylor spin off and the crop chemicals legal overhang move Corteva's earnings story toward or away from those assumptions as new results and news arrive.
Share your own Narrative for Corteva and set out the assumptions behind your valuation.
Before acting on Corteva's valuation, there is one more angle to check
Price tags tell only part of the story for Corteva, because the people steering the business and the way they are rewarded can either support or undermine the case you are building. See who runs Corteva and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com