
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Executive Layoffs At Universal Music Group (ENXTAM:UMG) Have Changed Its Investment Story
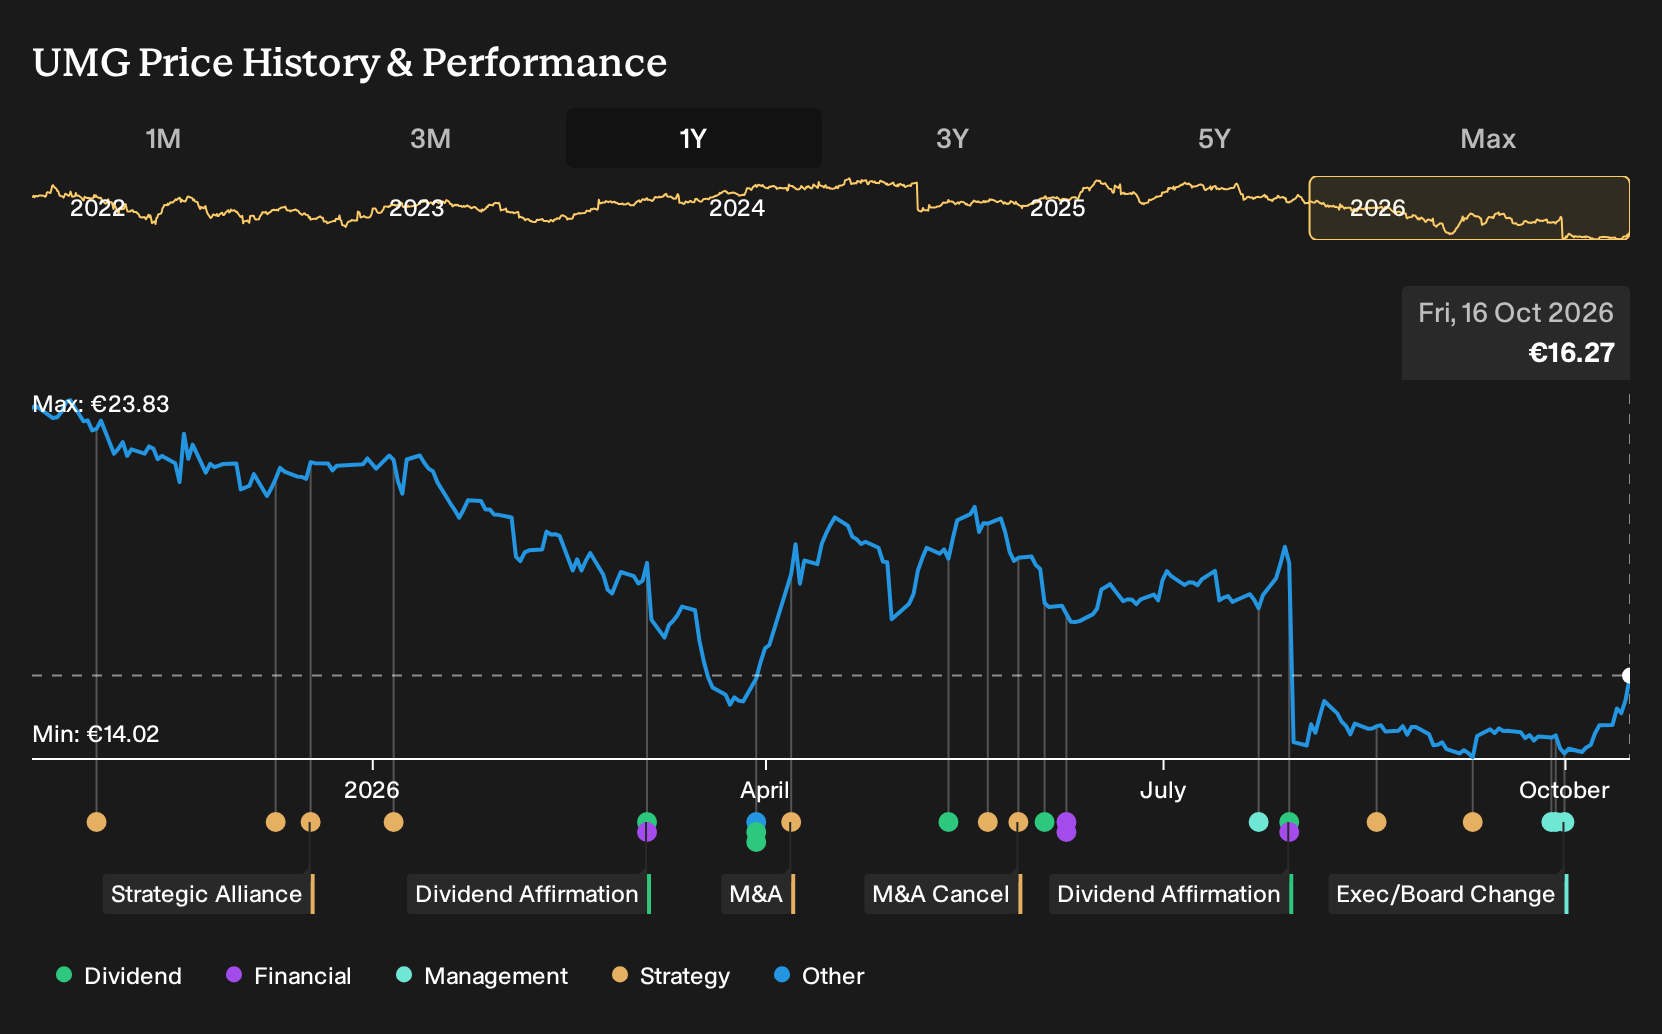
- Universal Music Group has undertaken a wide restructuring in 2024 and 2026, cutting staff and reshaping senior leadership across major labels to support a planned €250 million annual cost saving target by 2027.
- The layoffs have affected high profile roles and raised questions about leadership diversity and continuity at the same time that Universal Music Group pursues AI, Streaming 2.0 and emerging market initiatives.
- The focus now shifts to how Universal Music Group's cost cutting and executive turnover could reshape the long term investment narrative.
Universal Music Group Investment Narrative Recap
To stay invested in Universal Music Group, you need to believe the music catalogue, Streaming 2.0 deals and AI licensing model can support healthier earnings over time even as formats keep shifting. In the short term, the main swing factor is how effectively management executes the €250 million cost saving plan without disrupting artist campaigns, dealflow or Streaming 2.0 negotiations.
The largest operational risk today sits in margin pressure and weaker recent free cash flow, paired with high debt and a dividend that is not well covered by earnings. The latest layoffs and leadership changes matter if they slow execution on AI partnerships, merch turnaround and emerging markets; otherwise the financial impact is likely limited.
The subpoena push involving DistroKid around AI generated uploads is the announcement that connects most directly to this restructuring story. Universal Music Group is already leaning on AI licensing as a key earnings catalyst, and this legal stance goes to the heart of how much control the business can retain over catalog usage in AI tools and pseudo user generated tracks.
If enforcement efforts translate into cleaner data, clearer rules for distributors and more consistent payouts from partners, that outcome could support the Streaming 2.0 and AI royalty thesis. If they drag on cash costs or strain relationships with distribution platforms, the situation would compound existing risks around under monetized short form content and already thin profit margins.
Universal Music Group Analyst Case in Numbers
Universal Music Group's consensus story hinges on a fairly specific set of numbers. Analysts are working off an assumption that revenue can rise by 6.9% per year over the next few years, while profit margins move from 2.5% today to 11.3% by around 2029. That earnings bridge runs from current profit of €323.0 million to a forecast €1.8 billion, which implies an earnings increase of about €1.5 billion by 2029. On these estimates, the business would generate about €15.6 billion of revenue in 2029, with earnings of €1.8 billion in the same year.
Universal Music Group's narrative projects €15.6 billion revenue and €1.8 billion earnings by 2029. This requires 6.9% yearly revenue growth and an earnings increase of about €1.5 billion from €323.0 million today.
Uncover how Universal Music Group's fair value indicates a 33% potential upside to its current price, an opportunity that could narrow quickly if Universal Music Group executes the analyst playbook.
Exploring Other Perspectives
One alternate view focuses on AI enforcement risk rather than AI upside. The most cautious Universal Music Group analysts were already baking in €15.6 billion of revenue and €1.8 billion of earnings by 2029, yet only saw a €12.0 target. You can treat the new DistroKid subpoenas as a live test of whether that more pessimistic AI story sticks or needs a rewrite.
Explore 6 other Universal Music Group fair value estimates, including one that suggests as much as 26% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Universal Music Group research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Universal Music Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Universal Music Group's overall financial health at a glance.
Looking for more Universal Music Group style investment ideas?
If the Universal Music Group story has sharpened your thinking on risk, cash generation and long term earnings power, it can help to line that view up against a wider watchlist built with a consistent framework. The Simply Wall St Screener lets you do exactly that by filtering for financial traits that match how you prefer to balance upside and resilience.
- For investors who care most about balance sheet strength and fundamental quality, use the list of solid balance sheet and fundamentals (203 results) to focus on businesses with the financial resilience to handle shocks.
- If your priority is keeping downside risk in check, start with the 233 resilient stocks with low risk scores and concentrate on companies that score well on overall risk metrics.
- When you want potential mispricing ideas to compare with Universal Music Group, broaden your shortlist with the 618 high quality undiscovered gems that combine solid fundamentals with less market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com