
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Dropbox (DBX) Sets Q3 Results Date, Is The Stock Fully Valued?
Dropbox (DBX) has set its next catalyst, with third quarter 2026 results scheduled after the market close on Thursday, November 5, 2026. This will be followed by an investor conference call and webcast later the same day.
Recent trading has been choppy for Dropbox, with the share price down 5.75% over the past month but still up 16.17% over 90 days and showing a 32.08% year to date share price return. The 1 year total shareholder return of 22.21% points to momentum that has cooled slightly but not reversed.
Scan beyond Dropbox and identify your next catalyst-driven idea with our curated list of 33 high quality undervalued stocks, which highlights opportunities showing solid recent performance and balance sheet support.
Dropbox’s pullback over the past month sits awkwardly against its stronger 90 day and year to date gains. Is this price action catching up with the business, or is sentiment simply resetting before the next valuation check?
Most Popular Narrative: 11.9% Overvalued
Dropbox closed at $35.57 compared with a widely followed fair value estimate of $31.80, so the key question is whether the current price already bakes in the most optimistic version of the cash flow story.
A combination of high free cash flow, a roughly 15% year over year reduction in diluted share count, a new US$400m revolving credit facility, and an additional US$900m buyback authorization positions Dropbox to keep shrinking its share base. This can support growth in free cash flow per share and earnings per share even if revenue growth remains modest.
See why 10 investors see Dropbox as 12% overvalued.
Result: Fair Value of $31.80 (OVERVALUED)
Still, the Dropbox story can break if rising AI and infrastructure costs keep eroding gross margins, or if further security incidents undermine user trust and paid adoption.
Find out about the key risks to this Dropbox narrative.
Another View On Dropbox’s Valuation
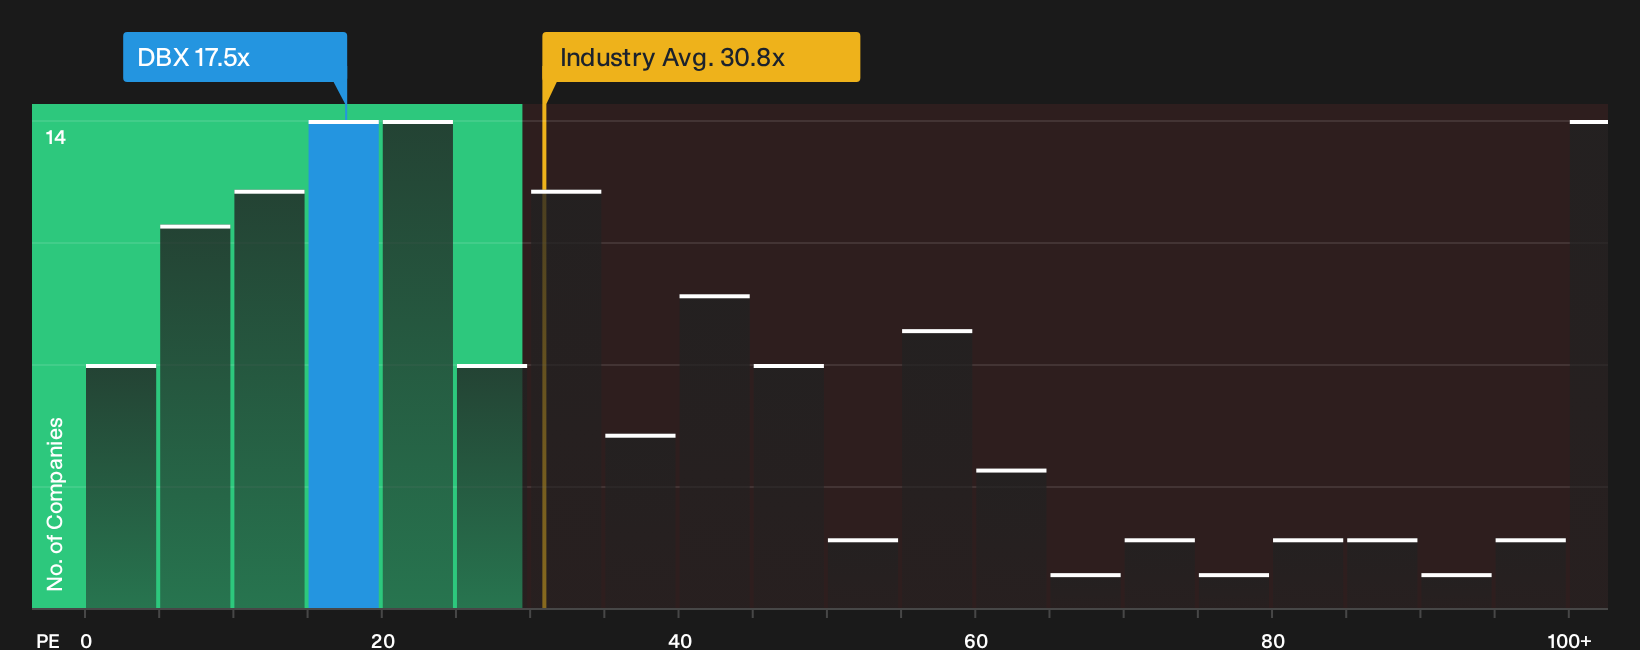
The analyst fair value of $31.80 implies Dropbox is 11.9% overvalued, yet its current P/E of 17.5x looks cheap next to the US Software industry at 31.3x and peers at 27.9x. It also sits below an estimated fair ratio of 21.5x. Is the market underpricing the risk, or the opportunity?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Dropbox’s valuation story and risk profile can feel messy, so move quickly, review the underlying data, and weigh 2 key rewards and 3 important warning signs
Ready For More Investment Ideas Beyond Dropbox?
If you stop with Dropbox, you only see one angle. Cast a wider net now and let the data surface ideas you might otherwise miss.
- Target resilient compounding potential by scanning a curated 32 resilient stocks with low risk scores that aims to limit downside while still giving you meaningful upside candidates.
- Hunt for mispriced quality by focusing on a select 20 high quality undiscovered gems that many investors may not yet be watching closely.
- Prioritise balance sheet strength with a focused list of solid balance sheet and fundamentals (25 results) that filters for companies backing their story with robust financial foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com