
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
EPA Rule Change Might Change The Case For Investing In Green Plains Stock (GPRE)
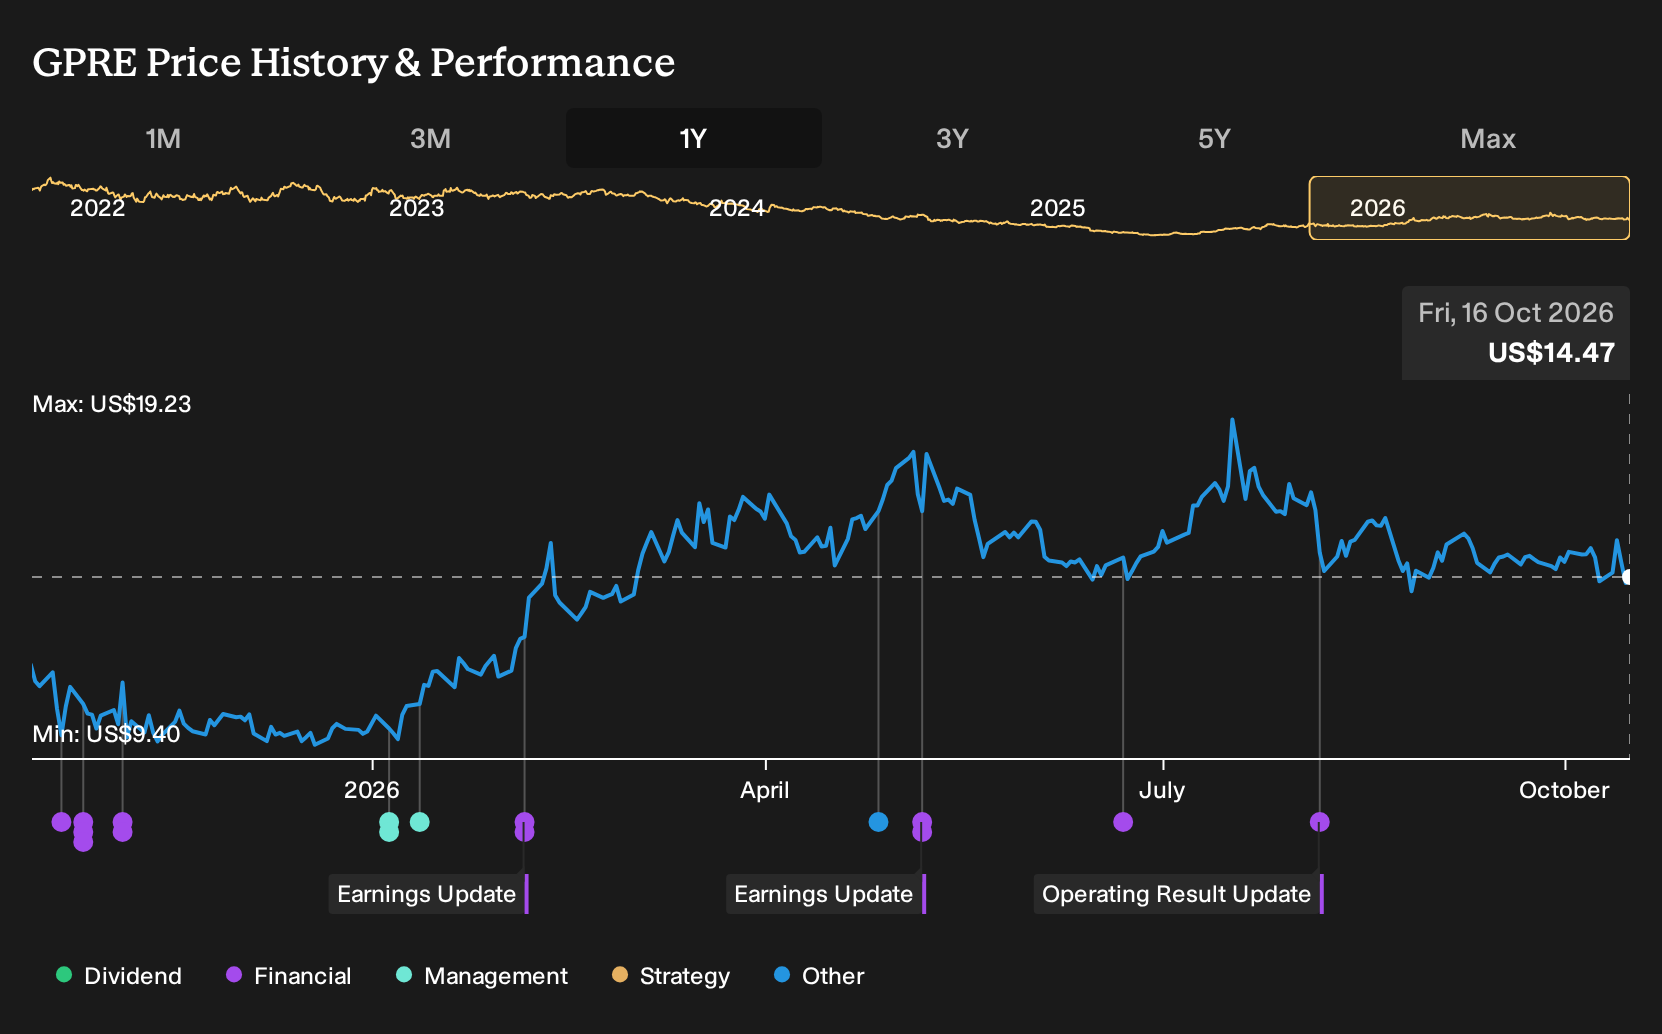
- The Environmental Protection Agency recently proposed changes to the Renewable Fuel Standard that would reallocate previously waived small refinery exemptions, aiming to preserve ethanol blending volumes and support producers like Green Plains that focus on low carbon fuels.
- The same policy push, including the extended 45Z clean fuel production tax credit through 2029, directly targets recurring revenue streams from Green Plains' low carbon ethanol and coproduct output rather than just one off project incentives.
- We will now look at how this expanded 45Z tax credit support could reshape Green Plains' longer term investment narrative for investors.
Scan other low carbon fuel opportunities with a similar policy tailwind by reviewing the 41 power grid technology and infrastructure stocks alongside your work on Green Plains.
Green Plains Investment Narrative Recap
To own Green Plains, you need to believe the ethanol platform can steadily convert policy support into repeatable cash flow from low carbon fuels and coproducts. The recent EPA proposal to reallocate small refinery exemptions points in that direction by supporting ethanol blending volumes, which helps plant utilization and keeps the low carbon thesis intact in the near term.
The most important short term swing factor is still execution on efficiency gains and higher value coproducts while staying profitable. Policy risk remains the biggest overhang. Green Plains relies heavily on credits such as 45Z and carbon capture incentives, so any future change or delay in these programs could pressure earnings and valuation.
The extended 45Z clean fuel production tax credit through 2029 ties directly into this latest EPA move. Both developments speak to the same theme: policy is currently structured to reward lower carbon intensity fuels, which is exactly where Green Plains is trying to push its ethanol and coproduct portfolio.
For you as an investor, that tax credit extension is less about a one time boost and more about potential visibility. Management can plan plant upgrades and carbon intensity improvements knowing that qualifying volumes may earn credits for several years, while still facing ongoing execution risk, commodity volatility, and the possibility that policy support changes later on.
Green Plains' current loss of $15.4 million is set against analyst expectations that earnings reach $158.0 million by 2029. This implies an earnings swing of roughly $173 million, alongside forecast revenue growth of 18.5% per year and revenues of $3.2b in 2029.
Discover why Green Plains' fair value indicates a 22% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate take on Green Plains focuses on demand risk from electric vehicles rather than policy support. The most cautious analysts were penciling in slower revenue growth at about 2.9% a year and 2029 earnings of roughly $151.0 million before this news. That is a far more muted narrative. Use it as a prompt to compare several viewpoints and decide which assumptions feel more realistic to you.
Explore 2 other Green Plains fair value estimates, including one that suggests it could be worth just $17.71!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Green Plains research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Green Plains. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Green Plains' overall financial health at a glance.
Looking for more investment ideas beyond Green Plains?
Once you have formed a view on Green Plains, it can help to cross check that thesis against other opportunities with clear financial profiles using the Simply Wall St Screener.
- If you care most about valuation support, scan a curated set of 33 high quality undervalued stocks that combine quality fundamentals with prices that may be out of sync with their underlying metrics.
- If resilience matters more to you than excitement, focus on 32 resilient stocks with low risk scores that aim for steadier balance sheets and fewer red flags in their risk profiles.
- If you want financially robust businesses first, followed by growth stories, start with a list of solid balance sheet and fundamentals (25 results) and filter from there based on your own return and risk preferences.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com