
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Japan Post Holdings (TSE:6178) Climbed, What Is Driving Attention Now?
Recent Performance Snapshot for Japan Post Holdings
Japan Post Holdings (TSE:6178) has come into focus after a recent move in its share price, with the stock closing at ¥2,427 and short term returns showing mixed momentum.
Over the past week the stock gained about 3%, while the past month showed a decline of roughly 3%. Over the past 3 months, the share price logged a gain of about 4%, with the 1 year total return figure near 78%.
Investors tracking Japan Post Holdings may also notice year to date total returns around 40%. Those numbers sit alongside reported annual revenue of about ¥11.47b and net income of roughly ¥432m, reflecting a broad footprint across postal, banking, and insurance activities.
For Japan Post Holdings, the recent 1 day share price return of 2.6% and 7 day gain of 3% sit against a 30 day share price pullback of about 3%, while the 1 year total shareholder return of roughly 78% signals strong longer term momentum. Short term swings around ¥2,427 hint at investors reassessing both the growth potential in the postal, banking, and insurance operations, as well as the risks that come with such a broad financial and logistics footprint over time.
Scan how Japan Post Holdings stacks up against other large, diversified financial and logistics groups by comparing it with list of solid balance sheet and fundamentals (21 results) in one place.
Bulls point to Japan Post Holdings’ broad mix of postal, banking, and insurance activities and recent double digit returns. Bears focus on the recent pullback and complexity. Which story do the current valuation markers support next?
Price-to-Earnings of 15.4x: Is it justified?
Japan Post Holdings is trading on a P/E of 15.4x, which lines up with a share price of ¥2,427 that looks rich against both peers and the wider Asian insurance sector.
The P/E multiple compares what investors are paying today with the company’s earnings. For a group spanning postal, banking, and insurance activities, that ratio becomes a quick shorthand for how the market weighs its profit profile against more focused insurers and financial groups.
Here the signal is clear. The stock is described as expensive versus both its direct peer average of 11.9x and the broader Asian insurance cohort at 10.7x. This means buyers are currently paying a higher price for each unit of earnings than the sector norm. At the same time, the estimated fair P/E of 17.6x is higher than the current 15.4x. This points to a level the market could move toward if earnings forecasts and quality hold up.
Explore the SWS fair ratio for Japan Post Holdings.
Result: Price-to-Earnings of 15.4x (OVERVALUED)
Still, Japan Post Holdings faces potential setbacks if complex banking and insurance operations drive earnings volatility, or if property and logistics exposure weigh on profitability.
Find out about the key risks to this Japan Post Holdings narrative.
Another View on Japan Post Holdings’ Value
The P/E ratio paints Japan Post Holdings as expensive, yet the SWS DCF model shows a more muted picture. With the share price at ¥2,427 versus an estimated future cash flow value of ¥2,376.44, the stock screens only slightly overvalued on this lens. That raises a simple question for investors: Is a narrow gap like that enough to justify paying up for a complex postal, banking, and insurance group?
For readers who want to see how this cash flow approach is built from the ground up, including the key assumptions that sit behind the output, Look into how the SWS DCF model arrives at its fair value.
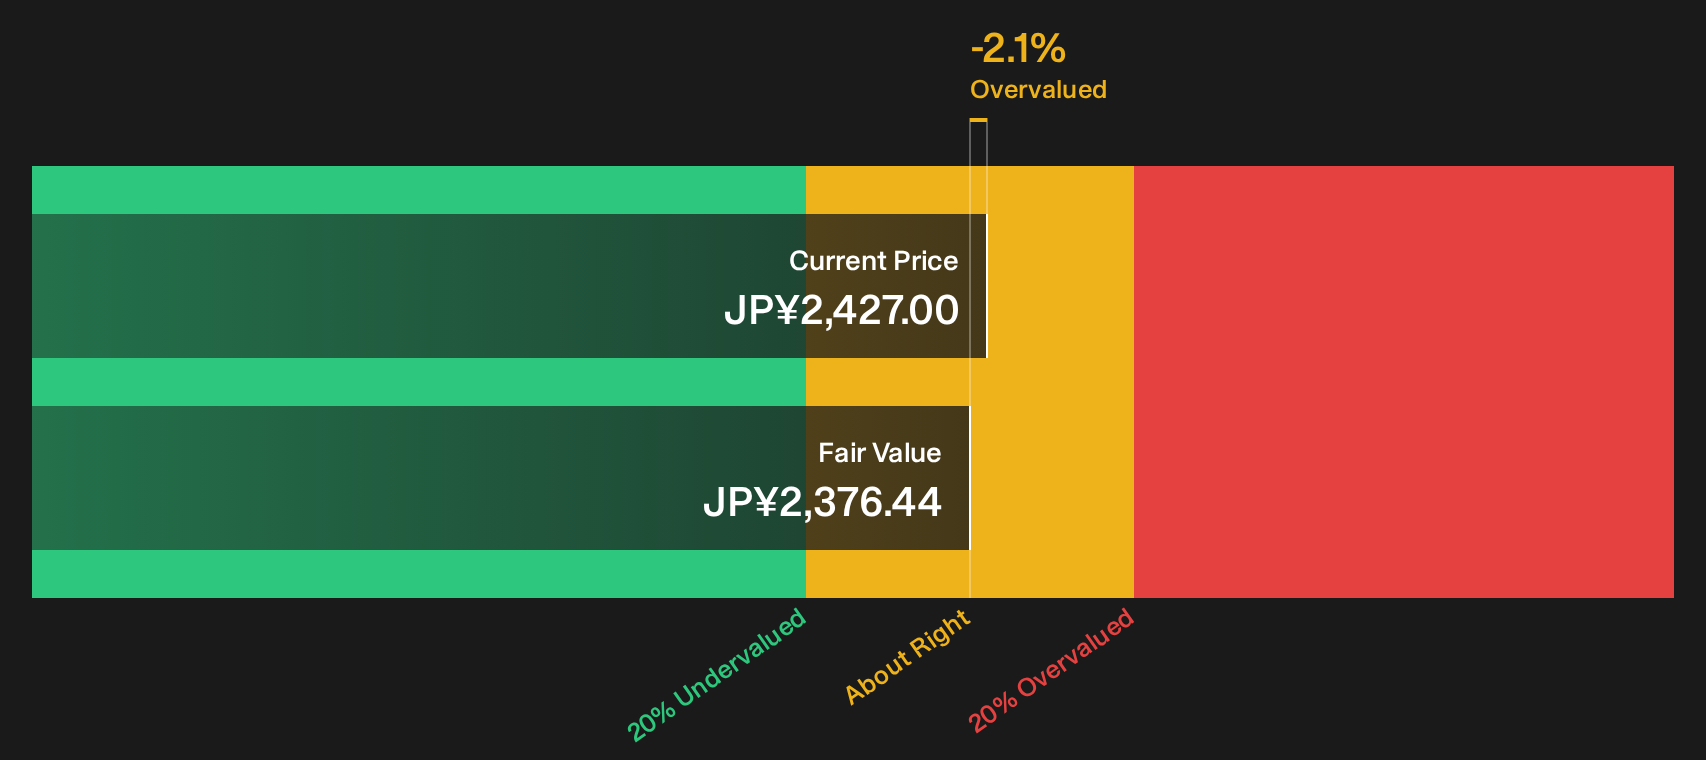
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Japan Post Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Japan Post Holdings is clearly split, with both bright spots and pressure points on show, so move quickly and inspect the data yourself. To weigh these mixed signals and decide what matters most for your portfolio, start with the 1 key reward and 1 important warning sign
Looking for more investment ideas beyond Japan Post Holdings?
If Japan Post Holdings has sharpened your focus on valuation and quality, do not stop here. Broader opportunities sit just a few clicks away.
- Target resilient balance sheets and disciplined fundamentals with the list of solid balance sheet and fundamentals (21 results).
- Hunt for mispriced opportunities where quality and value intersect using the 14 high quality undervalued stocks.
- Lock in income potential by screening for stronger yield candidates through the 29 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com