
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Starwood Property Trust (STWD) Is Back In The Spotlight
Starwood Property Trust (STWD) is back in focus after a sharp year-over-year earnings drop tied to prior one-off gains and a large credit loss provision reflecting a tougher economic outlook.
At a share price of $12.46, Starwood Property Trust has seen momentum fade in 2024, with the 30 day share price return down 16.82% and the year to date share price return down 32.36%, while the 1 year total shareholder return has declined 24.50% as investors weigh the premium P/E multiple against earnings volatility, credit loss provisioning, and debate over the value of its loan book.
Scan beyond Starwood Property Trust and compare how other income-focused plays are handling credit risk with our curated list of 8 dividend fortresses.
Starwood Property Trust has a diversified lending and property platform that many investors respect. Yet the sharp share price slide and premium P/E raise a blunt question: Is a solid REIT now offered at a fair price or still expensive?
Most Popular Narrative: 37% Undervalued
On the most followed view, Starwood Property Trust screens as undervalued, with a fair value estimate of $19.88 versus the last close at $12.46. This puts the focus squarely on how quickly tied up capital can be recycled back into earning assets.
Systematic workout and recycling of roughly US$1.9b of nonaccrual and REO assets, including guidance to resolve about US$800m or 40% of the current balance by year end 2026 and the expected US$140m cash out from the Woodstar refinancing, provides a pipeline of capital that can be redeployed into higher yielding opportunities and potentially improve earnings and dividend coverage.
See why 51 investors see Starwood Property Trust as 37% undervalued.
Result: Fair Value of $19.88 (UNDERVALUED)
Still, the tight dividend coverage and heavy exposure to US$1.9b of nonaccrual and REO assets could flip the Starwood Property Trust story if outcomes disappoint.
Find out about the key risks to this Starwood Property Trust narrative.
Another View: SWS DCF Flags Overvaluation
The fair value story for Starwood Property Trust looks very different when using the SWS DCF model. On this approach, the estimated future cash flow value sits at $5.07 per share, well below the current $12.46 price. This screens as materially overvalued rather than cheap.
That kind of gap can matter for income investors who care about capital preservation as much as yield. It raises a simple question: is the market correctly pricing dividend risk, or is the cash flow view too harsh for a REIT with Starwood Property Trust's profile?
Look into how the SWS DCF model arrives at its fair value.
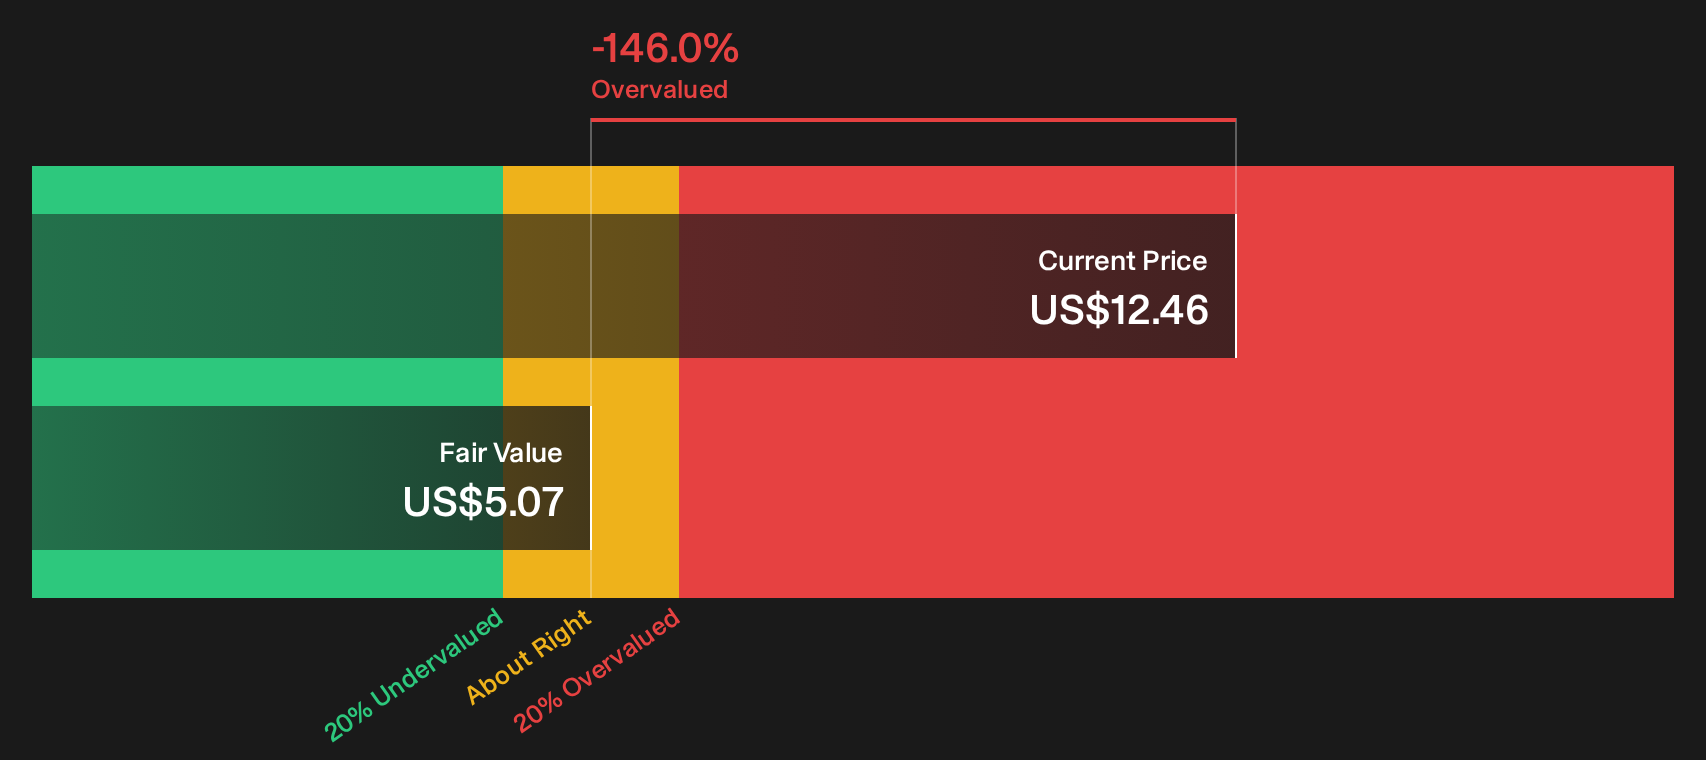
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Starwood Property Trust for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Starwood Property Trust is clearly divided. Investors may want to act promptly, review the available data, and consider both the downside alerts and upside potential described in 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond Starwood Property Trust?
If you stop at Starwood Property Trust, you risk missing other income, value, and quality opportunities that could better match your goals and risk tolerance.
- Target potential bargains by reviewing companies that screen as high quality yet priced below their estimated worth through 33 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on businesses with healthier finances and robust fundamentals using the list of solid balance sheet and fundamentals (25 results).
- Hunt for underfollowed opportunities that pair sound fundamentals with lower market attention through the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com