
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Bristow Group (VTOL)'s Government Services COO Appointment Means For Shareholders
- Bristow Group has appointed Paul Armstrong as incoming Chief Operating Officer, Government Services, following Alan Corbett’s planned retirement, with a phased transition running into March 2027.
- Armstrong’s background in complex international aviation and defense operations positions Bristow Group to address execution, regulatory and customer demands across key government contracts.
- This development highlights how Bristow Group's investment narrative may intersect with Armstrong's government services leadership appointment and the sector's execution requirements.
Scan how Bristow Group's leadership-focused story compares with other government and infrastructure plays by reviewing a curated set of 32 resilient stocks with low risk scores.
Bristow Group Investment Narrative Recap
Bristow Group attracts shareholders who buy into a relatively simple idea. You are backing a helicopter operator that depends on long term government and offshore contracts, with the potential for gradually improving profitability as supply chain friction eases and aircraft transitions settle down. The short term swing factor remains execution on existing government work, where delays and penalties have already pressured margins.
The Armstrong appointment looks more like continuity than a sharp catalyst. Corbett staying through March 2027 gives the Government Services arm time to manage complex contract ramps without a leadership vacuum. If supply chain problems or transition costs worsen instead, that remains a key risk that could blunt the wider earnings story.
The acquisition of Berry Aviation is one of the clearest reference points for this leadership news. Bristow Group is leaning harder into government and cargo flying, with Berry adding more than 20 aircraft and a primarily government services revenue base. That acquisition increases exposure to regulated, contract backed work where Armstrong’s background is directly relevant.
For you as an investor, the key question is how this heavier government mix will affect margins and free cash flow that analysts currently build into their models. Integration risk around Berry, along with ongoing aircraft availability issues, can still interrupt that path. Execution by the new Government Services COO team will be watched closely against those catalysts.
Bristow Group's narrative projects US$2.0b revenue and US$241.1 million earnings by 2029. This rests on analysts' assumption of 7.9% yearly revenue growth and an earnings increase of about US$136.9 million from US$104.2 million today.
Discover why Bristow Group's fair value indicates a 66% potential upside to its current price that may not last much longer.
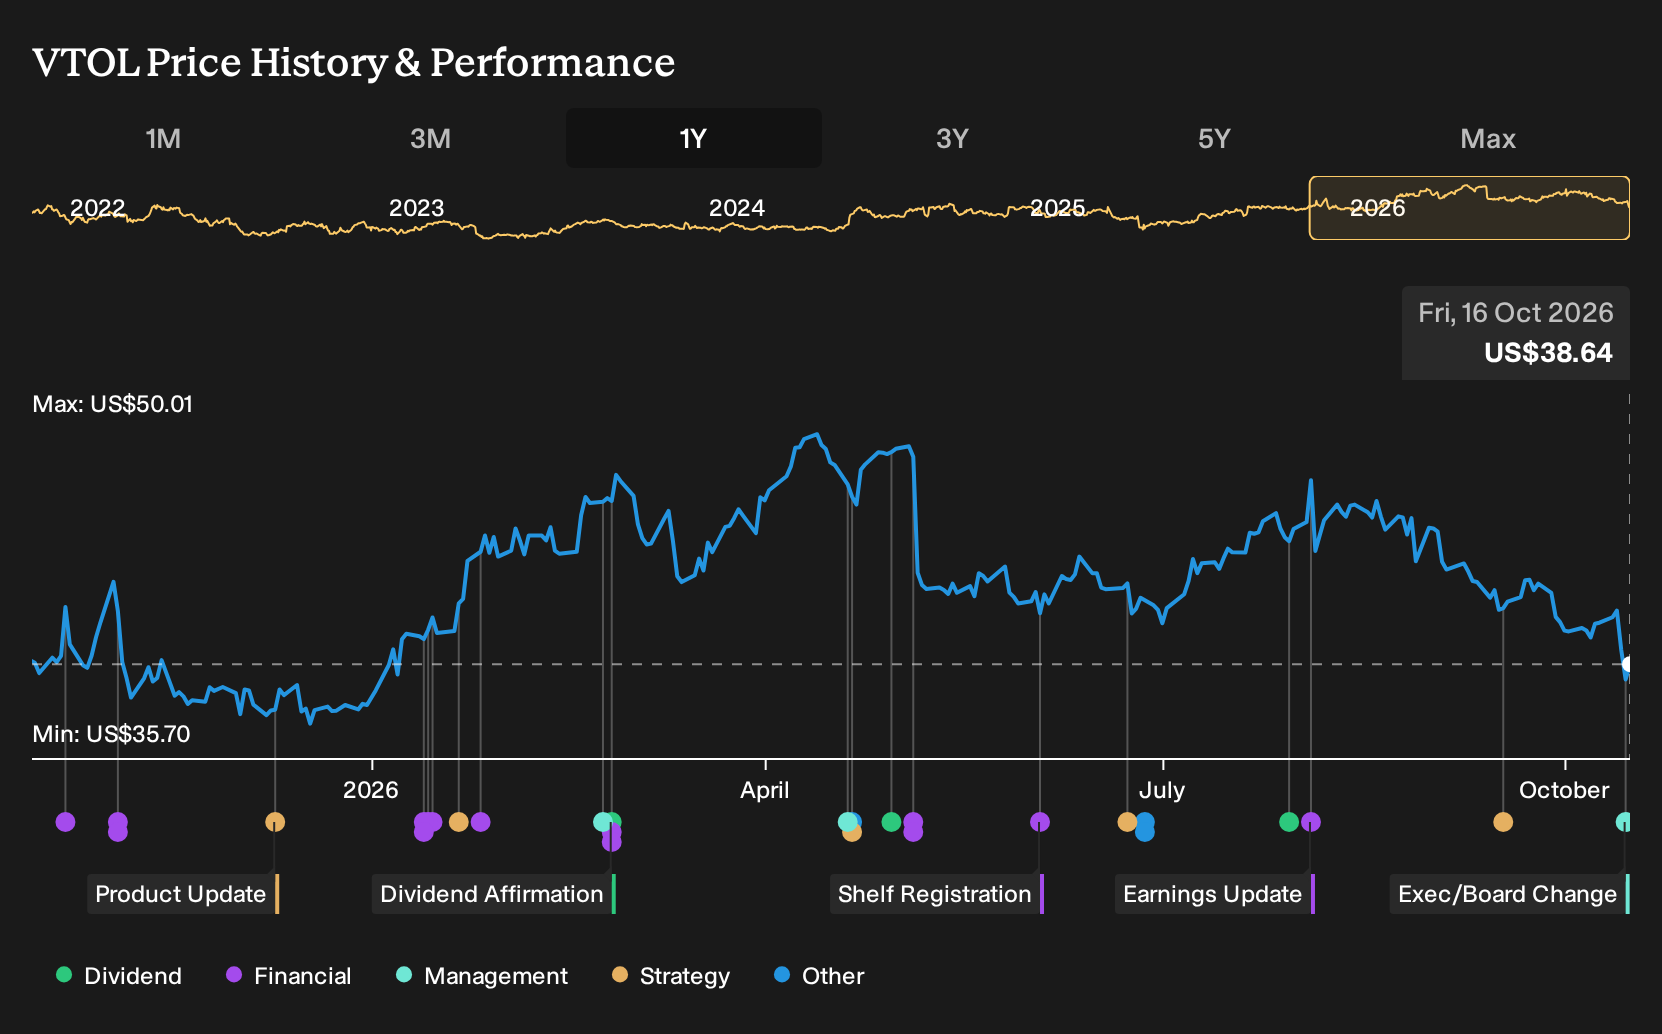
Exploring Other Perspectives
One alternative angle focuses on aircraft availability risk. The most cautious analysts were already baking in tighter offshore supply and softer mature markets, with forecasts of about US$1.9b revenue and US$207.1 million earnings by 2029. Those views came before Bristow Group announced Armstrong, so opinions may evolve from here.
Explore 2 other Bristow Group fair value estimates, including one that suggests it could be worth just $64.33!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Bristow Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bristow Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bristow Group's overall financial health at a glance.
Looking for more Bristow Group style ideas?
If the Bristow Group story has sharpened your thinking, it can help to line it up against other opportunities that share similar risk, return and balance sheet profiles. The Simply Wall St Screener lets you filter for traits that match how you like to invest, rather than forcing every thesis into the same mold.
- Prioritize capital preservation and steadier price swings by scanning a curated set of 32 resilient stocks with low risk scores that aim to keep business risk contained.
- Focus on quality at a reasonable price by reviewing a hand picked group of 20 high quality undiscovered gems that combine solid fundamentals with less analyst attention.
- Target income focused opportunities by checking a universe of 8 dividend fortresses where cash payouts sit at 5%+ and are supported by underlying operations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com