
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should LNG Carrier Buy Require Action From Golar LNG Stock Investors?
- Golar LNG has acquired the 2013-built LNG carrier Grace Dahlia from NYK Line, planning to convert the 177,427 cbm vessel into its fourth FLNG unit, with larger storage than FLNG Esperanza and targeted redelivery in 2029 from the CIMC Raffles yard in Yantai, China.
- The enlarged storage capacity for FLNG #4 gives Golar LNG more flexibility to offer different offloading patterns to customers. This aligns with how the business is trying to turn its long term FLNG contract pipeline into a broader liquefaction and storage service platform.
- We will look at how Golar LNG's investment narrative is affected by locking in Grace Dahlia as feedstock for FLNG #4 capacity.
Scan Golar LNG's move into larger floating liquefaction and compare it with other gas and energy infrastructure plays using our curated 41 power grid technology and infrastructure stocks
Golar LNG Investment Narrative Recap
To own Golar LNG, you need to believe the FLNG service model can turn its long charter book and future capacity into steady, contract backed cash flow. Grace Dahlia fits that story by underpinning FLNG #4, but it does not change that the near term focus remains execution and uptime on existing units and projects already under construction.
The key short term swing factor is still whether current FLNG assets hit schedule and performance targets, because that underpins confidence in the whole growth pipeline. The biggest risk remains funding this build out with higher cost debt while free cash flow is still uneven, which could pressure margins and leave less room for shareholder returns.
The Grace Dahlia move ties directly into the earlier ordering of FLNG #4 with an all in budget of about US$2.45b and targeted delivery in 2029. By locking in a 2013 built carrier for conversion, Golar LNG is filling in execution detail on that plan rather than rewriting it. This should help you judge timing and scale more clearly.
That FLNG #4 order sits alongside roughly US$17b of contracted EBITDA backlog and three long term FLNG contracts running through 2045. The operational question becomes whether management can finance and build this extra capacity without stretching the balance sheet. If funding again leans on higher coupon borrowing and free cash flow stays tight, leverage and project risk stay front of mind.
Golar LNG's current analyst story centres on revenue of US$802.8 million and earnings of US$501.2 million by 2029, based on a projected 15.3% yearly revenue growth rate and an earnings increase of about 3.1x from US$163.7 million today.
Uncover how Golar LNG's fair value indicates a 47% potential upside to its current price before that discount can close.
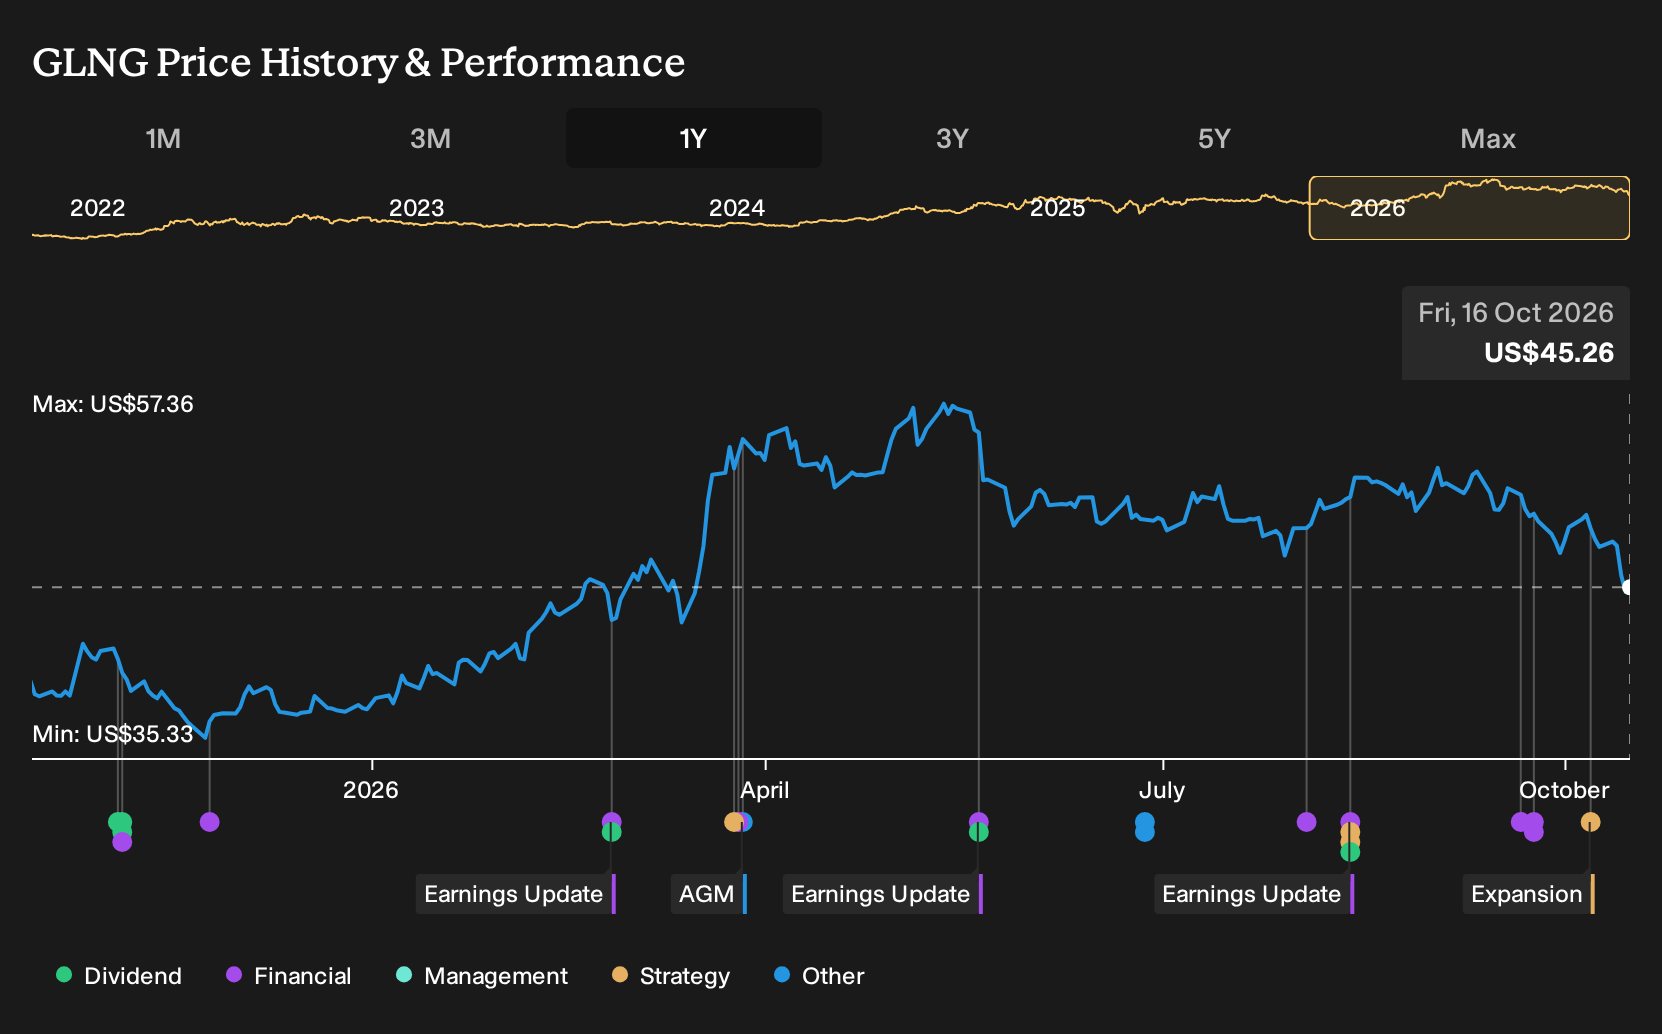
Exploring Other Perspectives
One alternate story around Golar LNG zooms in on FLNG #4 charter risk. The most cautious analysts were only forecasting about US$931.5 million of 2029 revenue and US$313.9 million in earnings before this news. That view assumes thinner margins and tougher contracting. It shows how sharply opinions can differ, so explore several angles before deciding how this update might reshape your thesis.
Explore another Golar LNG fair value estimate, including one that suggests it could be worth just $66.31!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Golar LNG research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Golar LNG. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Golar LNG's overall financial health at a glance.
Looking for more investment ideas beyond Golar LNG?
Once you have a view on Golar LNG, it can help to put that thesis alongside other opportunities so you can see how risk, balance sheet strength, and income potential compare across your watchlist.
- For investors who want income to do more of the heavy lifting, start with companies that have payouts above 5% and a focus on resilience by scanning our 8 dividend fortresses.
- If capital preservation comes first and you want businesses with sturdier finances and lower risk scores, narrow your search using the 32 resilient stocks with low risk scores.
- When you are hunting for under followed opportunities with strong fundamentals, use the 20 high quality undiscovered gems to surface candidates that might not yet be widely owned.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com