
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Expanded Nvidia Partnership Require Action From Volvo Shares Investors?
- Volvo Car AB expanded its long running alliance with Nvidia, agreeing to integrate Nvidia's Hyperion sensor platform, Alpamayo automated driving software and Halos safety layer into future electric, plug in hybrid and gas models over the coming years.
- This move pushes Volvo Car AB deeper into building its own full tech stack for automated driving. It could reshape cost structures, supply decisions and the pace at which it brings higher automation features to urban and highway driving.
- Next, the focus turns to how this deeper Nvidia tech stack integration might influence Volvo Car AB's broader investment narrative.
What Is Volvo Car AB (publ.)'s Investment Narrative?
To own Volvo Car AB (publ.), you need to believe this is a safety and software heavy automaker that can turn modest top line growth into healthier profitability over time. The Nvidia expansion matters because it ties Volvo Car AB (publ.) more tightly to a defined automated driving roadmap across its electric and combustion models. That speaks directly to execution, since management now leans on a single, integrated platform rather than stitching together multiple suppliers.
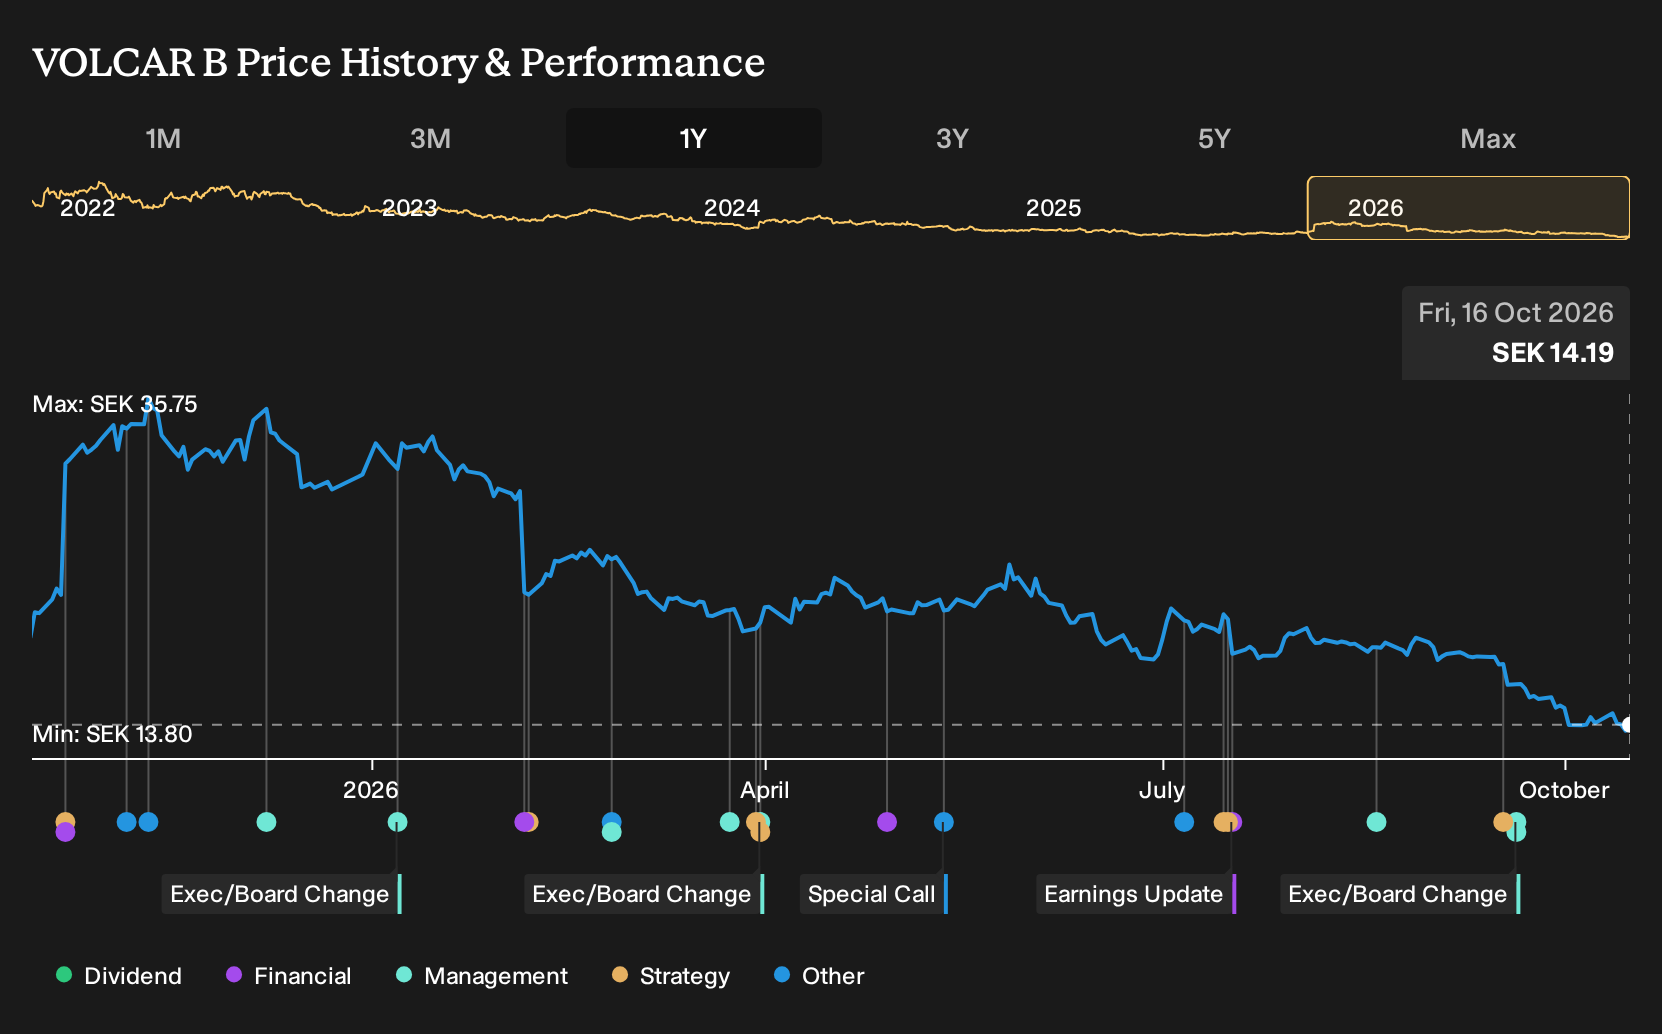
In the short term, the key swing factors still look very operational. The group is dealing with a share price that has fallen 57% year to date and around 67% over three years, even as revenue of SEK 331,112m and net income of SEK 9,348m support a P/E of 4.5x and earnings described as high quality. Earnings recently grew very sharply and are forecast to expand at 11.7% a year, with revenue projected to rise 4% annually. That Nvidia deal connects to this by potentially raising capital intensity and software development spend before automated driving features scale, while the stock’s weak 1 year and 3 year returns keep investor patience quite tested.
That said, the story around Volvo Car AB (publ.) becomes far less comfortable once you weigh one structural funding issue that...
There's only one way to know the right time to buy, sell or hold Volvo Car AB (publ.). Head to Simply Wall St's company report for the latest analysis of Volvo Car AB (publ.)'s Fair Value.
Exploring Other Perspectives
Lowest analysts worried that Volvo Car AB (publ.) would stay stuck in a capital hungry loop. They were pencilling in fairly flat revenue near SEK 337.9b and earnings of SEK 8.1b by 2029, below today’s SEK 9.3b. Those views pre date the Nvidia expansion, so some of those narratives may evolve.
Explore 3 other Volvo Car AB (publ.) fair value estimates, including one that suggests it could be worth just SEK15.79.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Volvo Car AB (publ.) research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Volvo Car AB (publ.). The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Volvo Car AB (publ.)'s overall financial health at a glance.
Looking For More Investment Ideas Beyond Volvo Car AB (publ.)?
Once you have a view on Volvo Car AB (publ.), it can help to set it beside a few very different opportunities so you can judge risk, quality and income potential on the same screen.
- If you want higher potential upside and are comfortable with volatility, scan a focused list of 131 elite penny stocks with strong financials that already have stronger financials than many peers.
- For investors who care most about quality at a reasonable entry point, run a comparison using our 191 high quality undervalued stocks that combine solid fundamentals with more modest pricing.
- If stable cash returns matter to your plan, filter for income ideas with the 214 dividend fortresses to see which payouts might better fit your portfolio goals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com