
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Results And Trading Update Just Shift IntegraFin Holdings' (LSE:IHP) Investment Narrative?
- IntegraFin Holdings recently released its results and a trading update, providing fresh detail on platform activity, costs and operational performance.
- The update gives investors a clearer read on how IntegraFin’s business model is handling current expense pressures and client behaviour on its platform.
- We will look at how IntegraFin Holdings' investment narrative is shaped by the latest trading update on operational and platform trends.
Spot fresh angles on financial platforms like IntegraFin Holdings by reviewing our hand picked list of solid balance sheet and fundamentals (9 results) that may be handling cost pressure and client flows differently.
IntegraFin Holdings Investment Narrative Recap
To own IntegraFin Holdings, you need to be comfortable backing a fee based investment platform that leans heavily on proprietary technology, adviser relationships and steady funds under direction. The immediate swing factor after the recent results and trading update is how client behaviour and gross outflows evolve, since those flows underpin revenue and help absorb higher operating costs.
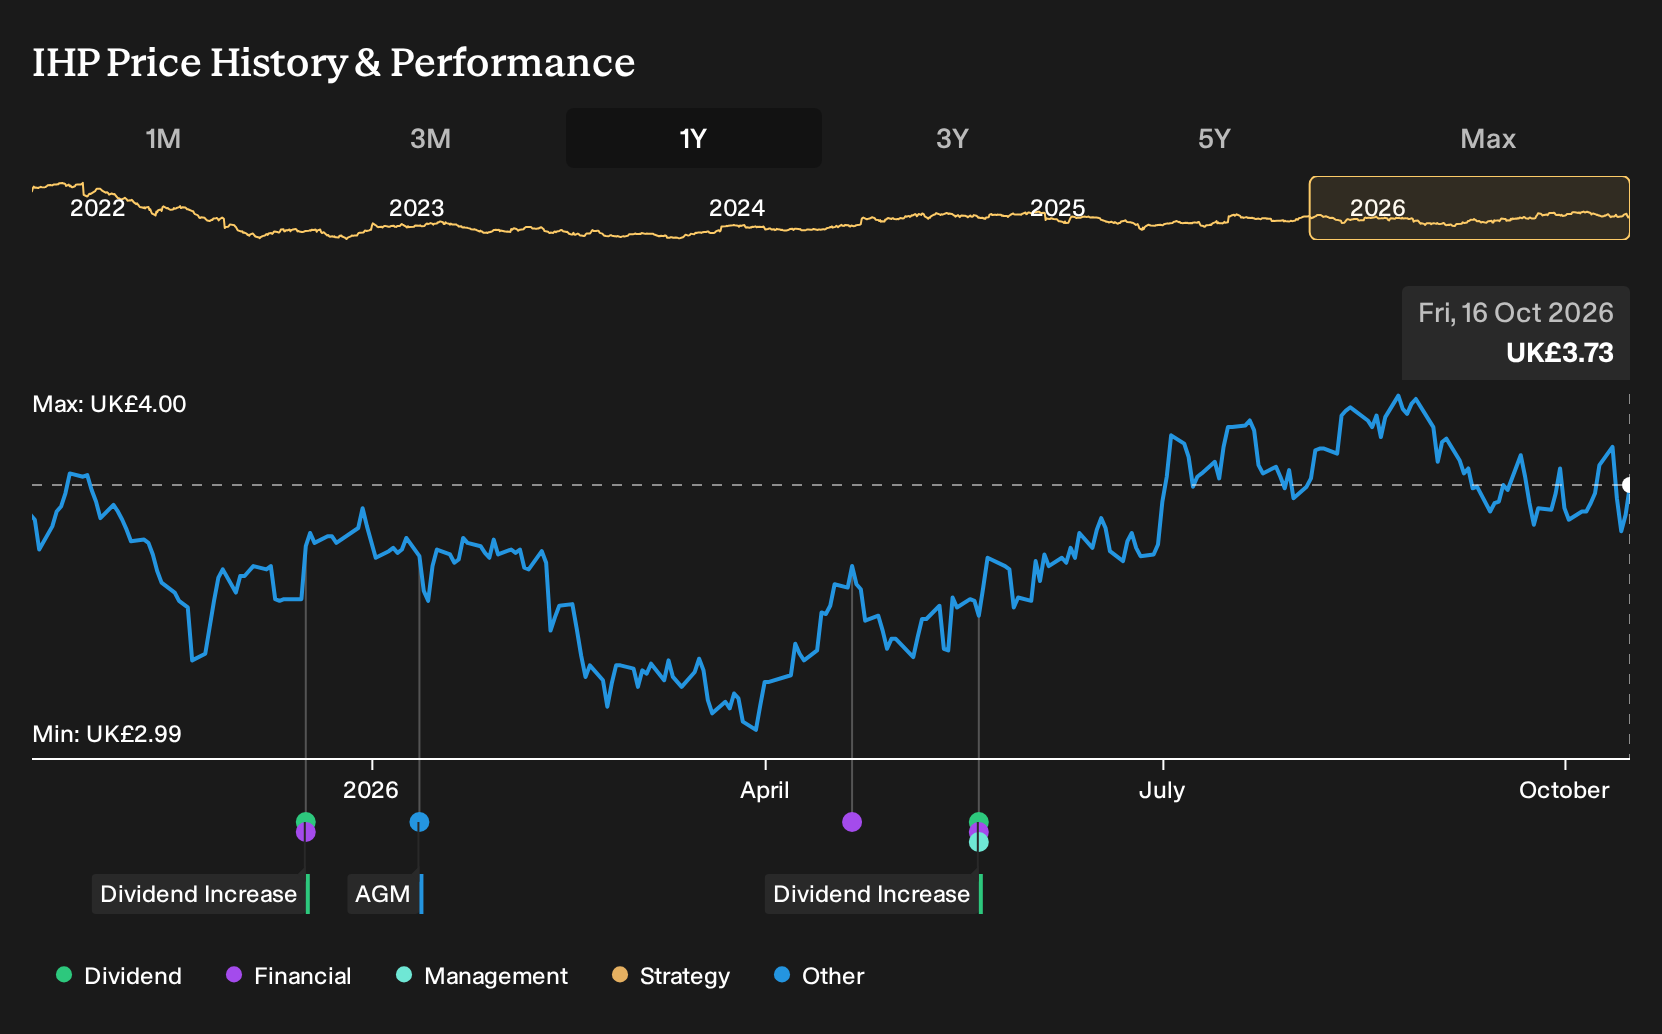
The biggest near term risk still sits in the combination of planned FY 2025 price cuts and rising administrative expenses, including headcount and back office investment. The share price fall signals the market is focused on these pressures. If platform activity and inflows hold up, the impact of the news appears more sentiment driven than structural.
With no fresh announcements beyond the latest results and trading update, that disclosure becomes the key reference point for you. It ties together platform flows, planned price reductions of about £3 million a year from FY 2025 and the 9% projected increase in administrative expenses, which are central to the current debate on IntegraFin Holdings.
The update matters because it gives you live evidence against the core catalysts. Adviser and client growth, digital upgrades such as straight through processing and API integration, and the focus on intergenerational wealth planning all rely on IntegraFin continuing to invest in its platform while protecting margins. Your judgement hinges on how well that balance is being managed after the share price reaction.
IntegraFin Holdings Forecasts and Valuation Anchors
IntegraFin Holdings' current analyst narrative ties the recent trading update to a specific set of long term expectations. Consensus modelling points to revenue growth of 9.5% a year over the next three years, profit margins rising from 38.1% to 43.2%, and earnings of £93.7 million by 2029 compared with £63.1 million today. That implies an earnings increase of about £30.6 million across the forecast window. On these assumptions, analysts are working with 2029 revenue of £217.1 million and applying a P/E multiple of 19.9x to reach a target price of £4.48, against a current share price of £3.67 and a sector P/E of 11.6x.
IntegraFin Holdings' narrative projects £217.1 million revenue and £93.7 million earnings by 2029. This requires 9.5% yearly revenue growth and an earnings increase of about £30.6 million from £63.1 million today.
Uncover why IntegraFin Holdings' fair value indicates a 20% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternative view on IntegraFin Holdings leans hard into the cost saving story. The most optimistic analysts were assuming revenue of about £235.4 million and earnings near £101.4 million by 2029, with a 12.5% annual revenue growth rate, before this latest trading update. After the share price fall, those expectations may shift, so consider them as one of several viewpoints to test, not a script to follow.
Explore another IntegraFin Holdings fair value estimate, including one that suggests as much as 20% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your IntegraFin Holdings research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for IntegraFin Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IntegraFin Holdings' overall financial health at a glance.
Looking For More Ideas Beyond IntegraFin Holdings?
Once you have a view on IntegraFin Holdings, it can help to compare that thesis with other businesses that share similar qualities or offer very different risk and income profiles. The Simply Wall St Screener lets you scan the market quickly so you can test ideas against real numbers instead of headlines.
- If you want potential value combined with balance sheet strength, consider starting with a 7 high quality undervalued stocks that pair solid finances with market skepticism.
- For steadier income and cash return potential, you could review a curated 2 dividend fortresses that meet higher yield and consistency criteria.
- If resilience is your priority, focus on a 4 resilient stocks with low risk scores that screen for businesses with lower overall risk scores and sturdier fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com