
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Oil And Gas Stocks Screening Well As Energy Prices And Inflation Reignite}
Energy prices are back in the spotlight as inflation creeps higher, central banks talk tougher, and geopolitical shocks ripple through oil and gas markets. That mix is reshaping where money flows, creating fresh openings for some large-cap producers and refiners while leaving others exposed to new risks. This article walks through 3 globally significant oil and gas stocks that screens suggest are positively exposed to the latest news shock.
The three highlighted stocks are just a sample set, and the full screen surfaced 29 more large-cap producers and refiners with equally compelling narratives that are not covered below. To identify your own highest-conviction ideas, head straight into the Large-cap global oil & gas producers and refiners screener to filter and analyze this broader group of oil and gas heavyweights.
Ovintiv (OVV)
Ovintiv sits near the center of this large cap oil and gas screen because it is a pure upstream play on North American crude and natural gas prices, giving you direct exposure to the same energy shock that is driving this entire theme.
Ovintiv is a large North American exploration and production business focused on oil and natural gas in the Permian, Anadarko and Montney plays, with about US$6.0b from USA Operations, US$3.6b from Canadian Operations and a market value near US$19.1b.
While Ovintiv points to its deep Permian and Montney inventory and low entry costs as a foundation for long-term drilling activity, the recent 1.2b after tax ceiling test impairment signals that parts of the portfolio may not economically support the booked reserves. This could weigh on future proved reserve additions and ultimately on revenue and earnings quality.
What happens if a single assumption about how efficiently that drilling inventory converts into cash flow starts to move in the wrong direction?
If that efficiency question is front of mind, read the full narrative for Ovintiv to see how Ovintiv’s impairment, drilling inventory and capital choices could be decoupling beneath the surface.
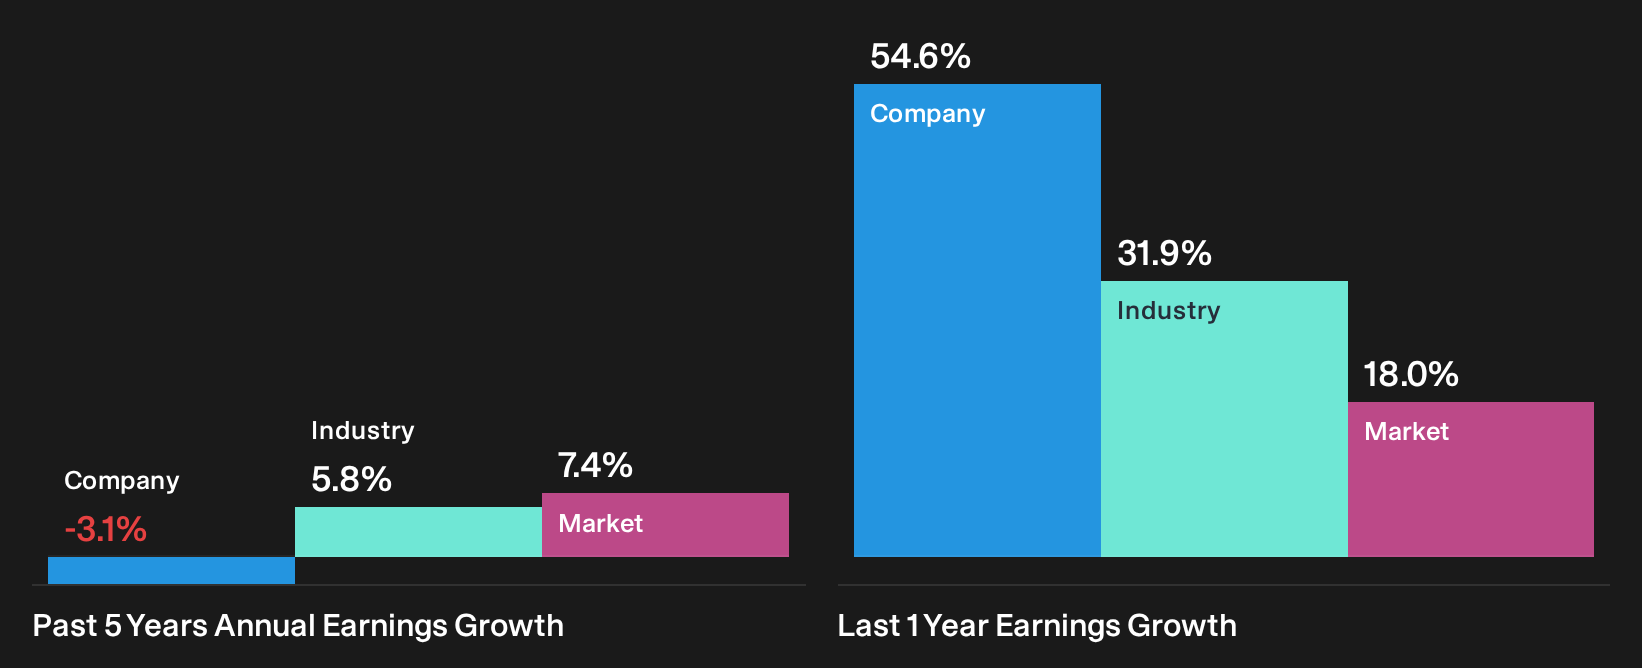
Matador Resources (MTDR)
Matador Resources is one of the clearest plays in this large cap producers and refiners screen, with a US$6.7b market value and a business built around U.S. oil and gas output in the Delaware Basin, supported by about US$3.5b from exploration and production and roughly US$750 million from midstream services.
For investors hunting direct leverage to higher oil and gas prices, Matador Resources offers a pure U.S. production story with its own midstream backbone. This is exactly the kind of profile this large cap energy screen is designed to surface.
Although the integrated midstream platform is expected to contribute about US$360 million of EBITDA in 2026, the expanded US$1.1 billion San Mateo credit facility with an accordion feature up to US$1.35 billion introduces additional capital that must earn adequate returns, which could compress net margins if throughput or fee terms are weaker than anticipated.
What investors really need to watch is how one quiet shift in the balance between volumes, pricing and capital costs shapes those future margins.
That margin mix is exactly where the story gets interesting, and the full narrative for Matador Resources explains how Matador Resources could turn that capital load into accelerating cash generation potential.

Excelerate Energy (EE)
Excelerate Energy plugs directly into the screener theme through its liquefied natural gas infrastructure, giving investors exposure to regasification capacity and global gas flows rather than upstream drilling risk. The group generated about US$1.5b from gas utility activity and has a roughly US$3.7b market value.
Excelerate Energy controls 12 of a little over 50 FSRUs globally at a time when about 200 million tonnes per annum of new LNG supply is expected by the end of the decade. This can support higher utilization and pricing for regas assets and feed into EBITDA growth if tight capacity persists.
What that means for Excelerate Energy’s future earnings will hinge on how one pressure point in its LNG contract mix actually plays out.
That contract pressure point is exactly where the Excelerate Energy story can accelerate or stall, and the full narrative for Excelerate Energy unpacks how that LNG mix could reshape its long term opportunity set.
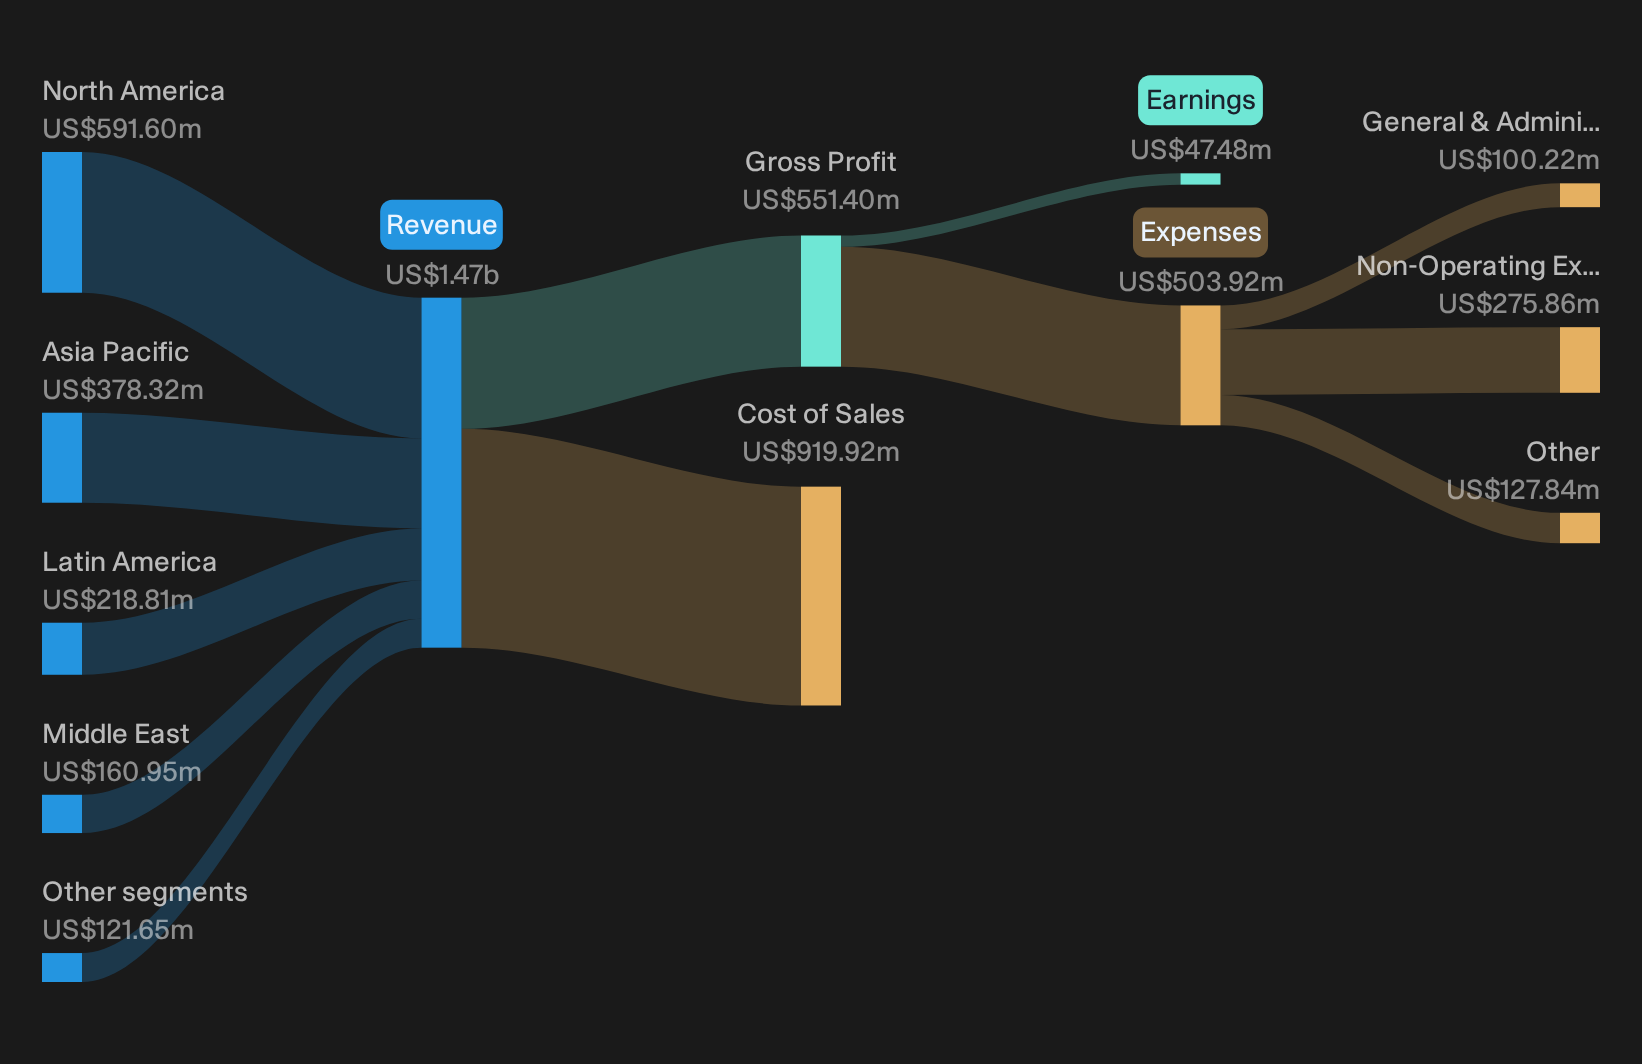
Seeking Alternatives Before The Crowd?
Fresh opportunities can move quickly as momentum builds, prices move sharply, and weaker ideas lose ground. Scan these under the radar lists before the edge fades and consider acting promptly.
- Target cash rich operators that combine staying power with potential upside by reviewing the list of solid balance sheet and fundamentals (25 results) while the market focus is elsewhere.
- Explore the evolving energy build out by assessing essential infrastructure suppliers with the 41 power grid technology and infrastructure stocks before capital conditions change.
- Identify early leaders in intelligent automation by working through the curated 92 robotics and automation stocks while adoption is developing and expectations remain contained.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com