
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Does Earnings Beat Change The Bull Case For Royal Caribbean Cruises Stock (RCL)?
- Royal Caribbean Cruises recently reported earnings of $4.21 per share compared with expectations of $3.97 and outlined an expanded 2028 to 2029 Europe program with year round Mediterranean and Northern Europe itineraries.
- The focus on higher utilization of existing ships and deeper spending from repeat guests suggests management is working to squeeze more value from the current fleet rather than leaning only on new capacity.
- We will examine how Royal Caribbean Cruises' investment narrative is influenced by its Europe program expansion and recent earnings performance.
Royal Caribbean Cruises Investment Narrative Recap
To own Royal Caribbean Cruises, you need to be comfortable with a consumer travel story that leans on full ships and strong onboard spending rather than just more vessels. The recent earnings beat at $4.21 per share against $3.97 expectations signals that operations are currently running ahead of what the market had penciled in, which supports near term confidence in demand and cost control.
The key short term swing factor is whether booking and pricing hold up into the next few quarters as macro worries and softer Mediterranean commentary linger. The biggest operational risk remains any hit to demand or fuel costs that squeezes yields and margins, and the latest updates do not remove that concern.
The expanded 2028 to 2029 Europe program is the clearest operational announcement tying into this update, because it leans into higher utilization of Royal Caribbean Cruises' existing fleet and deeper spending from loyal guests. Year round Mediterranean and Northern Europe itineraries give the group more levers on itinerary mix and onboard revenue in a region where some research already flags softer bookings.
Early access for Crown & Anchor Society members also matters for catalysts, since it brings forward data on pricing, occupancy and guest spending that can influence future guidance and capacity decisions. That booking and pricing insight, combined with a record of earnings surprises and a positive Earnings ESP, keeps execution on these itineraries central to how the next results are received.
Royal Caribbean Cruises Analyst Assumptions and Valuation Setup
Analyst models around Royal Caribbean Cruises are built on revenue expansion of 9.1% a year over the next three years and a move in profit margins from 23.5% today to 26.2% by 2029. Earnings projections call for profit of US$6.4b, or US$24.37 per share, by 2029 compared with current earnings of US$4.4b, with the most optimistic forecasts stretching to US$7.1b. That shift implies an earnings increase of about US$2.0b against today’s base, alongside an expected annual 1.93% reduction in share count and a P/E multiple of 18.1x on those 2029 profits versus 15.9x at present.
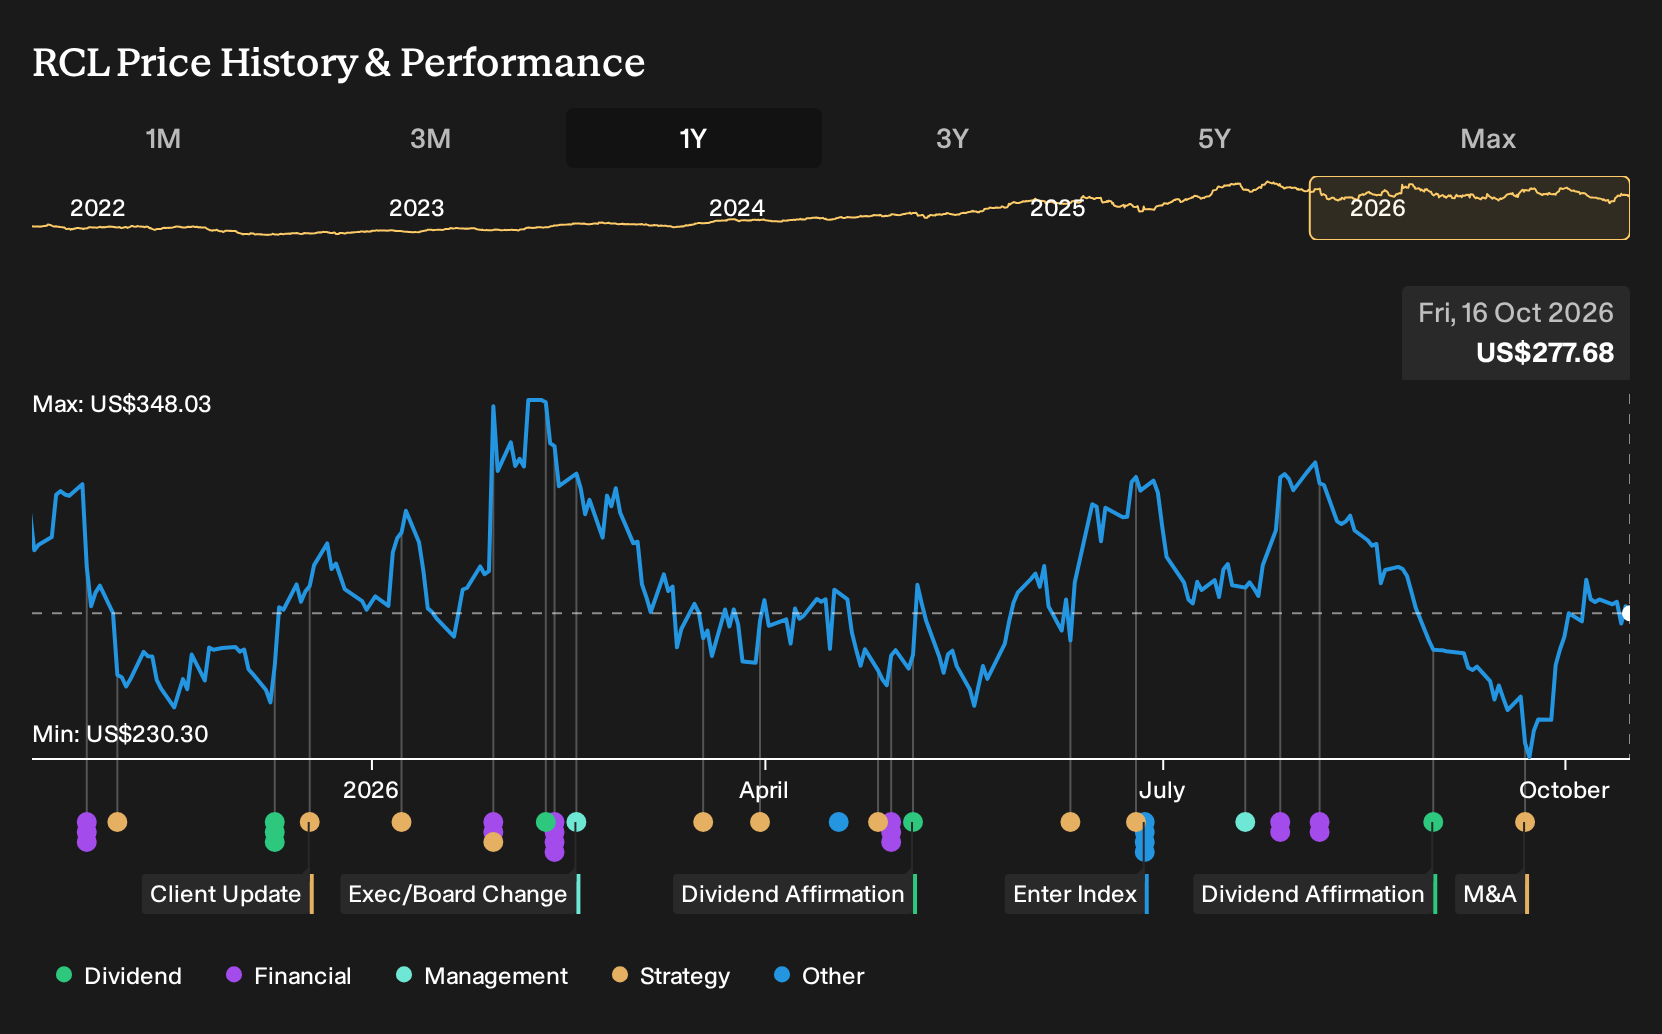
On the valuation side, the analyst framework points to Royal Caribbean Cruises generating US$24.3b in revenue and US$6.4b in earnings in 2029. These figures are then discounted back at roughly 9.2% to support a consensus target price of US$350.44. Price objectives span from US$262.00 to US$425.00, so sentiment is far from uniform even with that shared 2029 anchor. With the stock around US$260.67, the average target sits 25.6% higher. This highlights how much weight these long dated Europe itineraries, fleet utilization gains and onboard spending assumptions carry in the current investment story.
Royal Caribbean Cruises is effectively being framed as a business where future value is tied to steady revenue growth, thicker margins and disciplined capital decisions rather than a simple bet on more ships. The discount rate of about 9.2% reflects the risk that fuel costs, Mediterranean demand softness or broader consumer pullbacks disrupt those forecasts, particularly given the reliance on discretionary travel budgets. This is why the 2028 to 2029 Europe program, early booking trends from Crown & Anchor Society members and any update to yield guidance matter so much for how investors interpret these forward looking earnings paths.
Royal Caribbean Cruises' analyst narrative points to forecast revenue of US$24.3b and expected earnings of US$6.4b by 2029, based on revenue growth of 9.1% a year and an earnings increase of roughly US$2.0b from current earnings of US$4.4b.
Uncover why Royal Caribbean Cruises' fair value indicates a 26% potential upside to its current price before that gap closes.
Exploring Other Perspectives
One alternate Royal Caribbean Cruises story focuses on yield pressure rather than fuel or macro risks. The lowest analysts were penciling in about US$23.6b of 2029 revenue and US$6.2b of earnings before this Europe update, alongside a 14.6x P/E. That is a much more cautious setup. Use these gaps as a prompt to compare several viewpoints and decide which assumptions you find more convincing as new itinerary and earnings data arrive.
Explore 5 other Royal Caribbean Cruises fair value estimates, including one that suggests it could be worth just $275.45.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and judgment.
- A great starting point for your Royal Caribbean Cruises research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Royal Caribbean Cruises. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake. This makes it easier to evaluate Royal Caribbean Cruises' overall financial health at a glance.
Looking for more Royal Caribbean Cruises style investment ideas?
If the Royal Caribbean Cruises story has you thinking about other opportunities tied to travel, discretionary spending or just resilient balance sheets, it can help to cast a wider net using structured stock lists rather than wandering through tickers at random.
- For investors who want potential value combined with quality fundamentals, review a curated group of 33 high quality undervalued stocks that pair cash flow strength with disciplined balance sheets.
- If capital preservation and fewer surprises matter most to you, scan a focused set of 32 resilient stocks with low risk scores that aim to keep risk scores on the lower side.
- Income focused readers can zero in on a targeted universe of 8 dividend fortresses that couple higher yields with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com