
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Nordea Bank Abp (HLSE:NDA FI) Weaker Earnings And Buyback Uncertainty
- Nordea Bank Abp reported third quarter 2026 results with net interest income of €1,799 million and net income of €1,181 million, while confirming a dividend payout policy of 60 to 70% of yearly profit and keeping share buybacks under review.
- The bank paused buybacks as regulators review its internal risk models, which puts more focus on how earnings quality supports dividends and capital strength.
- We will look at how Nordea Bank Abp's investment narrative holds up as weaker operating profit intersects with paused share buybacks.
Compare Nordea Bank Abp's pause on buybacks and firm dividend stance with other resilient capital return stories by scanning our hand-picked 214 dividend fortresses in one place.
Nordea Bank Abp Investment Narrative Recap
To own Nordea Bank Abp you need to be comfortable with a large Nordic lender that is posting solid profitability but slightly softer earnings momentum. Net interest income and net income for both the quarter and the first nine months are marginally lower than a year ago, which keeps the spotlight on cost control, fee income and digital efficiency programs as key near term supports.
The short term swing factor is execution on its existing guidance while managing higher rates that could pressure customer confidence. The biggest current risk sits around regulation and capital, where tighter rules and the ongoing review of internal models could affect how much flexibility Nordea Bank Abp has on distributions beyond its core dividend.
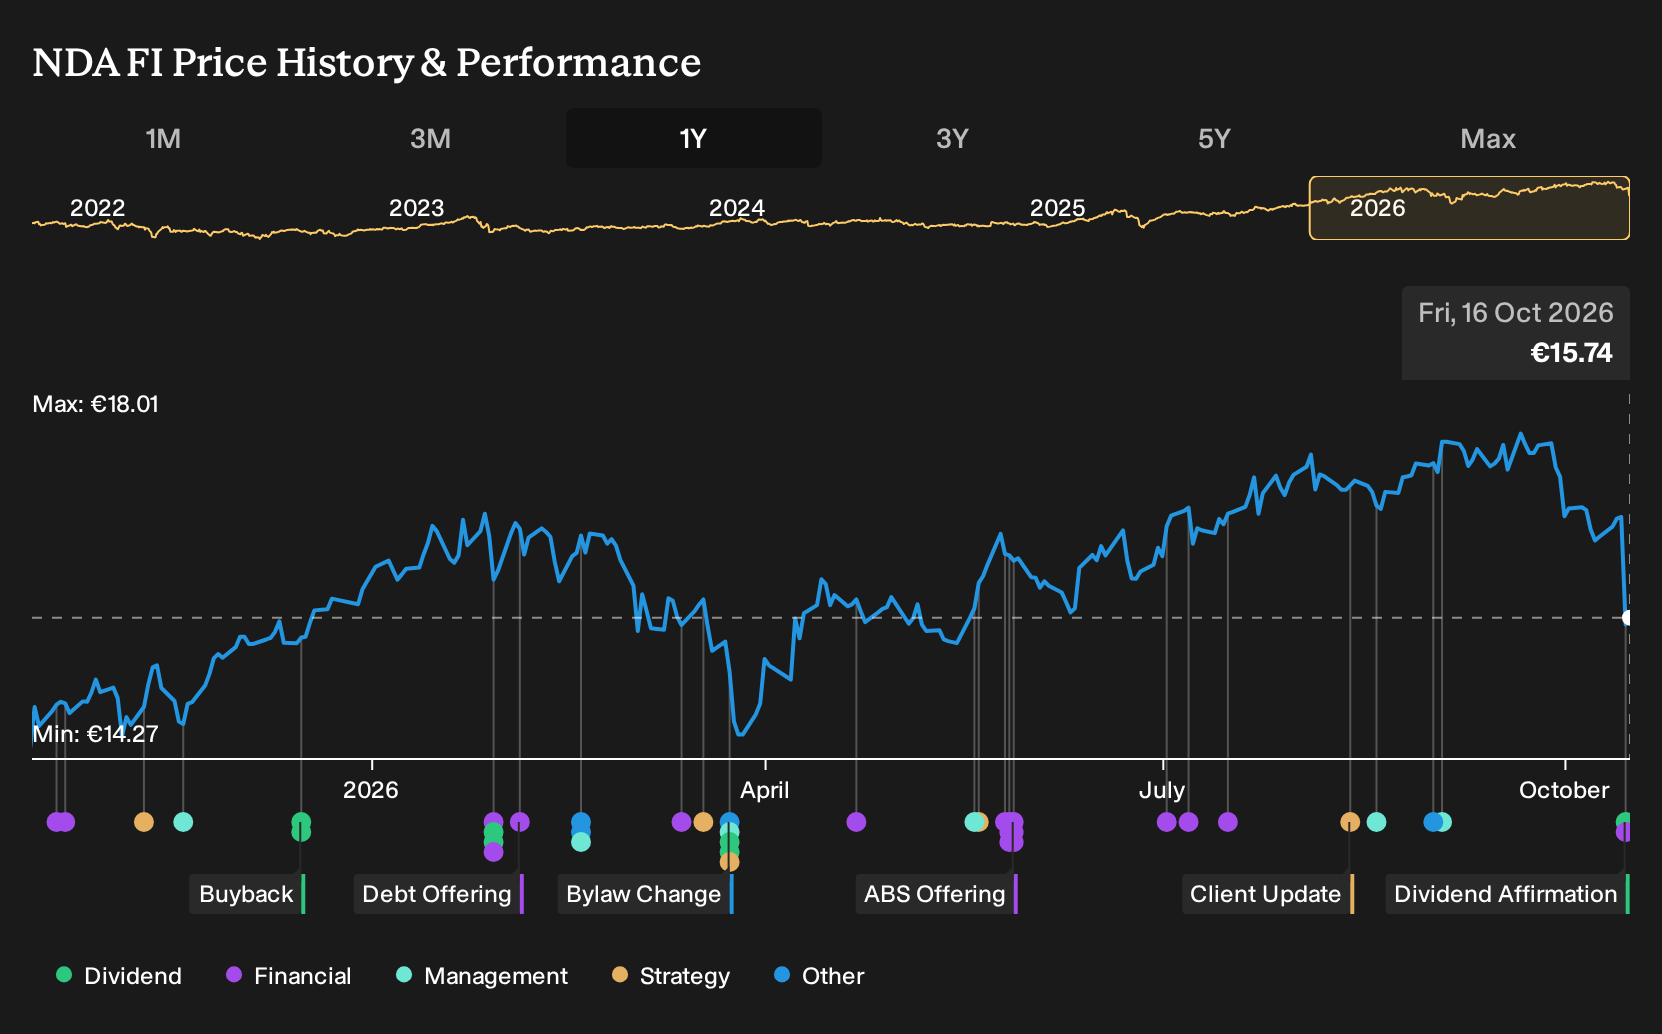
The clearest piece of news to focus on is the reaffirmed dividend policy of paying out 60% to 70% of yearly profit, with buybacks assessed continuously. That commitment frames how management is thinking about excess capital, while operating profit has come in below analyst expectations and the share price has slipped from recent levels.
This payout stance interacts directly with the paused buybacks and the minor flags on dividend cover and bad loan allowance. For you as a shareholder, the practical question is how consistently Nordea Bank Abp can fund that dividend from earnings while keeping capital ratios strong in a tougher regulatory setting and with slightly lower net income so far this year.
Nordea Bank Abp's current earnings are €4.7 billion, with analysts forecasting revenue growth of 4.6% per year and consensus earnings of €5.4 billion by 2029. That profile implies a €0.7 billion increase in earnings from today to the 2029 estimate, with revenues projected to reach €13.3 billion in the same forecast year.
Uncover why Nordea Bank Abp's fair value indicates a 19% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span a tight €18.66 to €29.98 range for Nordea Bank Abp, giving you very different anchors to compare with current pricing. Those views sit alongside fresh pressure from weaker operating profit, paused buybacks, and regulatory uncertainty, which could reshape how you weigh these community valuations.
Explore 2 other Nordea Bank Abp fair value estimates, including one that suggests it could be worth just €18.66.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Nordea Bank Abp research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Nordea Bank Abp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nordea Bank Abp's overall financial health at a glance.
Looking for more investment ideas beyond Nordea Bank Abp?
Once you have a view on Nordea Bank Abp, it often helps to set that against a wider watchlist so you can judge risk, quality, and income options side by side.
- For investors who want income with resilience, scan a curated group of companies built around strong and recurring payouts through the 214 dividend fortresses.
- If your priority is robust finances and cleaner balance sheets, focus on businesses screened for solid capital positions and fundamentals using the list of solid balance sheet and fundamentals (203 results).
- When you want to broaden horizons beyond well covered stocks, search for under followed quality businesses with strong underlying metrics through the 618 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com