
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Zegona Communications (LSE:ZEG) Draws Fresh Value Attention As Low P S Stands Out
Fresh attention is hitting Zegona Communications (LSE:ZEG) after new analysis flagged its P/S ratio of 1.3x as lower than both the wider telecom industry and a 2.0x peer average.
Recent trading has been lively for Zegona Communications, with a 1-day share price return of 1.51% and a 90-day share price gain of 15.17% feeding into year to date share price growth of 29.33%. The 1-year total shareholder return of 54.87% and very large 3-year and 5-year total shareholder returns suggest momentum has been strong over both shorter and longer horizons, even after a 30-day share price dip of 2.68% that keeps the current £17.46 level and modest 1-month pullback aligned with a P/S ratio still below peers.
Scan for other telecoms showing similar momentum with a compressed P/S setup by running the 7 high quality undervalued stocks alongside Zegona Communications on your watchlist.
That mix of strong multi year returns and a below peer P/S ratio splits opinion on Zegona Communications. Do the numbers still argue for undervaluation, or has the recent run already priced in the good news?
Price to Sales of 1.3x: Is it justified?
On the numbers available, Zegona Communications looks inexpensive versus its own fair P/S estimate and its closer peers, even if it screens less cheap against the wider European telecom group.
The preferred yardstick here is the P/S ratio. It sits at 1.3x, which compares the current £17.46 share price to the £3,627.54m of revenue the business produced. For a telecom operator where headline earnings are still in loss territory, investors often lean on P/S because it connects the market value of the stock directly to the top line rather than profit, which can be distorted by financing costs, integration charges or accounting choices.
Against similar companies, that 1.3x reading is not aggressive. The P/S level is described as good value versus the peer average of 2.0x, suggesting the market is assigning a lower price tag per pound of sales than it does for comparable telecom operators. The internal fair P/S estimate of 2.7x is also materially higher than where Zegona Communications trades today. This gap points to a level the valuation could drift toward if sentiment on the shares and the sector aligns with that model.
Industry context tells a different story. Compared to the broader European telecom space, where the average P/S comes in at 1.1x, Zegona Communications is described as expensive. In other words, investors in this ticker are currently paying more per unit of revenue than they would for the sector in aggregate, even though the stock appears cheap alongside direct peers and versus its own estimated fair ratio.
Explore the SWS fair ratio for Zegona Communications.
Result: Price-to-sales of 1.3x (UNDERVALUED)
Still, the ongoing net loss of €189.41m and reliance on a single Spanish market leave Zegona Communications exposed if competition or pricing pressure intensifies.
Find out about the key risks to this Zegona Communications narrative.
Another View on Zegona Communications: What the DCF Says
The picture shifts when you look at Zegona Communications through the SWS DCF model. On this view, the estimated future cash flow value sits at £42.14 per share, well above the current £17.46 price, which frames the stock as undervalued through this second lens.
If two methods both point to value but use very different inputs, the real question for you is which risks and assumptions you trust more.
Look into how the SWS DCF model arrives at its fair value.
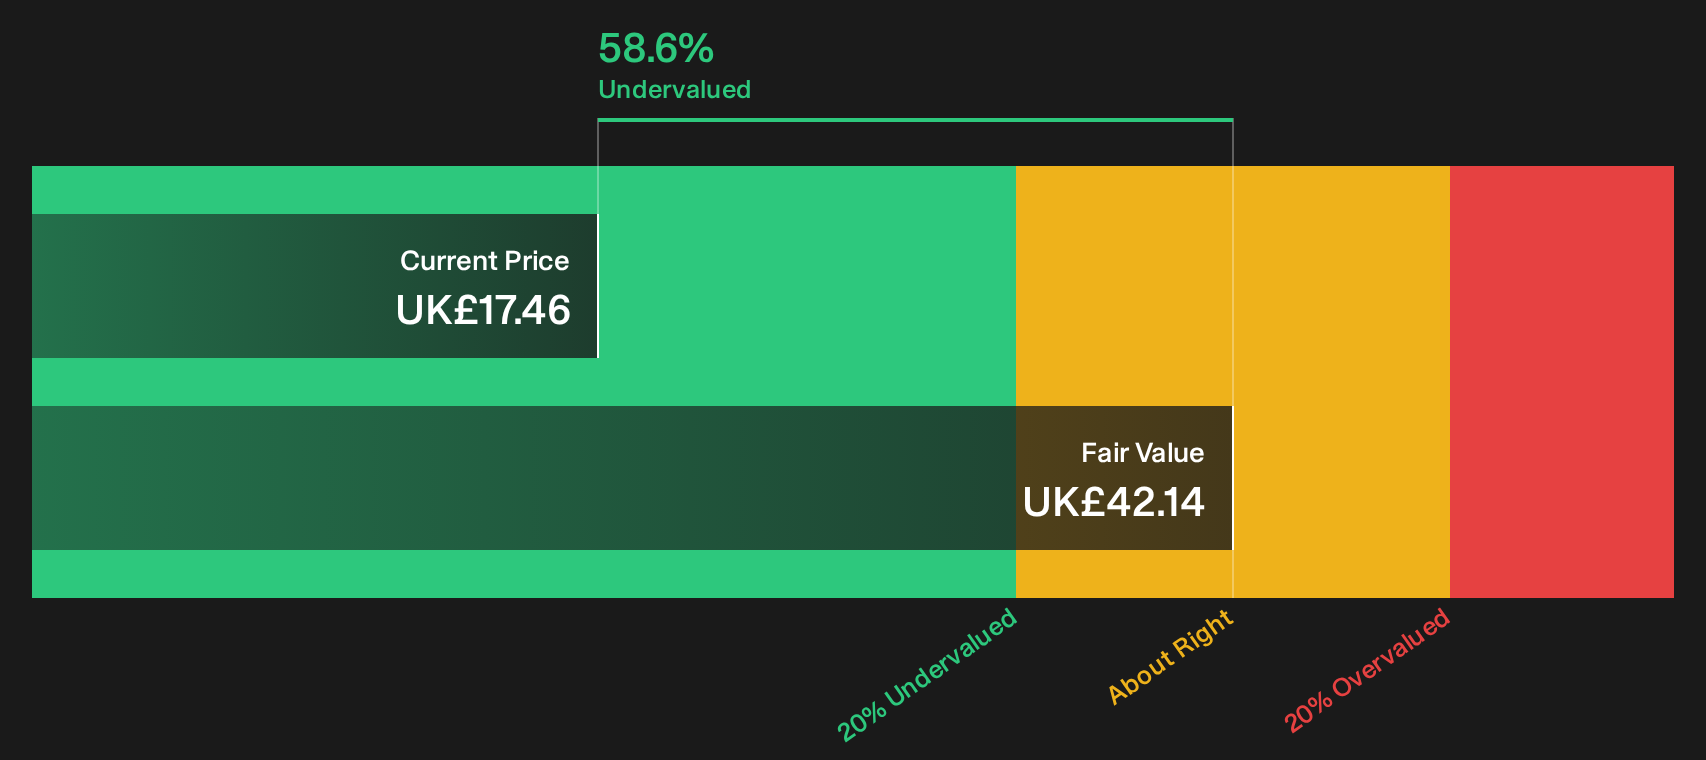
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Zegona Communications for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Zegona Communications often trigger strong opinions, so move quickly, review the underlying figures for yourself, and then weigh both the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Zegona Communications?
Do not stop with Zegona Communications when fresh opportunities could be only a few filters away using the Simply Wall St Screener.
- Target stronger balance sheets by scanning companies in the list of solid balance sheet and fundamentals (9 results) so you are not relying on just one resilient story.
- Hunt for mispriced opportunities by lining up the 7 high quality undervalued stocks and comparing their fundamentals to what you see in Zegona Communications.
- Spot under followed prospects early by running the 5 high quality undiscovered gems before attention and pricing start to catch up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com