
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Perseus Mining Holders Saw Early
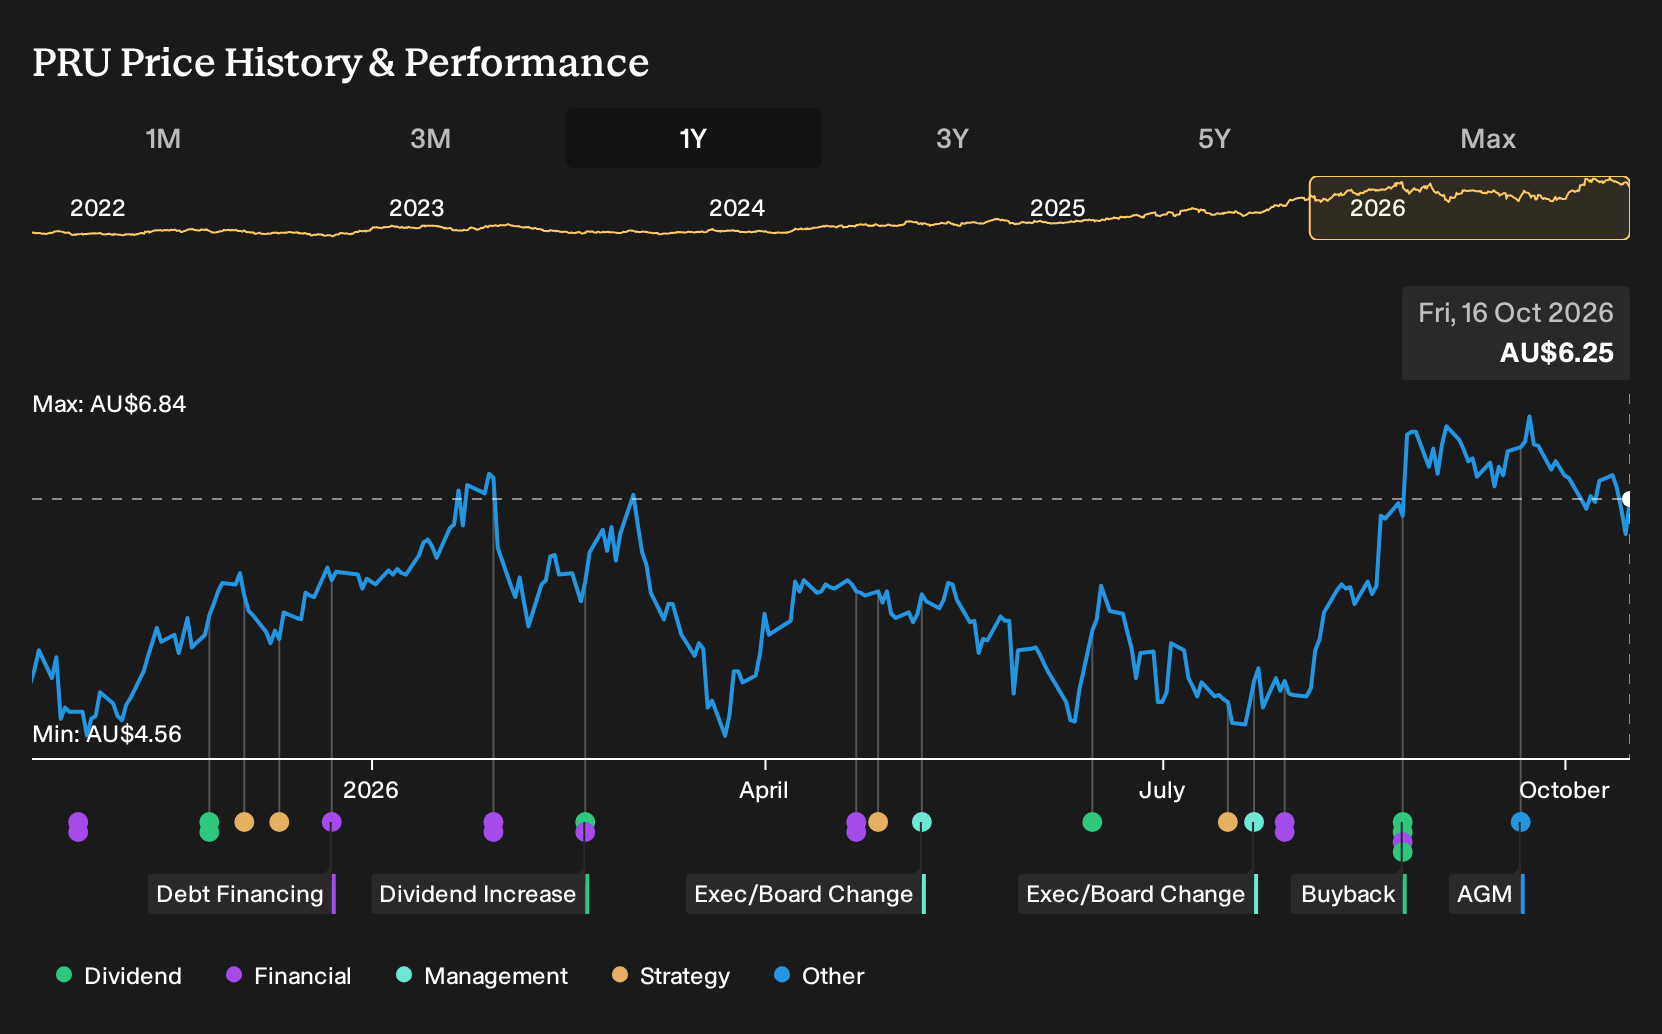
If you had backed Perseus Mining a year ago, the outcome would look very different today from sitting on the sidelines. Holding Perseus Mining over the past year would have returned 23.6%, including dividends. That kind of gain invites a harder question. If you were weighing its West African focus, analyst disagreement, and dependence on gold prices back on 16 October 2025, which of those trade offs would have mattered most to your decision?
The move put Perseus Mining in the middle of this trade. Scan 36 elite gold producer stocks for other companies exposed to it.
The Two Futures Investors Had To Price In
The shares cost A$5.03 at the start of the period, and anyone looking at Perseus Mining then had to decide which future seemed more plausible.
On the optimistic side, the bullish Narrative pinned a Fair Value of A$5.8, a price implied by expectations rather than hard fact, on the stock and leaned on early delivery of Nyanzaga and CMA Underground to support faster revenue growth and higher profit margins.
In the opposing camp, the cautious view saw Fair Value at A$4.26 and treated reliance on elevated gold prices, together with West African political and cost risks, as the core threat to long term profitability.
What The Results Changed For Perseus Mining
Perseus Mining delivered H2 2026 revenue of US$875.447 million and net income of US$264.703 million, both above H2 2025 levels, with net margin edging up from 28.9% to 30.2%. That combination supported the optimistic case that focused on stronger profitability. However, reliance on high gold prices and West African exposure meant the cautious argument on risk remained intact.
The useful takeaway is how much the thesis depended on margin resilience. When you assess another miner, compare any stated cost discipline or pricing power with the reported net margin over time and see whether it actually changes.
What Today's Perseus Mining Price Already Assumes
Perseus Mining now trades at A$6.25, while the selected Narrative’s Fair Value sits below that level based on its own framework rather than any hard rule.
The Narrative leans on heavy sensitivity to gold prices, higher environmental costs, and political risk. A buyer today must assume elevated gold pricing and West African operations stay stable enough to support current expectations.
"Perseus Mining's recent surge in revenue and cash margins is heavily reliant on historically elevated gold prices, leaving future earnings vulnerable to any sustained downturn in the price of gold as global macroeconomic volatility and potential de-dollarization dampen gold's safe-haven appeal, likely resulting in declining top-line revenue and margin compression."
One Narrative disagrees with today's price. → See where this Narrative says Perseus Mining should trade
Looking Beyond Perseus Mining
Perseus Mining keeps you focused on precious metals and political risk. One step away sits a different resource with a very different demand story.
Instead of gold, think crop nutrients. Farmers cannot swap out this mineral, and food costs feel the strain when supplies misfire.
One miner is trying to produce that fertiliser ingredient using adapted drilling methods. The approach aims to cut upfront construction costs and speed up first output.
Modular build outs also change the rhythm of risk. Each phase can refine the process and funding mix.
If that method proves dependable, your watchlist might need space beside Perseus for a very different kind of mine.
One Narrative has already put a figure on it. → Uncover the company trading 25% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com