
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What 1st Source (SRCE)'s Earnings Beat Potential Means For Shareholders
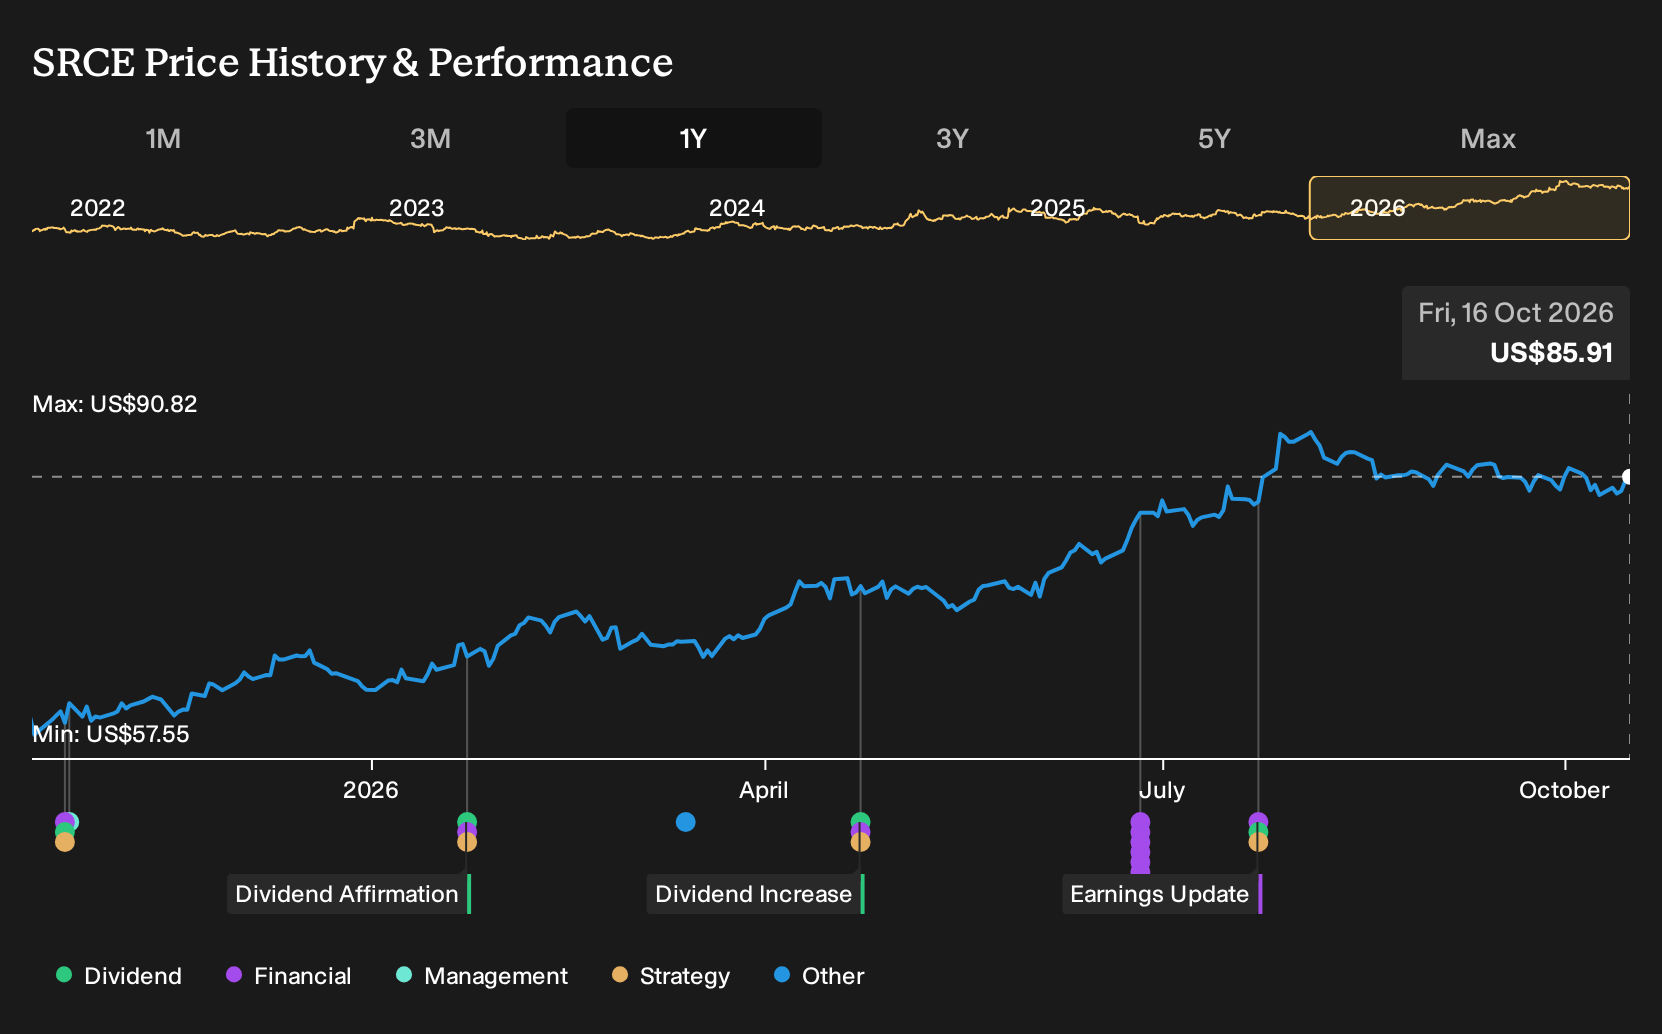
- 1st Source is scheduled to report quarterly results for the period ended September 2026. Analysts expect higher earnings and revenue compared with the same quarter a year earlier, supported by a positive Earnings ESP of 0.55% and a recent track record of beating EPS estimates in three of the past four quarters.
- The key fundamental angle is rising expectations for 1st Source's operating performance, as investors focus on whether the bank can again exceed consensus profit forecasts after several past beats.
- The focus also includes how 1st Source's investment narrative could be influenced by expectations of stronger earnings heading into this report.
What Is 1st Source's Investment Narrative?
To own 1st Source, you need to be comfortable with a fairly traditional banking engine that leans on commercial lending, equipment finance and fee lines like wealth advisory and insurance. The appeal is a mix of steady earnings, high quality profit and a dividend around 2%. Expectations for a higher earnings print this quarter simply sharpen that story, because they keep attention on whether management is still executing cleanly on pricing, credit discipline and operating efficiency rather than chasing headline growth.
The near term swing factors are straightforward. Net interest income resilience, loan demand in core Midwestern markets and credit costs all matter more than a single quarterly beat. Forecasts that call for slower earnings and revenue expansion than the broader US market frame this earnings setup as a test of durability, not of rapid expansion. If the upcoming report lines up with that, the bigger question for 1st Source is whether the current valuation already reflects that balance of consistency and modest growth.
Yet sitting behind that seemingly comfortable profile is one issue that could change how you read those earnings altogether...
There's only one way to know the right time to buy, sell or hold 1st Source. Head to Simply Wall St's company report for the latest analysis of 1st Source's Fair Value.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community span roughly US$89.67 to US$129.47 per share, which leaves a wide gap in how 1st Source is assessed. That spread reflects how differently private investors weigh earnings forecasts and the pending earnings ESP story, so treat it as a prompt to compare several viewpoints before you act.
Explore another 1st Source fair value estimate, including one that suggests it could be worth just $89.67.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your 1st Source research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for 1st Source. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate 1st Source's overall financial health at a glance.
Looking For More Investment Ideas Beyond 1st Source?
Once you have a view on 1st Source, it can help to compare that thesis with other opportunities that share similar qualities or sit at very different points on the risk and income spectrum. The Simply Wall St Screener lets you quickly filter for companies that match what you care about most, whether that is resilience, income or value.
- For investors who want potential growth without ignoring financial strength, scan a 20 high quality undiscovered gems that already show solid fundamentals but attract less attention.
- If capital preservation and steadier profiles matter more to you than headline excitement, narrow your watchlist with a 32 resilient stocks with low risk scores to see which businesses carry lower risk scores.
- Income focused investors who want yield backed by substance can check a 8 dividend fortresses that screens for higher payouts supported by underlying financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com