
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Raised EPS Guidance Change Cencora (COR) Stock Narrative
- Cencora recently raised its fiscal 2026 EPS guidance, reflecting confidence in the earnings contribution from acquisitions such as OneOncology and the pharmaceutical focused model that underpins its distribution and services network.
- The decision to lean further into specialty platforms like OneOncology highlights how Cencora is using higher value services to support earnings quality and capital deployment plans such as sizeable buybacks.
- We will now explore how Cencora's higher fiscal 2026 EPS guidance could reshape the existing investment narrative around specialty growth.
Scan Cencora’s specialty push against a hand-picked 33 high quality undervalued stocks that may also be priced below their cash flow potential.
Cencora Investment Narrative Recap
Cencora asks investors to view specialty drugs and services as the main engine for earnings, even as lower fee generics and biosimilars become a larger part of the mix. The raised fiscal 2026 EPS guidance reinforces that view, since it connects more of the near term narrative to platforms such as OneOncology and other higher margin offerings.
The key short term swing factor is whether those specialty services continue to offset pressure from lower profitability GLP 1 volumes and contract changes, including Walgreens shifting volume. The primary risk is that any slowdown in specialty operating income, combined with these mix headwinds, could limit margin progress despite disciplined execution.
The clearest recent announcement connected to this news is the higher fiscal 2026 EPS guidance, which follows a record of EPS growing faster than revenue and strong ROIC. That update effectively increases the emphasis on the contribution from OneOncology and similar platforms to support earnings quality.
In terms of catalysts, the guidance increase intersects with several ongoing drivers. Cencora is investing in digital tools such as AI based demand forecasting, expanding World Courier and European 3PL, and continuing sizeable buybacks, including the US$1.0b completed in fiscal Q3 2026 and an additional US$2.0b authorized. Taken together, these moves outline how execution in specialty, technology and capital allocation could influence EPS delivery relative to the updated guidance.
Cencora's narrative projects US$393.3b revenue and US$3.4b earnings by 2029. This assumes 5.7% yearly revenue growth and an earnings increase of about US$0.8b from US$2.6b today.
Uncover why Cencora's fair value indicates an 8% potential upside to its current price that could narrow quickly.
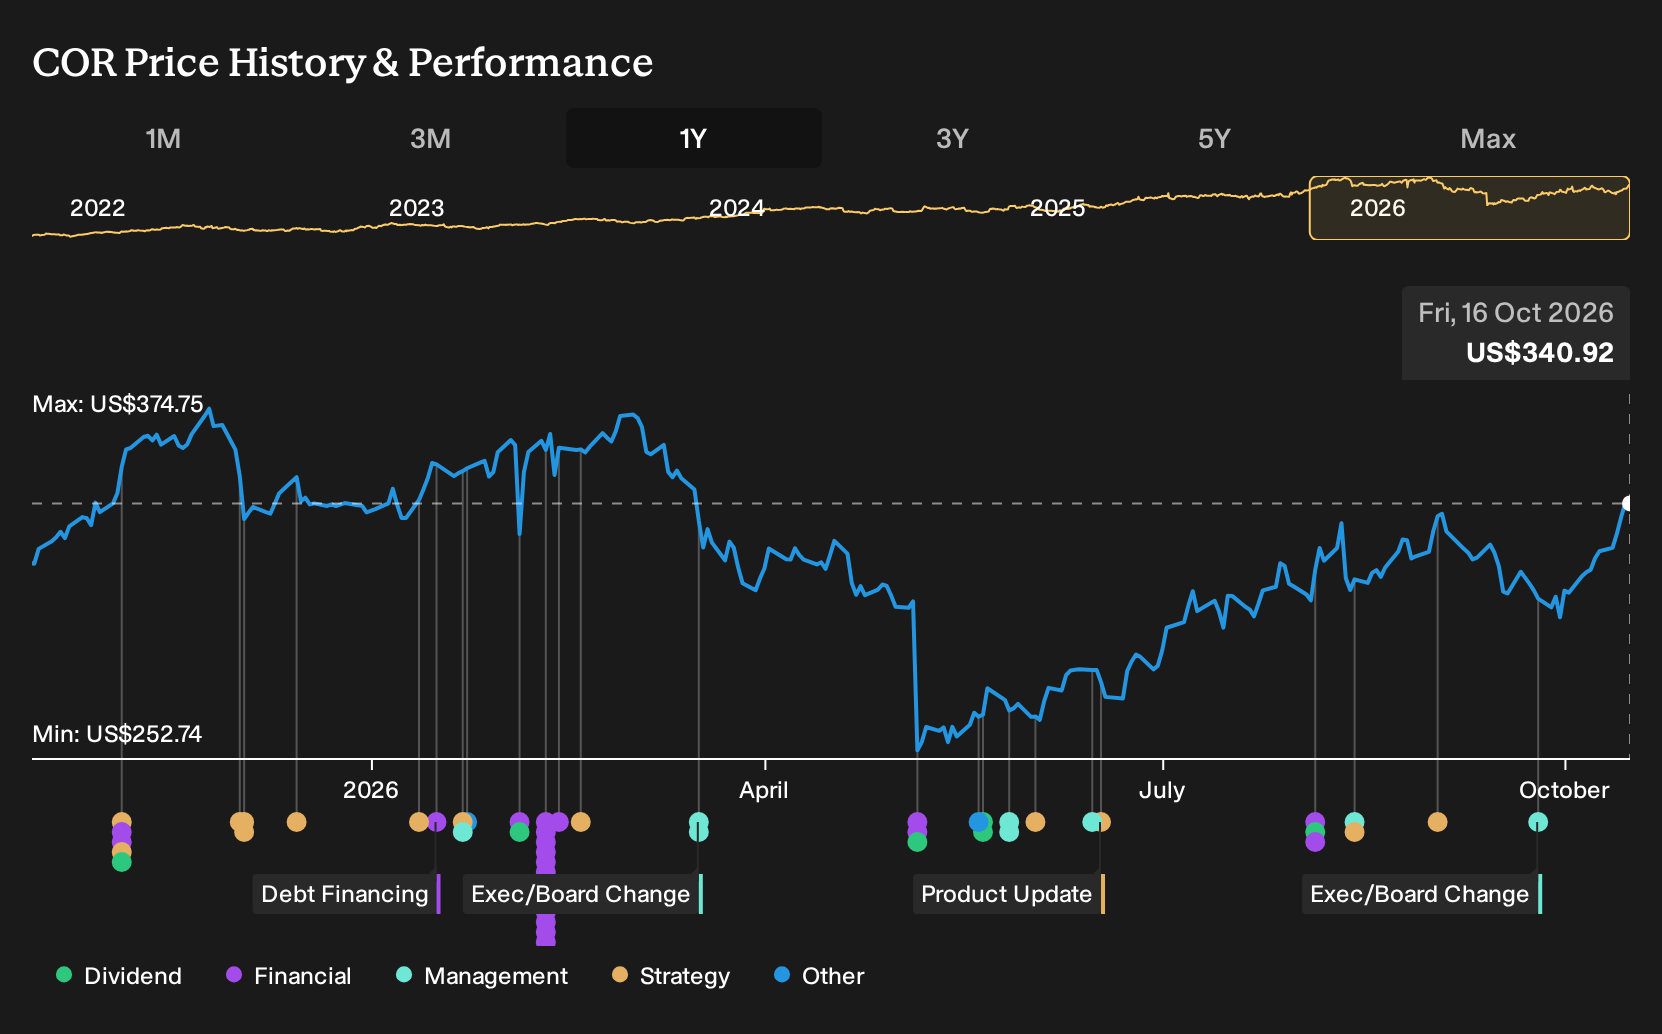
Exploring Other Perspectives
For Cencora, the more cautious story hinges on digital spending risk. The lowest analysts saw AI and automation costs squeezing future payoff, with revenue projections closer to US$372.4b and earnings of about US$3.3b by 2029. That is a cooler view than consensus, and this new guidance could eventually shift those expectations.
Explore 2 other Cencora fair value estimates, including one that suggests it could be worth just $367.67.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cencora research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cencora. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cencora's overall financial health at a glance.
Looking for more investment ideas beyond Cencora?
Once you have a view on Cencora, widen the lens and compare it with other businesses that fit different risk, income, and quality profiles using the Simply Wall St Screener.
- If resilience matters most to you, start with a 32 resilient stocks with low risk scores that score well on stability so you can focus on businesses with steadier profiles.
- If balance sheet strength is your filter, scan a list of solid balance sheet and fundamentals (25 results) to find companies backed by cleaner finances and solid fundamentals.
- If you want potential mispricings on your radar, check a 20 high quality undiscovered gems that may not yet be widely followed but still show strong underlying numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com