
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
UPM-Kymmene Oyj (HLSE:UPM) Starts Leuna Biorefinery Operations, Is The Upside Already Priced In?
UPM-Kymmene Oyj (HLSE:UPM) has brought its Leuna biorefinery in Germany into operation. The €1.37b investment converts wood-based biomass into renewable chemicals for sectors ranging from packaging and clothing to tires.
Investors have already been reacting to these moves. UPM-Kymmene Oyj’s share price is at €25.19, with a 7.42% 90-day share price return and a 20.19% total shareholder return over one year. However, the 3-year total shareholder return is slightly negative, which suggests momentum is relatively recent.
Scan for other bioeconomy players riding similar momentum with a curated list of 618 high quality undiscovered gems that echo UPM-Kymmene Oyj’s push into renewable materials and stronger fundamentals.
UPM-Kymmene Oyj now trades only slightly below analyst targets, while its own intrinsic value estimate implies a much wider gap. Is the Leuna step change already reflected in the price, or not yet?
Most Popular Narrative: 1% Undervalued
On the narrative view, UPM-Kymmene Oyj screens slightly undervalued, with an estimated fair value of about €25.57 against the latest close at €25.19. This shifts the discussion away from simple momentum and toward what really drives cash flow over the next decade.
The main priority is that UPM executes its portfolio simplification and transformation while managing the cash drag from Leuna, working capital build-up and higher leverage, so that earnings from Energy, Fibres South and specialty materials offset headwinds from Communication Papers and biochemicals start-up losses.
See why 33 investors see UPM-Kymmene Oyj as 1% undervalued.
Result: Fair Value of €25.57 (UNDERVALUED)
Still, the thesis can break if Leuna’s capital needs and start up losses weigh longer on cash flow, or if working capital remains tied up and keeps leverage elevated.
Find out about the key risks to this UPM-Kymmene Oyj narrative.
Another View: UPM-Kymmene Oyj Through the P/E Lens
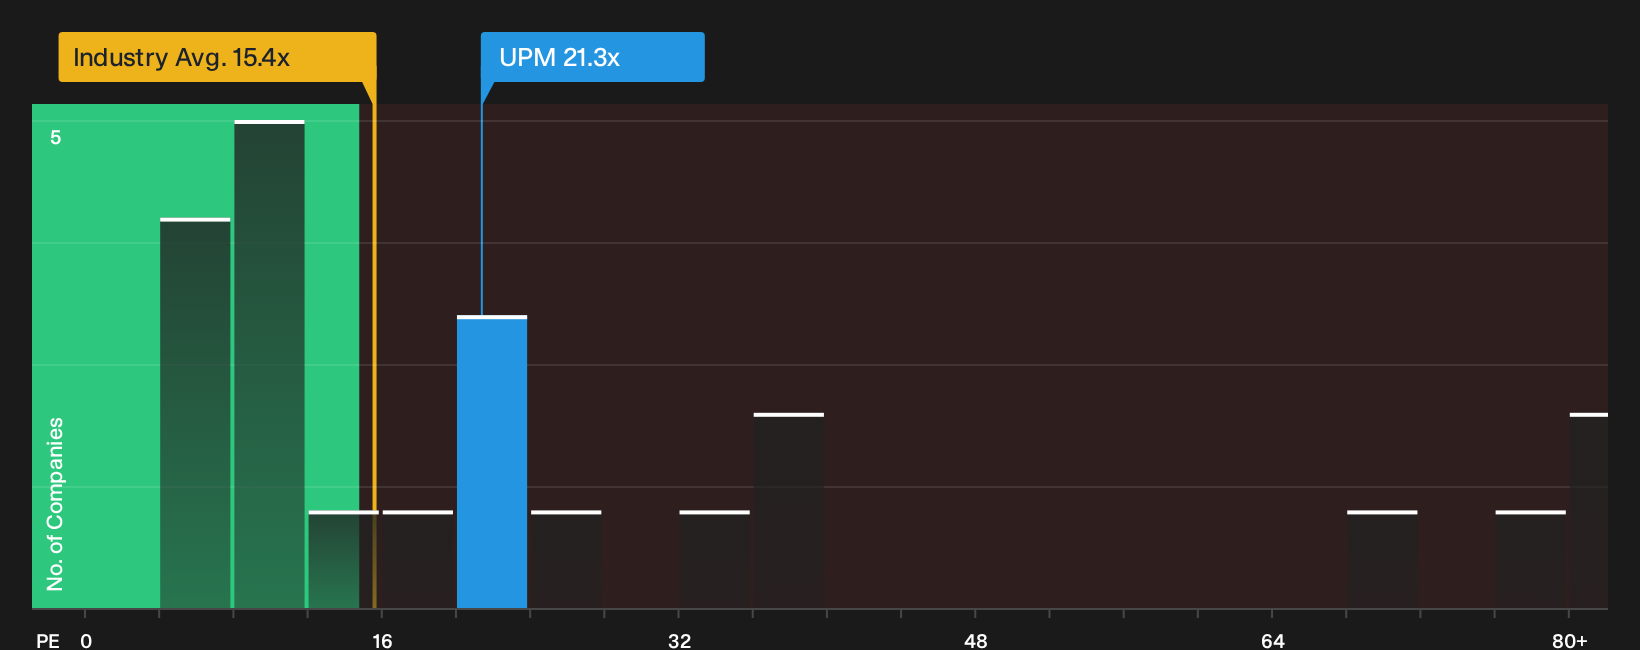
The first narrative frames UPM-Kymmene Oyj as slightly undervalued around €25 per share. On a simple P/E check, the picture looks less generous. The stock trades at 21.3x earnings, compared with 12.8x for peers and 15.4x for the wider forestry group, while the fair ratio sits higher at 24.7x.
A higher multiple than both peers and the industry means you are paying a premium today, even if that fair ratio indicates the market could move closer to 24.7x over time. The question is whether that premium feels like a safety margin for quality or a source of valuation risk if growth expectations cool.
See what the numbers say about this price in the fuller valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With sentiment this mixed around UPM-Kymmene Oyj, it pays to move quickly, review the data yourself, and weigh both sides. Start by walking through the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond UPM-Kymmene Oyj?
If the UPM-Kymmene Oyj story has sharpened your thinking, use that momentum to widen your watchlist and spot fresh opportunities before everyone else.
- Target stronger balance sheets by scanning a list of solid balance sheet and fundamentals (203 results) that can handle tougher conditions without stretching finances.
- Hunt for mispriced quality through a focused 191 high quality undervalued stocks that filters for solid fundamentals at what may be appealing entry prices.
- Prioritise stability with a curated 233 resilient stocks with low risk scores that highlights businesses screened for resilience rather than excitement alone.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com