
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Crédit Agricole (ENXTPA:ACA) Digital Spending And Euro Liquidity
- Crédit Agricole has been highlighted for its heavy spending on digital platforms, AI tools, and new ventures, alongside its large euro-linked deposit base tied to money-market style products.
- The same eurozone liquidity exposure that supports funding and product demand also raises questions about pricing power, funding costs, and pressure on near-term net margins if digital investments take longer to pay off.
- This analysis will examine how Crédit Agricole's investment narrative is influenced by its euro liquidity exposure and intensive digital spending.
Scan other euro-focused banks and financial stocks facing similar liquidity and tech spending questions through our hand-picked list of solid balance sheet and fundamentals (203 results) to benchmark Crédit Agricole's setup.
Crédit Agricole Investment Narrative Recap
To own Crédit Agricole, you need to be comfortable with a simple trade off. The bank is tying its future more tightly to euro liquidity flows and digital infrastructure while carrying a large base of money market style deposits. The near term story is really about whether that funding mix and fee pool stay supportive enough to offset heavier tech spending.
The most important short term swing factor is execution on cost control as digital, AI and new ventures keep expenses elevated. The biggest risk is that euro funding costs rise faster than Crédit Agricole can reprice products or extract efficiencies from its platforms, which would squeeze already pressured net profit margins.
Recent commentary around the accounting shift for the Banco BPM stake over 20% is the clearest disclosed event to watch in this context. Management expects a one off hit of about €220 million to the profit and loss statement, with future earnings from that holding linked directly to Banco BPM's own results.
That change does not alter the euro liquidity and digital investment story. It does, however, add another earnings variable on top of already tight French retail margins and elevated IT budgets. For you as a shareholder, the practical question is how well Crédit Agricole manages Italian sector volatility, M&A integration and tech execution without letting these moving parts erode returns on equity further.
Crédit Agricole's current consensus narrative points to €31.5b revenue and €8.4b earnings by 2029, based on analysts' assumption of 6.6% yearly revenue growth and an earnings increase of about €2.3b from the €6.1b reported today.
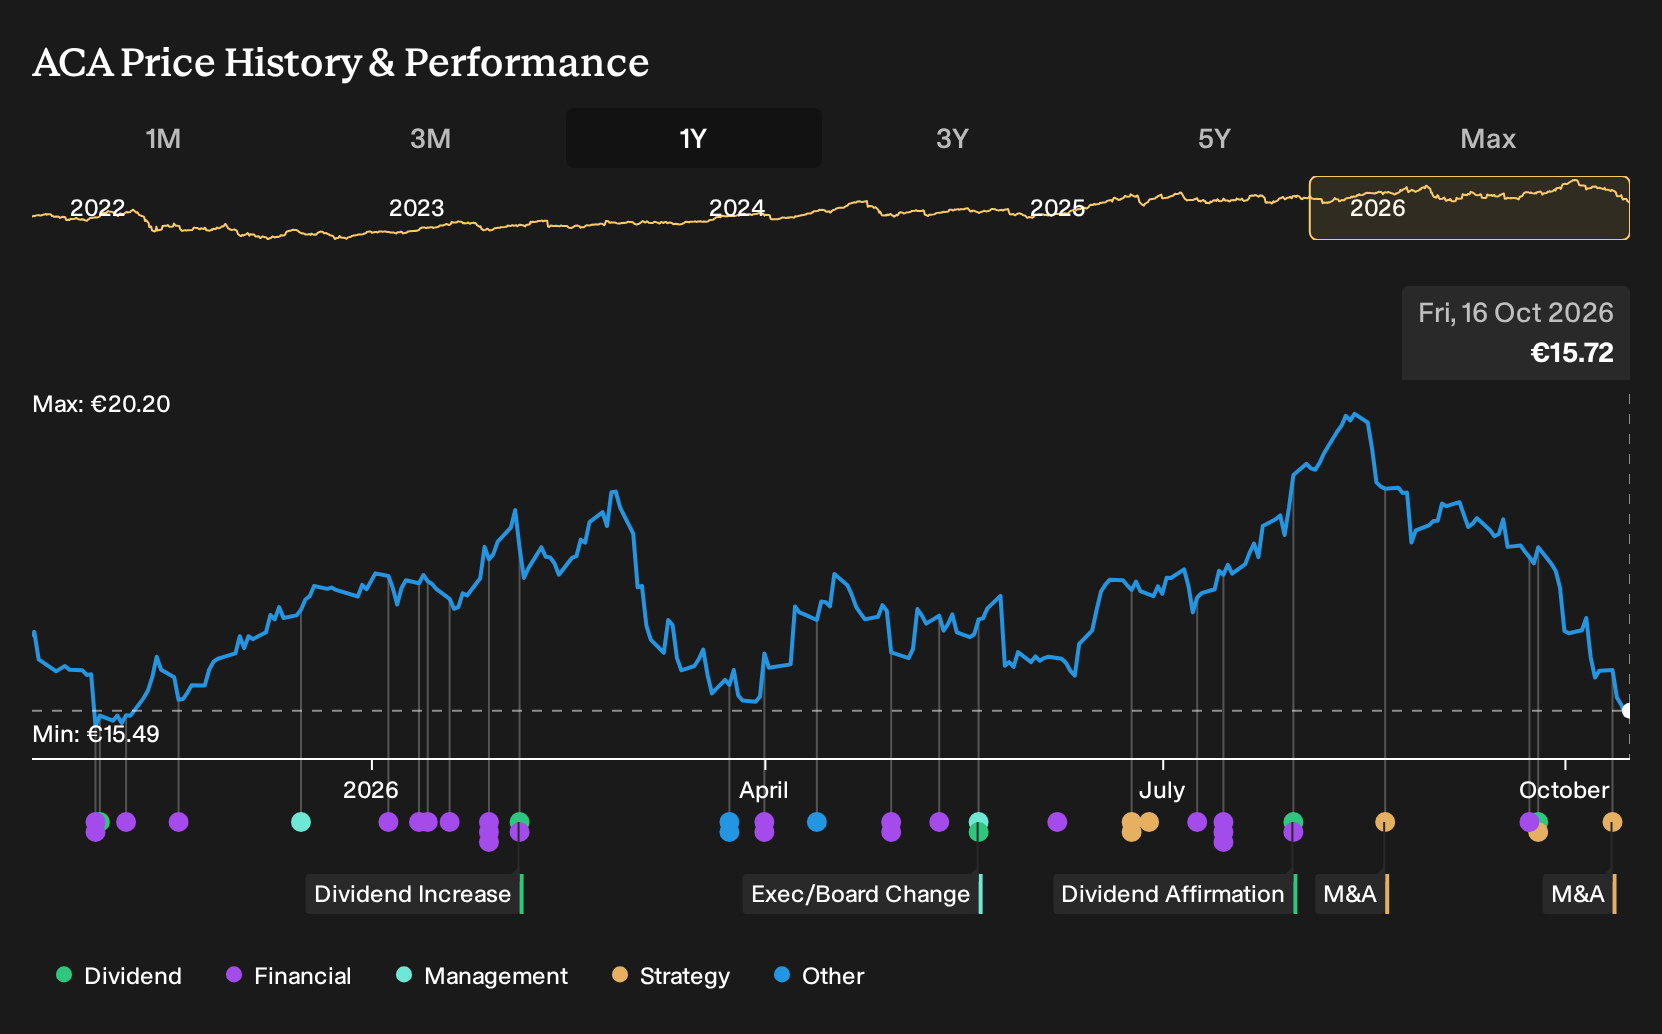
Uncover why Crédit Agricole's fair value indicates a 35% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
For Crédit Agricole, the bearish twist is all about digital spending taking longer to earn its keep. The lowest analysts leaned into that risk, pencilling in revenue of about €30.3b and earnings near €8.0b by 2029, versus higher consensus figures. Those numbers predate the latest news, so views may shift and readers should keep comparing scenarios themselves.
Explore 4 other Crédit Agricole fair value estimates, including one that suggests it could be worth just €18.90!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so go with your instincts.
- A great starting point for your Crédit Agricole research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Crédit Agricole. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Crédit Agricole's overall financial health at a glance.
Looking for more investment ideas beyond Crédit Agricole?
Once you have a working view on Crédit Agricole, it can help to line that thesis up against other potential opportunities so you are not anchored to a single story.
- For investors who care most about resilient balance sheets, start with a curated 233 resilient stocks with low risk scores that filters for companies with lower risk profiles based on financial strength.
- If upside potential matters more to you than size or familiarity, scan a focused 618 high quality undiscovered gems that spotlights lesser known businesses with solid fundamentals.
- When dividends are central to your plan, compare payout opportunities through a targeted 214 dividend fortresses focused on higher yielding companies.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com