
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Granite Construction (GVA) Lifted Guidance And Won New Work, Is It Still Below Fair Value?
Granite Construction (GVA) is back in focus after a mixed quarter that combined a 29.3% year-on-year revenue increase and stronger full-year guidance with an EBITDA miss and an 11.8% share price drop.
Granite Construction’s latest moves, including its roughly $324.8 million share of the Big Creek Tunnel contract and upbeat full-year revenue guidance, sit against a share price that has slipped 11.46% over 90 days and 7.46% year to date. At the same time, the 3-year total shareholder return of about 217% signals strong longer term momentum that recent weakness has only partially unwound.
Spot fresh infrastructure ideas by comparing Granite Construction with our curated 41 power grid technology and infrastructure stocks that is poised to benefit from long-dated public works and grid upgrade spending.For Granite Construction, the recent 11.8% post earnings slide resets the entry point. The real task now is simple. Does the current valuation already reflect that wobble, or does it still leave room to wait for a cheaper shot?
Most Popular Narrative: 36% Undervalued
Granite Construction closed at $109.82 against a narrative fair value of $171.67. This frames the recent pullback as a valuation gap that depends on how durable its contract mix and materials earnings power are.
Active capital allocation that combines continued M&A spending with balance sheet optimization and a focus on double digit operating cash flow margins gives Granite Construction flexibility to add earnings accretive acquisitions while also supporting cash generation and potential per share earnings growth.
See why 4 investors see Granite Construction as 36% undervalued.
Result: Fair Value of $171.67 (UNDERVALUED)
Still, the Granite Construction story can unravel if severe weather and materials cost overruns keep compressing margins, or if real public infrastructure spending slows more than expected.
Find out about the key risks to this Granite Construction narrative.
Another View: What Multiples Say About Granite Construction
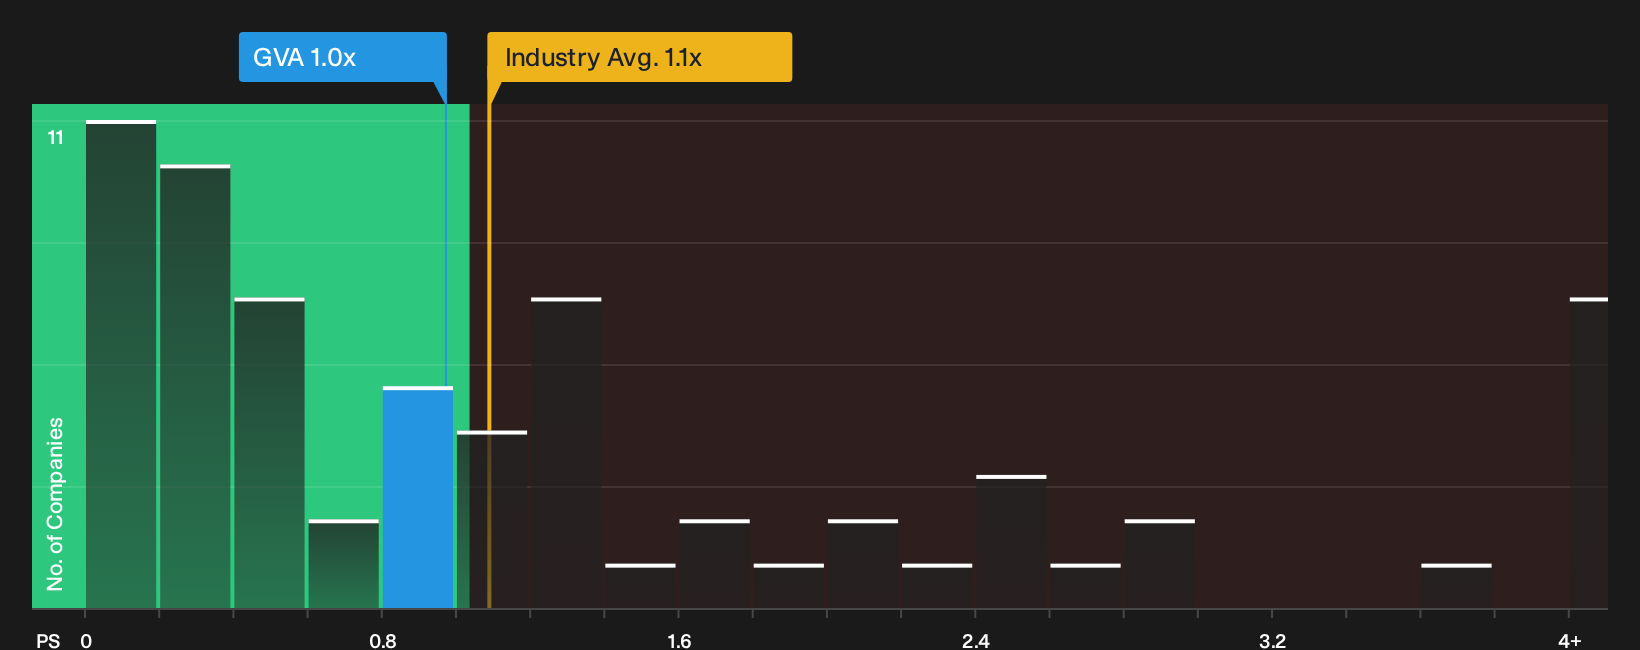
The first take leans on analyst fair value and future earnings power. A different lens is the current P/S ratio of roughly 1x. That is higher than the peer average of 0.8x yet just under a fair ratio of 1.1x, which points to limited outright mispricing but some valuation risk if expectations slip.
The gap is small in numeric terms, but in practice it means Granite Construction is priced a little richer than similar contractors while only modestly below where the market could move the ratio toward that fair ratio. The question for anyone watching the stock is simple. Are you comfortable paying close to peer levels while the business is still loss making?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Granite Construction so far. If the blend of risks and potential rewards feels finely balanced, consider acting promptly, review the underlying data, and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Granite Construction?
If Granite Construction has sharpened your focus on infrastructure, do not stop here. Broader opportunity often sits with the stocks you have not checked yet.
- Target steady compounders by scanning for companies with strong fundamentals and net cash positions through the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced quality by checking companies that combine robust cash flows with attractive valuations using the 33 high quality undervalued stocks.
- Prioritize sleep-at-night holdings by reviewing companies that carry resilient, lower risk profiles via the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com