
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Ericsson Stock Earnings Beat
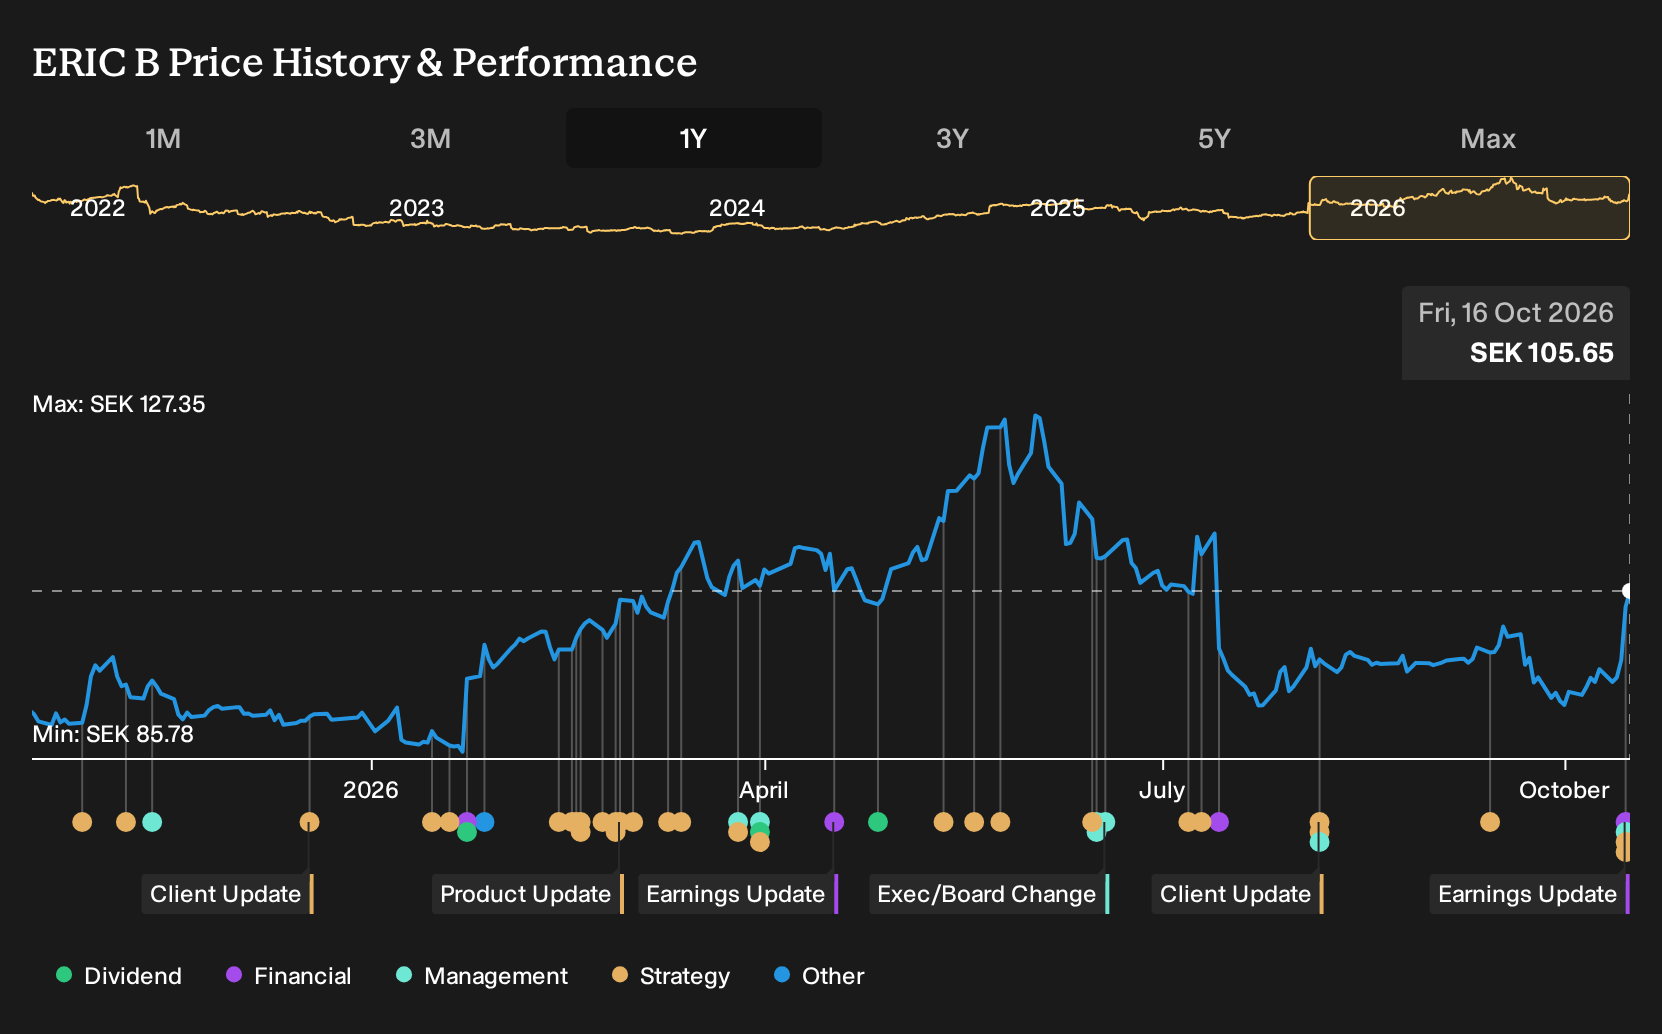
- Telefonaktiebolaget LM Ericsson reported Q3 2026 sales of SEK 59,478 million with net income of SEK 5,806 million, and also completed SEK 8,100 million of share repurchases equal to 2.37% of its shares under the current buyback.
- The group is overhauling its structure by merging Asian market areas into a single APAC unit and redistributing Enterprise Wireless Solutions into other segments to concentrate R&D, address Enterprise profitability pressure and sharpen focus on high demand network businesses.
- The next focus will be on how Ericsson's earnings beat and Enterprise reorganization shape the existing investment narrative around margins and capital returns.
Scan Ericsson alongside peers facing similar margin and capital allocation questions by checking a hand picked set of list of solid balance sheet and fundamentals (203 results) in the same session.
Telefonaktiebolaget LM Ericsson Investment Narrative Recap
To own Telefonaktiebolaget LM Ericsson, you need to believe its core Networks and Cloud Software and Services operations can keep converting 5G and digital transformation demand into resilient earnings, even while net income and EPS have recently softened. The near term swing factor is whether management can protect gross margins as component costs rise and operator capex stays cautious.
The biggest risk sits in Enterprise, where losses and a slower path to breakeven could keep group profitability under pressure. The Q3 2026 earnings beat helps sentiment but does not fully resolve that concern. The completed share buyback matters for capital returns, not the underlying operating challenge.
The reorganization of Business Area Enterprise Wireless Solutions looks most relevant here. Ericsson is moving Neutral Host and Private 5G into the Networks segment and leaving Wireless WAN as a separate unit. That shift puts enterprise connectivity bets closer to the profitable core network franchise, which could simplify execution on private networks and differentiated connectivity projects.
For you, the question is whether this new structure shortens the path from enterprise demand to group margins. If Enterprise losses persist after the portfolio reshuffle, the risk narrative around earnings quality remains intact. If execution improves, it could reinforce the idea that Ericsson’s exposure to 5G stand alone, AI heavy traffic and industrial automation can gradually support more balanced profit contributions.
What Current Assumptions Say About Ericsson’s Trajectory
Analysts sketch a relatively steady top line for Telefonaktiebolaget LM Ericsson, with revenue expected to stay fairly flat over the next few years while profit margins compress from 10.8% today to 8.6% in three years. Earnings today are put at SEK 24.6b, with consensus pointing to SEK 19.9b of profit and earnings per share of SEK 6.4 by 2029, and a wide spread between the most optimistic SEK 26.4b view and the most cautious SEK 14.9b scenario. On these forecasts, the gap between current earnings and the 2029 consensus implies an earnings decline of SEK 4.7b from today into that estimate year.
Telefonaktiebolaget LM Ericsson’s current narrative ties together those expectations with a fair value view that hinges on 2029 outcomes. For the analyst targets to make sense, investors would need to assume revenue of SEK 232.3b and earnings of SEK 19.9b by 2029, with the stock trading on a P/E of 19.3x compared with 12.6x today and a sector level of 18.7x. The consensus price target of SEK 96.53 sits only 2.2% above the recent share price of SEK 94.4, which signals that many on the Street see the shares as roughly in line with these longer term revenue and earnings assumptions.
Telefonaktiebolaget LM Ericsson’s narrative projects SEK 232.3b revenue and SEK 19.9b earnings by 2029. This reflects fairly flat yearly revenue trends and an earnings decrease of SEK 4.7b from SEK 24.6b today.
Uncover why Telefonaktiebolaget LM Ericsson's fair value indicates a 9% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate view on Telefonaktiebolaget LM Ericsson leans heavily on Enterprise as a future earnings engine. Those optimistic analysts were already pencilling in SEK 252.9b of revenue and SEK 26.2b of profit by 2029, well above consensus. With the Q3 beat, buyback progress and restructuring now on the table, those opposing narratives may evolve.
Explore 4 other Telefonaktiebolaget LM Ericsson fair value estimates, including one that suggests potential upside of up to 22% from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Telefonaktiebolaget LM Ericsson research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Telefonaktiebolaget LM Ericsson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Telefonaktiebolaget LM Ericsson's overall financial health at a glance.
Looking For More Investment Ideas Beyond Telefonaktiebolaget LM Ericsson?
Once you have formed a view on Telefonaktiebolaget LM Ericsson, it can help to compare that thesis with other opportunities that share similar financial qualities or risk profiles. A focused screen gives you a filtered set of stocks to review rather than an endless watchlist.
- If you want potential mispricing with balance sheet support in the background, start with a curated set of 191 high quality undervalued stocks that pair quality fundamentals with discounted valuations.
- For investors who care most about capital strength and staying power, scan a list of solid balance sheet and fundamentals (203 results) to find businesses with cleaner debt profiles and sturdier finances.
- When you are hunting for underfollowed opportunities, a 618 high quality undiscovered gems can surface companies with sound metrics that are still off most radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com