
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Sainsbury's (LSE:SBRY) Picard Frozen Food Rollout
- J Sainsbury has agreed to stock French frozen food retailer Picard in more than 150 UK supermarkets from 26 October 2026, widening its branded frozen offer and giving Picard broader physical access to British shoppers.
- This tie up plugs an established continental frozen specialist into Sainsbury's grocery focused store base, which could test how UK consumers respond to a richer, quality led frozen assortment alongside existing own label ranges.
- We will now look at how J Sainsbury's investment narrative could be affected by adding Picard frozen ranges across its stores.
Scan how this frozen-food tie up with J Sainsbury compares to other food retailers by reviewing our curated list of list of solid balance sheet and fundamentals (9 results)
J Sainsbury Investment Narrative Recap
To own J Sainsbury, you need to believe the shift toward higher food intensity, stronger Nectar loyalty economics and £1b of cost savings by 2027 can outweigh margin pressure from wages, taxes and promotions. The Picard frozen range broadens assortment, but on its own looks modest next to these bigger operational levers.
The key near term swing factor remains how effectively Sainsbury controls operating costs while trying to grow grocery volume share. Rising input costs and intense price competition still threaten margins. The Picard deal mainly tests customer appetite for more premium frozen options, so the impact on group profitability may not be material initially.
Recent commentary around Nectar and retail media, including the plan for Nectar360 to add about £100m of profit, feels more central to this Picard move. If Picard products attract data rich, repeat customers, that can feed directly into loyalty personalisation and advertising income on top of the frozen aisle sales.
For you as an investor, the interesting question is execution. Sainsbury is reallocating store space toward food, building higher margin Taste the Difference ranges and exiting Argos to Swift to simplify the group and reduce debt. Picard fits into that story as another test case for whether premium, convenience led food propositions can support those core catalysts without adding undue complexity or cost.
J Sainsbury's narrative projects £35.4b revenue and £481.0m earnings by 2029. This assumes 1.7% yearly revenue growth and an earnings increase of about £67m from £414.0m today.
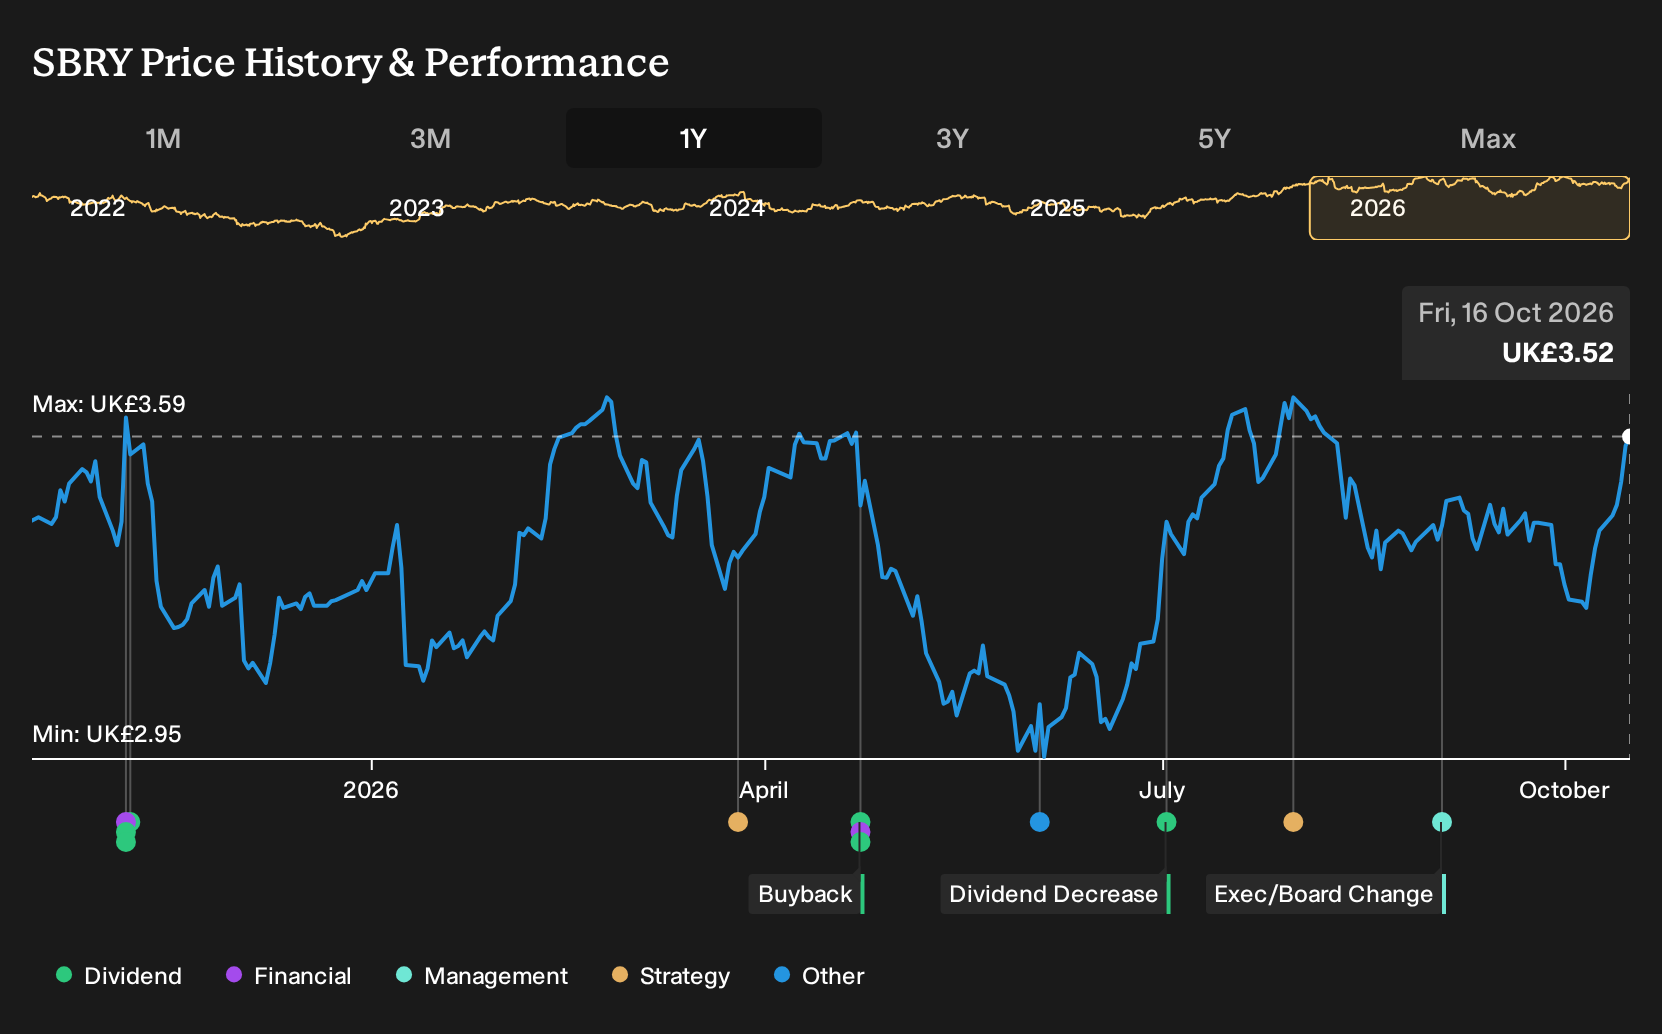
Uncover why J Sainsbury's fair value indicates that J Sainsbury is in line with its current price.
Exploring Other Perspectives
The Simply Wall St Community only supplies two fair value views on J Sainsbury, yet they already stretch from about 3.61 to 4.66, which shows how far private investors can diverge. When you also consider risks around Argos drag, rising operating costs and tougher grocery pricing, you have plenty of reason to compare several alternative viewpoints yourself.
Explore another J Sainsbury fair value estimate, including one that suggests there could be as much as 32% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your J Sainsbury research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for J Sainsbury. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate J Sainsbury's overall financial health at a glance.
Looking for more investment ideas beyond J Sainsbury?
Once you have formed a view on J Sainsbury, it can help to compare that thesis with other businesses that have different risk and income profiles. The Simply Wall St Screener lets you filter for very specific characteristics so you can build a watchlist that fits your goals rather than someone else's model portfolio.
- If you want potential income plus resilience, start with companies that have offered stronger cash distributions by reviewing 2 dividend fortresses that may suit a yield focused approach.
- For investors who care most about quality at a reasonable entry point, use our filters centered on valuation and balance sheet strength to scan 7 high quality undervalued stocks that currently screen well on both fronts.
- If capital preservation matters to you as much as upside potential, narrow the field to businesses with steadier fundamentals by checking companies in the 4 resilient stocks with low risk scores that pass our lower risk criteria.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com