
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
BYD (SEHK:1211) Is Back In The Spotlight, What Is Driving Attention Now?
Debate over higher UK tariffs on Chinese electric vehicles has put BYD (SEHK:1211) in the spotlight, as policymakers weigh measures that could reshape the company’s pricing power and export economics into Europe.
BYD’s share price has come under pressure this year, with a year to date share price return down 25.32% and a 1 year total shareholder return down 28.20%. The latest 1 day gain of 1.10% hints at sentiment reacting quickly to tariff headlines and recent regional expansion moves, such as the Malaysia assembly tie up.
Scan 618 high quality undiscovered gems that, like BYD, are in the spotlight of global trade shifts yet may still be flying under most investors’ radar.
After a year of double digit share price declines and fresh tariff worries colliding with BYD’s Malaysia expansion, does the balance of risk and potential reward still tilt toward buyers from today’s HK$73.75 level, or not?
Most Popular Narrative: 14% Undervalued
BYD’s most followed narrative pegs fair value at HK$85.40, a premium to the current HK$73.75 share price. This frames tariff worries against a longer term expansion story.
BYD is a bet on scalable energy. While other brands depend on third-party battery suppliers, BYD dictates the rules of the game, turning the car into a "smartphone on wheels" with record-breaking range. Full control over the supply chain, from lithium mining to in-house microchip production, allows BYD to win the price wars currently shaking the global EV market.
See why 11 investors see BYD as 14% undervalued.
Result: Fair Value of HK$85.40 (UNDERVALUED)
Still, the BYD story faces real pressure from potential EU tariff hikes and any slowdown in overseas demand that could test its export-heavy revenue mix.
Find out about the key risks to this BYD narrative.
Another View On BYD’s Valuation
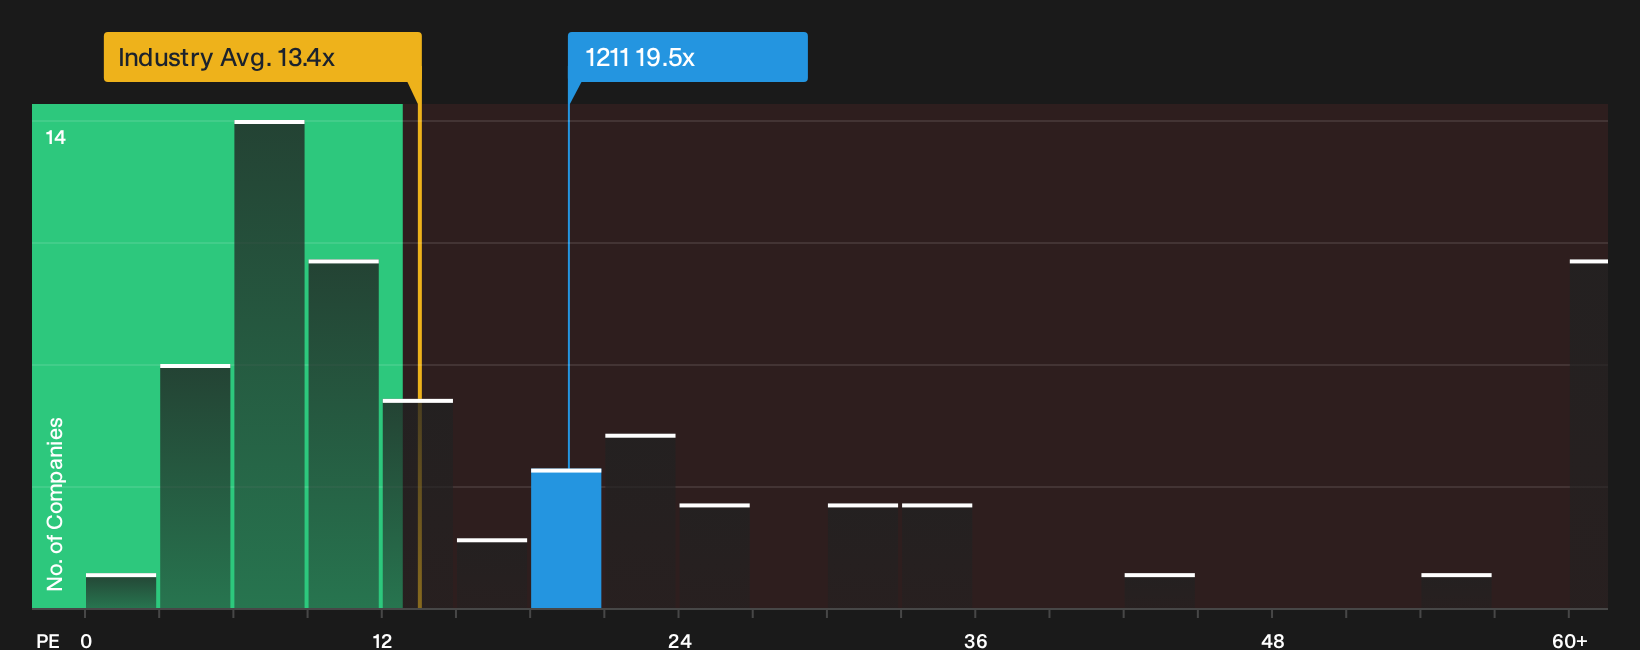
The first narrative leans on a user fair value of HK$85.40 for BYD. A different lens tells a tougher story. On a P/E of 19.5x, the stock trades above its fair ratio of 11.7x and the Asian auto average of 13.4x, which points to valuation risk if sentiment cools.
To see how that premium multiple stacks up against the underlying numbers and peers, take a closer look at our valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The tone of the BYD debate appears mixed, reflecting the push and pull between tariffs and valuation figures. Consider acting promptly, reviewing the full range of risks and potential upsides, and stress testing the story for yourself through 3 key rewards and 1 important warning sign
Looking For More BYD-Like Investment Ideas?
If you want a broader shortlist before making a call on BYD, use targeted screeners to surface stocks that match your risk, income, and quality preferences.
Scan fresh ideas across markets quickly and stay ahead of the crowd instead of reacting late when stories are already priced in.
- Target potential mispricings by checking companies flagged in the 191 high quality undervalued stocks so you are not relying only on headline narratives.
- Identify income-focused ideas by reviewing the 214 dividend fortresses and assessing whether those cash payouts align with your return goals.
- Reduce downside surprises by focusing on the 233 resilient stocks with low risk scores to keep your watchlist anchored in financial resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com