
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 AI Infrastructure Stocks Retail Investors Are Watching For Data Center Growth
AI infrastructure has turned into the picks and shovels story of this cycle, with spending on chips, data centers and power systems pushing ahead despite higher rates. That flow of capital is reshaping which stocks feel the tailwind and which get left out. This article breaks down how that backdrop connects to real tickers and reveals 3 stocks directly exposed to this AI spending wave.
The three stocks below are just a starter pack from this AI infrastructure theme, and the full screen surfaced 57 more companies with equally compelling narratives that do not fit into a short article. To go deeper into the AI picks and shovels angle, head straight into the AI Infrastructure Enablers (Semiconductors, Data Centers, Power & Electrical Equipment) screener to analyze, filter, and identify the highest conviction ideas.
Taiwan Semiconductor Manufacturing (TWSE:2330)
Overview: Taiwan Semiconductor Manufacturing builds and packages advanced chips that power AI data centers, high performance computing, smartphones, cars, and connected devices worldwide.
Market Cap: NT$62,756,335.4 million
For the AI infrastructure theme, Taiwan Semiconductor Manufacturing is a focused way to gain exposure to the demand for advanced AI accelerators and data center silicon without concentrating on any single chip designer.
"AI-returned capital intensity risk: The 2026 capex budget rose to $60 to $64B, up from roughly $52 to $56B in January."
What matters now is how this unresolved pressure on future returns may affect pricing power, utilization, and long-run margins.
If that pressure on future returns is what you keep circling back to, the full narrative for Taiwan Semiconductor Manufacturing shows how AI demand, capital intensity, and potential upside could still be decoupling.

Sterling Infrastructure (STRL)
Overview: Sterling Infrastructure provides e-infrastructure site work for large data centers and industrial facilities, plus transportation and building services across key U.S. regions.
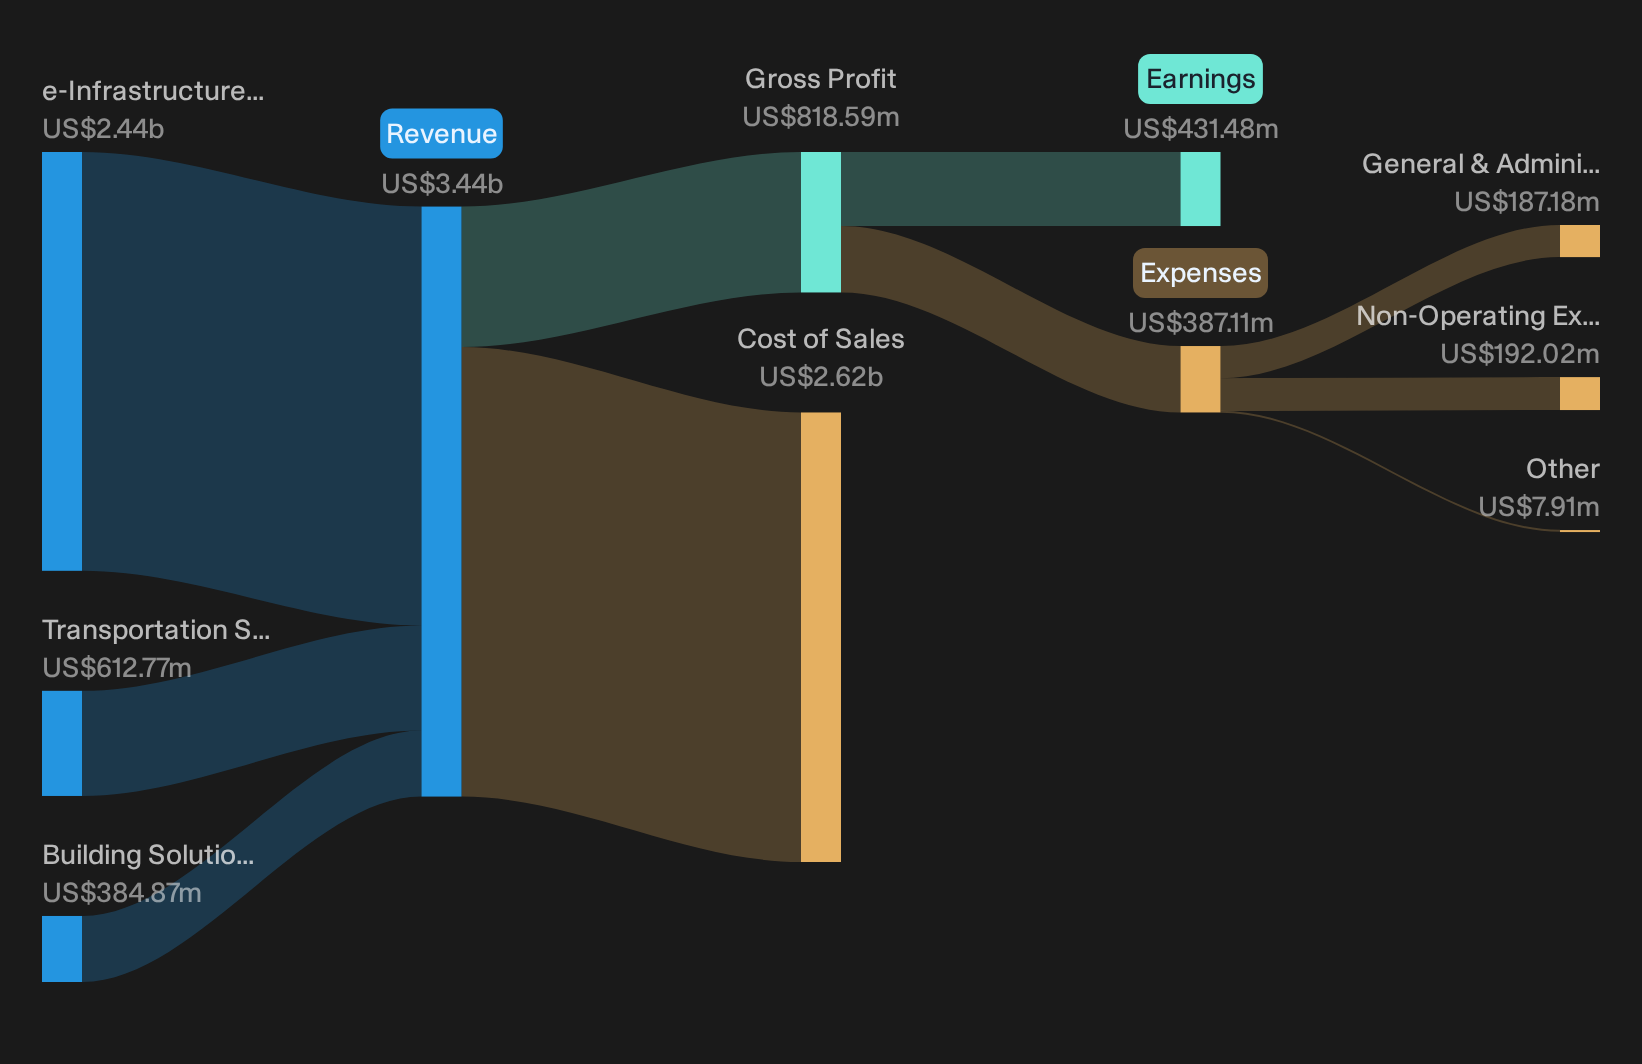
Operations: Sterling Infrastructure generates about US$2.4b from e-Infrastructure Solutions, US$612.8 million from Transportation Solutions, and US$384.9 million from Building Solutions, entirely in the United States.
Market Cap: US$13.0b
Sterling Infrastructure is positioned in the AI buildout by preparing the ground, power connections, and civil works that turn chip and cloud spending into actual data center campuses.
"Sterling Infrastructure’s multi year pool of signed backlog and high probability future phase work now exceeds US$7b, heavily weighted to mission critical data center and semiconductor projects."
What investors need to watch is how any constraint on execution capacity shapes the margins those long dated AI projects ultimately deliver.
Those execution bottlenecks are exactly what the full narrative for Sterling Infrastructure unpacks, showing how Sterling Infrastructure’s backlog, pricing, and capacity could be quietly reshaping its AI leverage.
Hammond Power Solutions (TSX:HPS.A)
Overview: Hammond Power Solutions designs and manufactures transformers and related power equipment that feed electricity into data centers and high load AI facilities.
Operations: Hammond Power Solutions generates approximately CA$1.1b from manufacturing and selling transformers, with around CA$805.9 million from the United States and Mexico and CA$221.7 million from Canada.
Market Cap: CA$3.1b
Hammond Power Solutions sits squarely in the AI infrastructure theme because its transformers help route grid power into racks of servers and GPUs that actually run AI workloads.
"Robust and accelerating demand from data center projects, highlighted as the fastest-growing segment and supported by ongoing digitization trends, is expected to drive sustained order flow and backlog, positively impacting top-line growth and supporting consistent earnings."
What ultimately happens to Hammond Power Solutions’ earnings will hinge on how one less visible cost pressure interacts with that swelling demand.
That cost pressure is exactly where the full narrative for Hammond Power Solutions shows how accelerating data center demand, pricing power, and supply risks could be quietly reshaping Hammond Power Solutions’ AI exposure.

Curious About What You Might Be Missing?
Fresh ideas tend to move first. The best breakout stories often fly before most investors even notice. Scan these curated lists while it still matters and get in early.
- Spot resilient cash generators before momentum headlines catch them by running a quick pass through the list of solid balance sheet and fundamentals (203 results), curated for financial strength and staying power.
- Hunt for income workhorses that keep paying even when sentiment drops by zeroing in on the 214 dividend fortresses, built around durable, high yielding payouts.
- Track under the radar growth stories that could be quietly building steam by filtering through the 618 high quality undiscovered gems, focused on quality businesses still off most radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com