
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is A. O. Smith (AOS) Undervalued After Its 6% Dividend Raise?
A. O. Smith (AOS) has approved a 6% increase in its quarterly cash dividend to $0.38 per share, covering both Common and Class A shares, with payment scheduled for November 16, 2026.
A. O. Smith’s higher dividend lands against a mixed share price backdrop, with the 7-day share price return of 5.0% hinting at improving short-term momentum, while the year-to-date share price return of 13.3% and 1-year total shareholder return of 13.2% both reflect recent weakness.
Scan how A. O. Smith compares with other income-focused opportunities by reviewing our hand-picked 8 dividend fortresses, featuring companies that have weathered recent volatility with robust cash generation and consistent payouts.
A. O. Smith shares have fallen 13% over the past year, even as the stock trades about 17% below analyst targets and roughly 31% below an intrinsic estimate. Is that discount a sign of caution or an opportunity?
Most Popular Narrative: 7.7% Overvalued
A. O. Smith closed at $59.22, while the most followed narrative, using a fair value of $55, frames the stock as slightly rich and heavily shaped by its North American engine and China drag.
AOS manufactures water heaters and boilers in North America, with a secondary business in China that is in structural decline. The North American franchise is genuinely strong: three players control more than 90% of the market, the product is a non-discretionary emergency replacement in more than 80% of cases, and prices have risen above inflation for twelve consecutive years. The company generates around $550M in free cash flow annually against a market capitalisation of roughly $8B. It has paid a growing dividend for 34 consecutive years and has reduced its share count nearly 10% over five years.
See why 2 investors see A. O. Smith as 8% overvalued.
Result: Fair Value of $55 (OVERVALUED)
Still, two pressure points could flip that script: a prolonged China drag on margins and a heat pump shift that erodes A. O. Smith’s distribution edge.
Find out about the key risks to this A. O. Smith narrative.
Another View On A. O. Smith Valuation
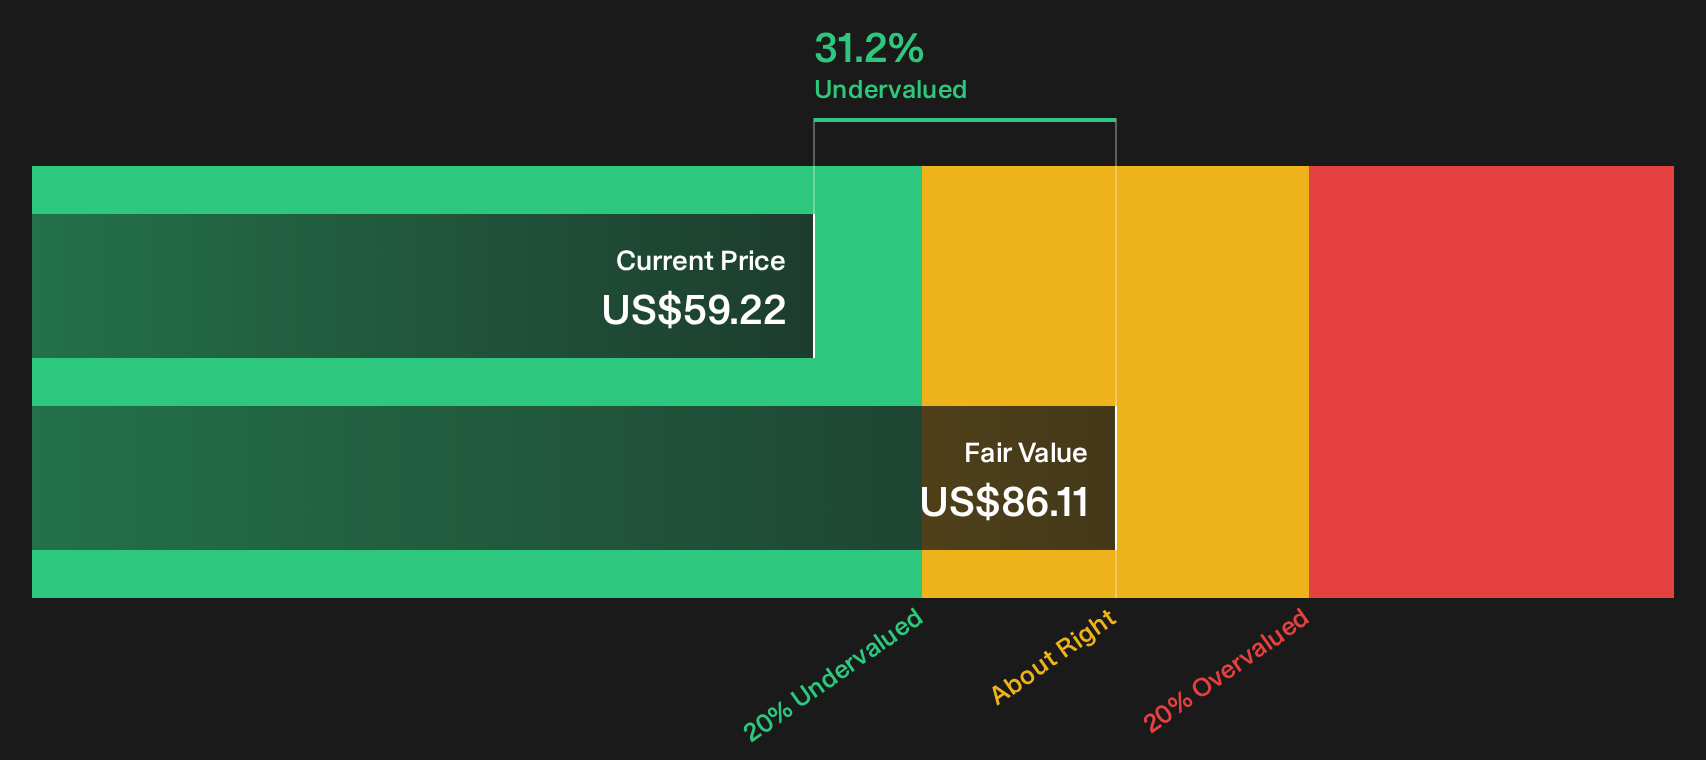
The narrative pegs A. O. Smith at $55 fair value and slightly overvalued at $59.22. Our DCF model points the other way. It puts future cash flow value nearer $86.11, which implies the shares trade at roughly a 31% discount. Which story do you trust when the gap is this wide?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on A. O. Smith valuation are one thing; your own work is another, so move quickly through the numbers, narratives, and 4 key rewards.
Looking for more A. O. Smith sized ideas?
If A. O. Smith has sharpened your focus on quality, do not stop here. Broaden your watchlist and pressure test your thesis across fresh opportunities.
- Target resilience first by scanning a 32 resilient stocks with low risk scores that can help you focus on businesses with steadier risk profiles and fewer financial surprises.
- Hunt for value by checking a 20 high quality undiscovered gems that may highlight underfollowed companies with solid fundamentals before they hit wider radars.
- Anchor your core holdings with a list of solid balance sheet and fundamentals (25 results) that points you toward stronger balance sheets and sturdier financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com