
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Toyoda Gosei (TSE:7282) Could Be 52% Undervalued Following Its 1 For 5 Stock Split
Toyoda Gosei (TSE:7282) has scheduled a 1-for-5 stock split for 29 September 2026, a move that will adjust both the share count and the trading price mechanics for existing investors.
The stock split comes after a strong run in Toyoda Gosei’s shares, with the latest share price at ¥1,068 and a year to date share price return of 32.64%, while total shareholder return over five years is 171.11%. This suggests that momentum has been building as investors reassess both prospects and risks.
Scan other potential beneficiaries of strong price action and corporate moves such as Toyoda Gosei's stock split by checking our hand picked 14 high quality undervalued stocks in related sectors.
After a sharp run and a 1-for-5 split on the way, Toyoda Gosei trades at a discount to both intrinsic estimates and analyst targets. Is that a genuine margin of safety or a warning label?
Price-to-earnings of 9.4x: Is it justified for Toyoda Gosei?
On simple numbers, Toyoda Gosei looks inexpensive. The shares trade on a P/E of 9.4x, while the stock is also flagged as trading at a 51.8% discount to an estimated fair value, with our DCF model indicating a future cash flow value of ¥2,215.76 versus a last close of ¥1,068.
The P/E ratio measures how much investors are paying today for each unit of current earnings. For an auto components manufacturer with established operations across Japan, the Americas, Europe, Africa, China, Asia, and India, this is a straightforward way to compare what the market is willing to pay for Toyoda Gosei’s profit stream against other businesses.
The signals here pull in two directions. Against its own estimated fair P/E of 12x, the current 9.4x looks restrained and suggests the market is assigning a lower multiple than that model-based level could support. Against the JP Auto Components industry average of 9.2x, the stock is described as slightly expensive, which points to investors paying a small premium to sector peers even as the fair ratio framework implies room for the multiple to move higher.
Explore the SWS fair ratio for Toyoda Gosei.
Result: Price-to-earnings of 9.4x (UNDERVALUED)
Still, Toyoda Gosei faces pressure from its heavy exposure to cyclical auto demand and the execution risk of balancing growth projects with shareholder returns.
Find out about the key risks to this Toyoda Gosei narrative.
Another View on Toyoda Gosei’s value
The P/E story suggests Toyoda Gosei looks inexpensive. The SWS DCF model goes further, with an estimated future cash flow value of ¥2,215.76 per share versus the current ¥1,068 price, which screens as undervalued. If both tools lean the same way, where is the real risk sitting for you?
Look into how the SWS DCF model arrives at its fair value.
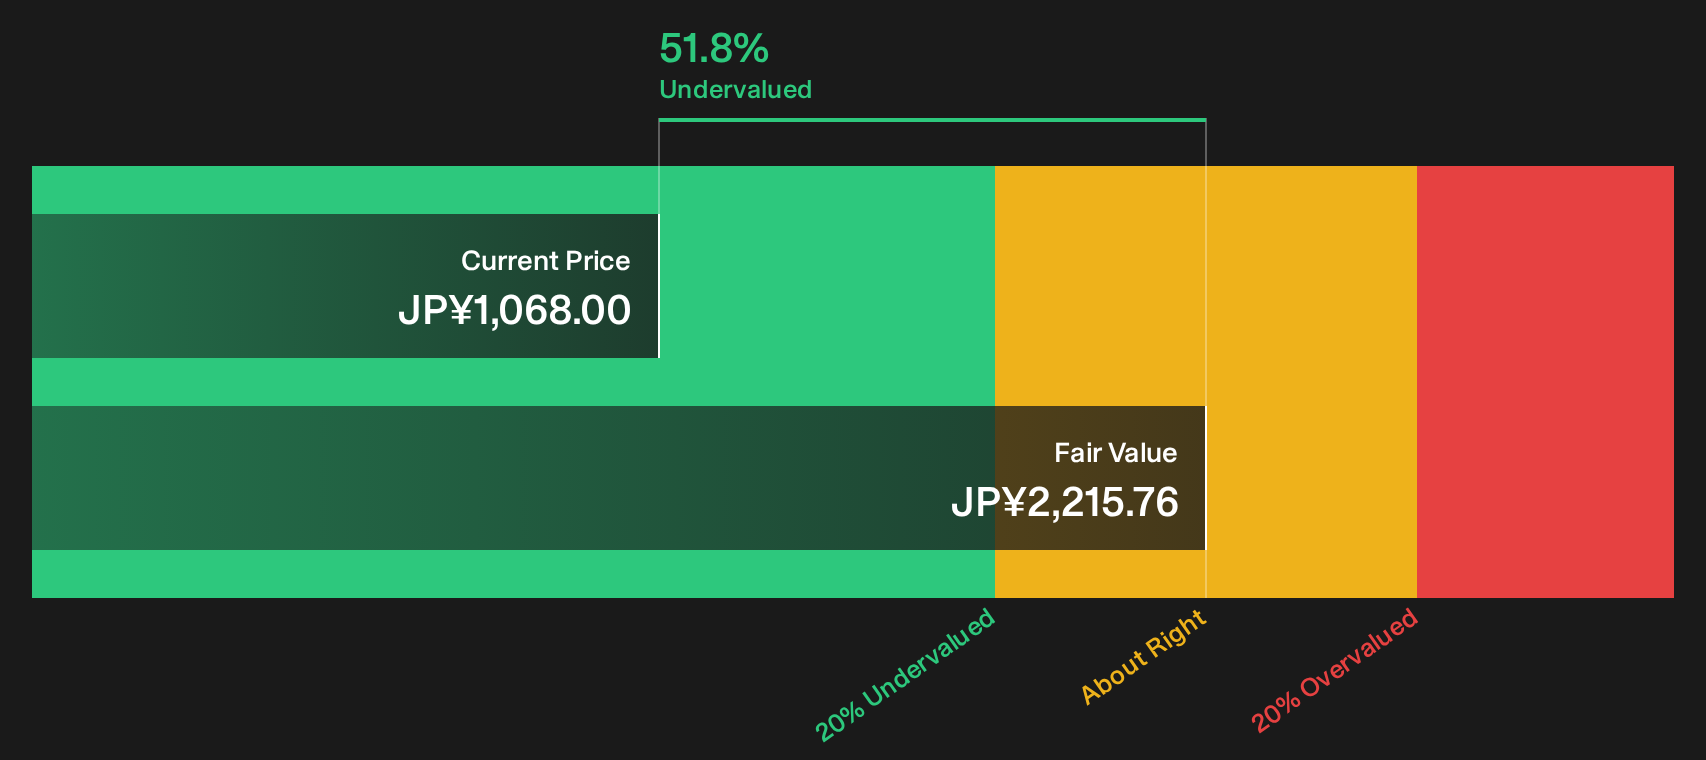
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Toyoda Gosei for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Toyoda Gosei’s setup appears balanced between opportunity and risk. Consider acting promptly, test the assumptions against your own research, and weigh the 3 key rewards and 1 important warning sign.
Hunting for more Toyoda Gosei style ideas?
If Toyoda Gosei has you thinking harder about value and timing, do not stop at one stock. Put a few fresh candidates on your radar today.
- Chase value with quality by scanning our hand picked 14 high quality undervalued stocks that combine appealing pricing with fundamental strength.
- Prioritise resilience by running through a list of solid balance sheet and fundamentals (21 results) so you focus on businesses with sturdier financial footing.
- Get ahead of the crowd by reviewing a 73 high quality undiscovered gems that have strong fundamentals before wider attention arrives.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com