
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did New CFO Appointment Just Shift Hammerson's (LSE:HMSO) Investment Narrative?
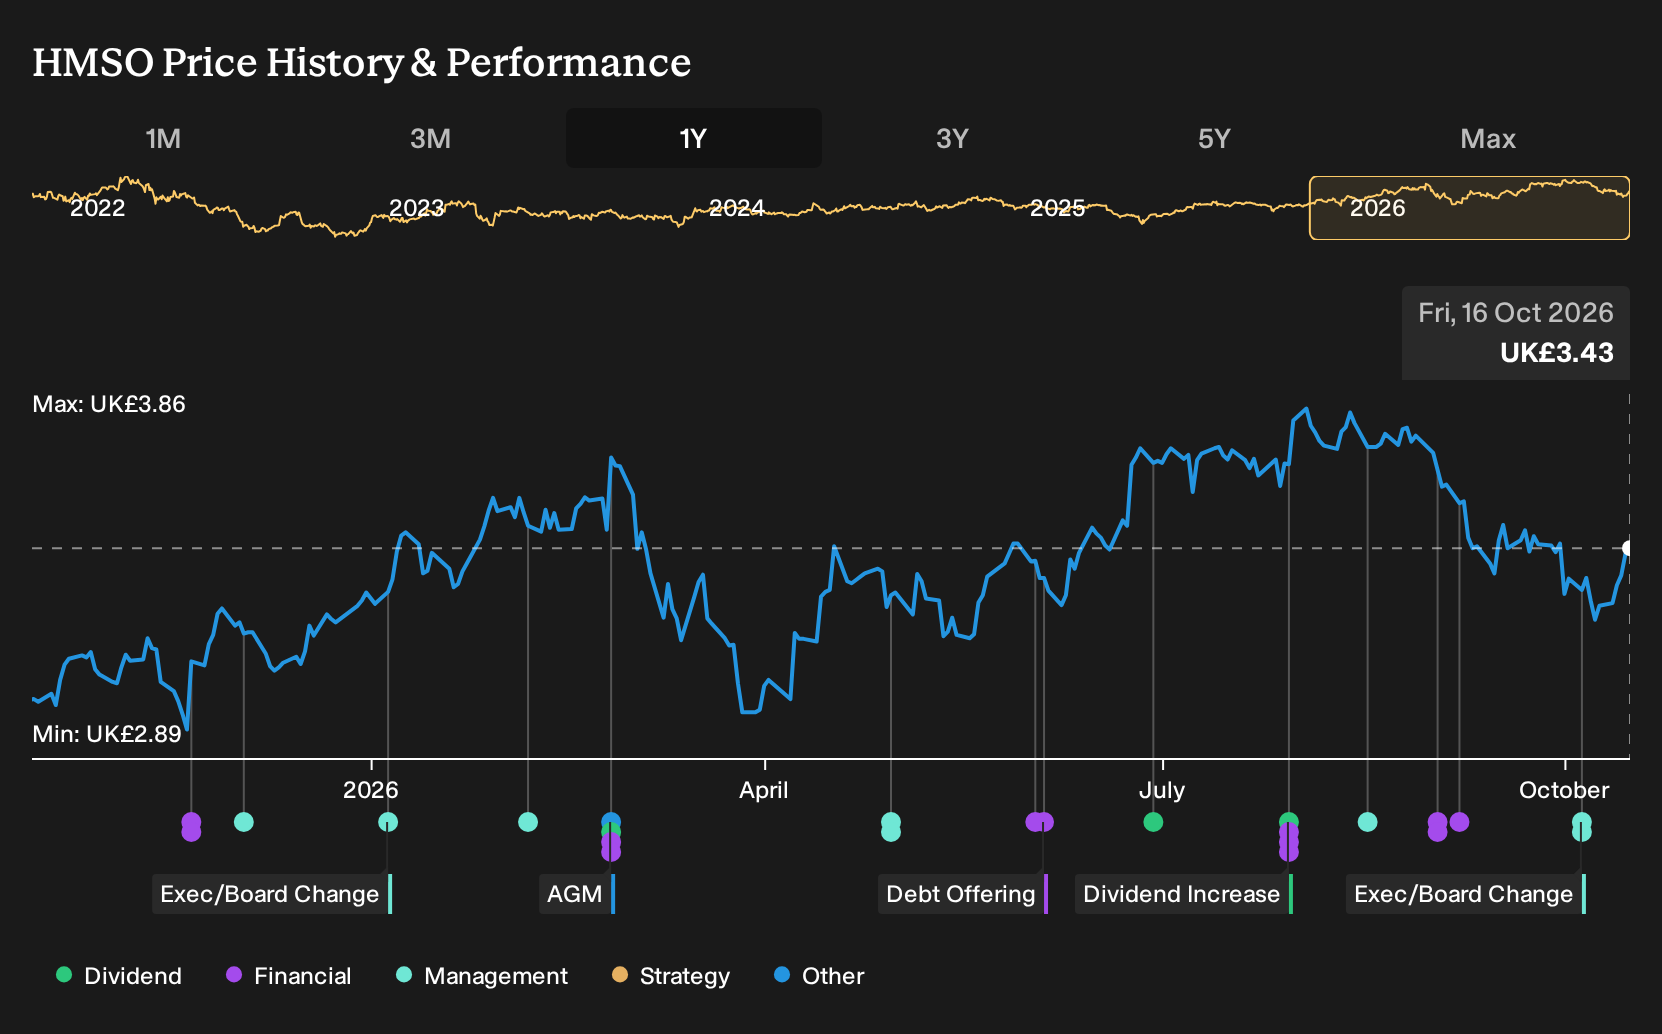
- Hammerson has appointed Gina Szymanski as Chief Financial Officer and Board Director after a search process, with her expected to assume both roles by 1 January 2027, subject to UK work visa approval.
- Szymanski’s background in REITs, capital markets and corporate strategy from AEW Capital Management aligns directly with Hammerson’s focus on mixed-use assets, data-led leasing and balance sheet discipline.
- We will now examine how Hammerson's investment narrative is influenced by Szymanski's appointment as CFO and Board Director.
Scan how other REIT focused businesses handle capital allocation and balance sheet discipline by reviewing our curated list of list of solid balance sheet and fundamentals (9 results) alongside Hammerson today.
Hammerson Investment Narrative Recap
To own Hammerson, you need to believe its prime city destinations can keep drawing tenants and shoppers even as e commerce chips away at traditional retail. The shorter term story still hinges on keeping occupancy around current levels, pushing rents on relettings, and progressing mixed use projects without letting £60 million of growth CapEx dilute returns.
The biggest near term risk remains leverage and refinancing. Debt is not well covered by operating cash flow and loan to value has risen, so interest costs matter a lot. Gina Szymanski’s appointment may help tighten capital allocation and balance sheet discipline, but the announcement alone does not remove that funding risk.
The most relevant announcement here is Szymanski’s move from AEW Capital Management, where she has been Global Securities Chief Investment Officer, into Hammerson’s CFO and Board roles. Her background spans REITs, capital markets and forensic accounting, which lines up with the focus on asset recycling, data led leasing and careful funding decisions.
For you, the link to catalysts is straightforward. Hammerson is leaning on asset disposals, mixed use redevelopment and AI driven leasing to support earnings that analysts forecast to grow 7.2% a year, while managing a balance sheet where debt coverage is a concern. Execution will depend heavily on how the new finance chief shapes funding, CapEx pacing and disposals once in post.
Hammerson's narrative projects £321.6 million in revenue and £251.7 million in earnings by 2029. This assumes 1.2% yearly revenue growth and an increase in earnings of about £42.5 million from £209.2 million today.
Uncover why Hammerson's fair value indicates a 15% potential upside to its current price before momentum in Hammerson closes that gap.
Exploring Other Perspectives
One alternate angle on Hammerson focuses less on leverage risk and more on the bullish catalyst of higher rent potential from its top tier city destinations. The most optimistic analysts were already modelling revenue of about £306.8 million and earnings near £254.8 million by 2029. Gina Szymanski’s appointment could shift those assumptions again, so treat this as one of several viewpoints to test for yourself.
Explore another Hammerson fair value estimate, including one that suggests there could be as much as 15% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgement.
- A great starting point for your Hammerson research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Hammerson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate Hammerson's overall financial health at a glance.
Looking For More Ideas Beyond Hammerson?
If you want to stress test your thesis on Hammerson, compare it with other businesses that share similar qualities or solve very different problems in your portfolio. The Simply Wall St Screener can help you quickly surface a shortlist that fits the type of opportunity you are hunting for today.
- For investors who care most about quality at a reasonable entry point, start with a focused set of 7 high quality undervalued stocks that pair solid fundamentals with attractive pricing.
- If capital preservation is your main priority, balance Hammerson with 4 resilient stocks with low risk scores that score well on financial resilience and business stability.
- To round out your watchlist with less crowded ideas, scan 5 high quality undiscovered gems that combine strong financial traits with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com