
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Earnings Expectations Just Shift AppFolio's (APPF) Investment Narrative?
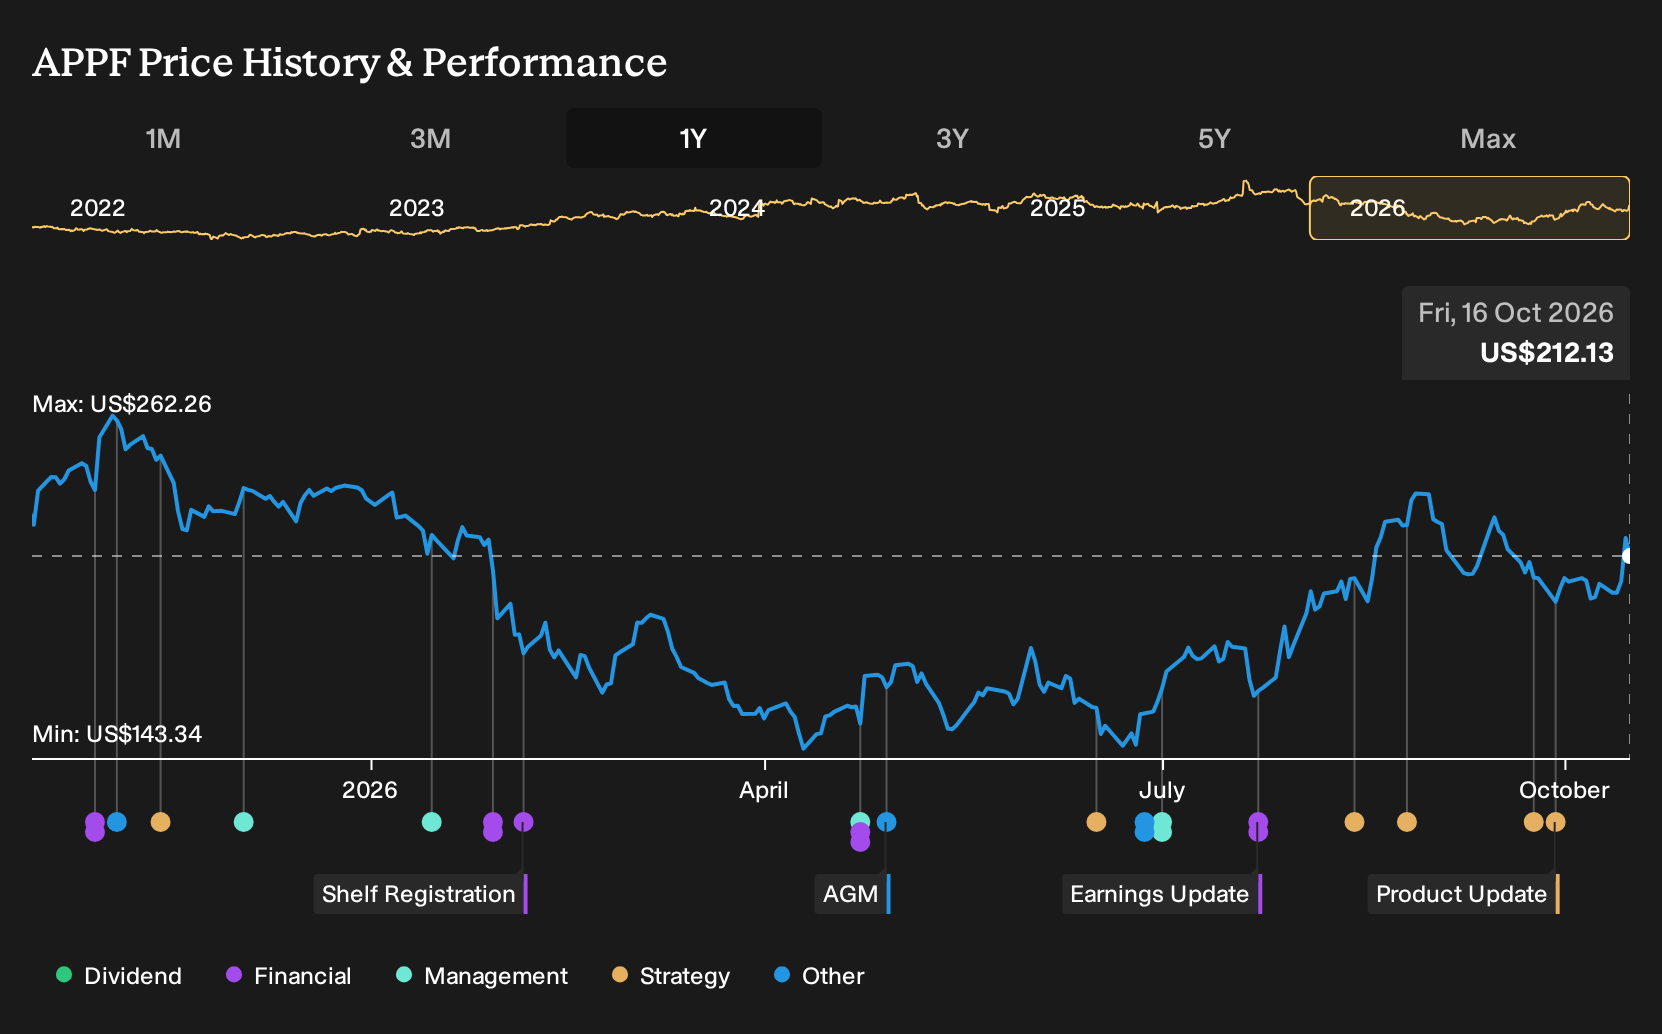
- AppFolio is approaching its October 22, 2026 earnings release, with analysts expecting higher earnings and revenue for the September quarter compared with a year earlier.
- The recent shift toward a lower Most Accurate Estimate and a negative Earnings ESP highlights growing scrutiny of how AppFolio converts product usage and services into reported profitability.
- We will now look at how AppFolio's investment narrative could be influenced by the upcoming earnings report and more cautious estimates.
Compare how AppFolio's setup ahead of earnings lines up against a curated group of resilient companies screened for 32 resilient stocks with low risk scores.
AppFolio Investment Narrative Recap
To own AppFolio, you need to believe its AI powered Realm platform, premium tiers and value added services can keep lifting what each managed unit is worth, without letting higher cloud and payments costs eat into that progress. The recent share price pullback ahead of earnings does not change that core thesis by itself.
The immediate catalyst is the 22 October earnings release, where investors will focus on revenue per unit trends, uptake of premium plans and the mix of higher margin services. The biggest near term risk stays the same. Usage could keep tilting toward costlier AI and payment features faster than pricing and efficiency gains offset those expenses.
The most relevant fresh data point is the negative Earnings ESP and the drop in the Most Accurate Estimate before this quarter. That shift tells you short term expectations around how AppFolio converts product usage into reported profit have become more cautious, even though headline consensus still looks for higher earnings and revenue.
That tension between strong operational catalysts and more guarded near term estimates puts execution under the microscope for this print. Clean delivery on AI adoption, premium penetration and cost control would support the longer term story. A miss on margins or unit economics would amplify existing worries about rising infrastructure spend and recent insider selling.
What The Current AppFolio Forecasts Assume
AppFolio's current analyst narrative leans on a specific set of numbers rather than vague optimism. The forecast points to about 16.8% yearly revenue growth over the next few years, profit margins stepping up from 15.1% today to 18.8% in roughly three years, and earnings moving from US$157.5 million now to US$311.9 million by 2029. That implies earnings a little under 2x higher than today, alongside an expected 1.4% annual decline in share count. Together these factors shape the per share math investors are weighing.
AppFolio's narrative projects US$1.7b revenue and US$311.9 million earnings by 2029. This requires 16.8% yearly revenue growth and an earnings increase of roughly US$154 million from US$157.5 million today.
Uncover why AppFolio's fair value indicates an 11% potential upside to its current price that could narrow quickly if sentiment shifts after earnings.
Exploring Other Perspectives
One alternate view on AppFolio focuses on insider selling rather than AI momentum. The most cautious analysts see the recent US$3.3 million of stock sold by insiders as a warning sign and estimate 2029 earnings at around US$306.7 million on US$1.7b revenue. That is a more reserved outlook than the consensus, and both sets of forecasts were shaped before this earnings report. Use that gap as a prompt to compare several viewpoints before deciding how this update might shift your own expectations.
Explore 4 other AppFolio fair value estimates, including one that suggests it could be worth just $217.29.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own analysis.
- A great starting point for your AppFolio research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AppFolio. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AppFolio's overall financial health at a glance.
Looking For More Investment Ideas Beyond AppFolio?
If the setup around AppFolio has sharpened your thinking about quality, risk and price, it can be useful to line it up against a wider field using the Simply Wall St Screener.
- For investors who care most about balance sheet strength and durable fundamentals, start with this list of solid balance sheet and fundamentals (25 results) to see which businesses might handle tougher conditions more comfortably.
- If your priority is finding quality at a reasonable entry point, scan through a curated 33 high quality undervalued stocks that match strict fundamental checks.
- Income focused readers can zero in on steady cash return potential by reviewing a 8 dividend fortresses that combine higher yields with an emphasis on resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com