
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Sichuan Kelun Biotech Biopharmaceutical (SEHK:6990) Showcased Phase III ADC Data, Is It A Bargain?
Sichuan Kelun-Biotech Biopharmaceutical (SEHK:6990) just presented new clinical data for its antibody-drug conjugate sacituzumab tirumotecan to a global oncology audience, including several Phase III readouts selected for high-profile oral sessions.
The new clinical readouts arrive as Sichuan Kelun-Biotech Biopharmaceutical trades at HK$452.0, with a 1-day share price return of 3.10% and a year-to-date share price return of 12.83%. The 1-year total shareholder return is slightly negative, while the 3-year total shareholder return is a very large multiple. This suggests that long term holders have already seen substantial value created even as shorter term momentum has recently cooled.
Spot emerging oncology players moving on fresh trial data by scanning the 127 healthcare AI stocks that could sit alongside Sichuan Kelun-Biotech Biopharmaceutical in a high-conviction watchlist.Bulls point to sac-TMT’s approvals, the global MSD partnership and very large 3-year shareholder gains. Bears flag the recent share price pullback and modest 1-year decline. Which story does Sichuan Kelun-Biotech Biopharmaceutical’s current valuation actually tell?
Most Popular Narrative: 27% Undervalued
Against a last close of HK$452.0, the most followed narrative pegs Sichuan Kelun-Biotech Biopharmaceutical’s fair value at HK$618.43, using a 7.3% discount rate and long range earnings assumptions to bridge the gap.
Kelun Biotech is leaning heavily on long duration oncology trends such as wider ADC use, combination regimens with immunotherapies and large global Phase III programs with partners like MSD. Together, these create meaningful optionality for new indications, overseas launches and royalty streams that could shift earnings and market expectations away from a flat share price if more products reach approval and commercialization.
See why 1 investors see Sichuan Kelun-Biotech Biopharmaceutical as 27% undervalued.
Result: Fair Value of HK$618.43 (UNDERVALUED)
Still, the analysts’ story for Sichuan Kelun-Biotech Biopharmaceutical can break if Phase III trials disappoint or key partners slow milestones and royalty payments.
Find out about the key risks to this Sichuan Kelun-Biotech Biopharmaceutical narrative.
Another View: What The P/S Ratio Signals For Sichuan Kelun-Biotech Biopharmaceutical
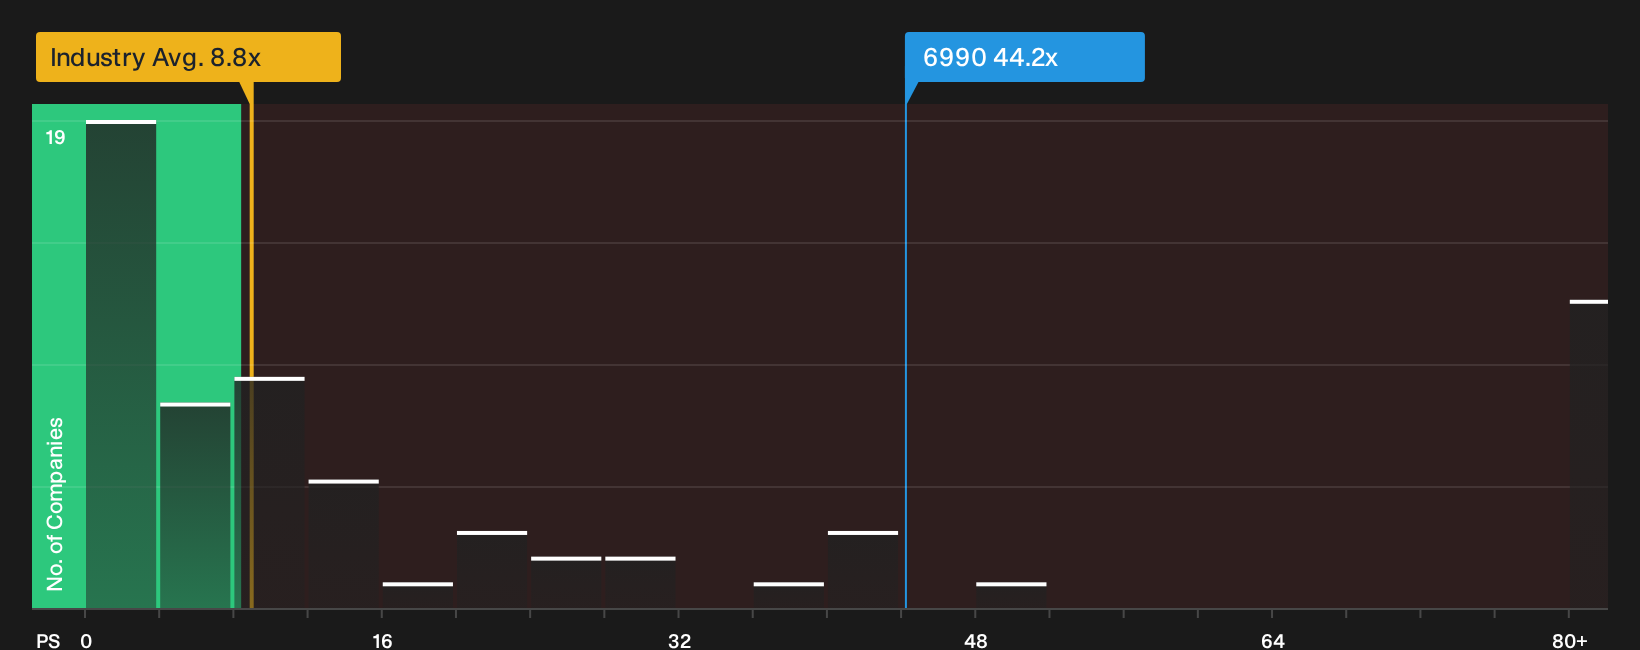
The DCF story is one thing. On a simple P/S yardstick, Sichuan Kelun-Biotech Biopharmaceutical trades on 44.2x sales, while the Hong Kong biotech group sits around 8.9x and the fair ratio is 15.2x. That is a wide gap. Is it a premium that future execution can actually justify?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Sichuan Kelun-Biotech Biopharmaceutical’s valuation and expectations only matter if you pressure test them yourself and decide where you stand. Act while the data and sentiment are fresh by reviewing the 4 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Sichuan Kelun-Biotech Biopharmaceutical?
If Sichuan Kelun-Biotech Biopharmaceutical is already on your radar, rounding out your watchlist with a few different angles can sharpen your decision making and keep you ahead.
- Target potential mispricings by scanning a curated pool of stocks that trade below their assessed fair value using the 191 high quality undervalued stocks.
- Build resilience into your portfolio by reviewing a list of solid balance sheet and fundamentals (203 results) that can help anchor returns when conditions become more volatile.
- Get in early on future contenders by surveying 618 high quality undiscovered gems that pair strong fundamentals with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com