
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 AI Infrastructure Stocks For Data Center Hardware Demand
Inflation pressures are creeping back through energy bills, freight costs, and sticky core prices, and that mix is colliding with an AI-driven surge in data center demand. Some stocks are feeling the squeeze, while others are finding fresh momentum as chips and hardware stay in focus. This article walks through three screened semiconductor and data center hardware suppliers that appear particularly exposed to this story, for better or worse.
These three stocks are only a starting cut, and the full screen surfaced 29 more large semiconductor and data center hardware suppliers with equally compelling stories that do not fit into a short article.
To go deeper on this theme, head straight into the Semiconductor and Data Center Hardware Suppliers screener to identify, filter, and analyze the highest conviction plays in one place.
ISU Petasys (KOSE:A007660)
Overview: ISU Petasys manufactures high complexity printed circuit boards for servers, storage, networking equipment, supercomputers, aerospace, and automotive radar systems.
Operations: The group generates virtually all of its ₩1.31 trillion revenue from the PCB sector, selling mainly into Thailand, other regions, Taiwan, and Mexico.
Market Cap: ₩7.30 trillion
ISU Petasys supplies advanced PCBs for servers, storage, and high performance computing equipment used in data centers. Analysts’ rapid earnings growth forecasts and commentary on a sizable discount to estimated fair value may give data center focused investors something to study closely, particularly if a single unseen pressure on its funding model and cash conversion starts to emerge.
If that funding and cash conversion pressure matters to you, review the 3 key rewards and 2 important warning signs (1 is major!) to see what might be accelerating beneath the headline story.

Lingyi iTech (Guangdong) (SZSE:002600)
Overview: Lingyi iTech (Guangdong) supplies thermal management, power, structural and liquid cooling hardware for AI devices, servers, robots and other electronics.
Operations: Ai Terminal products contribute about CN¥44.4b of revenue, Cars and Low-altitude Economy CN¥5.3b, with roughly CN¥37.3b from overseas customers.
Market Cap: CN¥75.99b
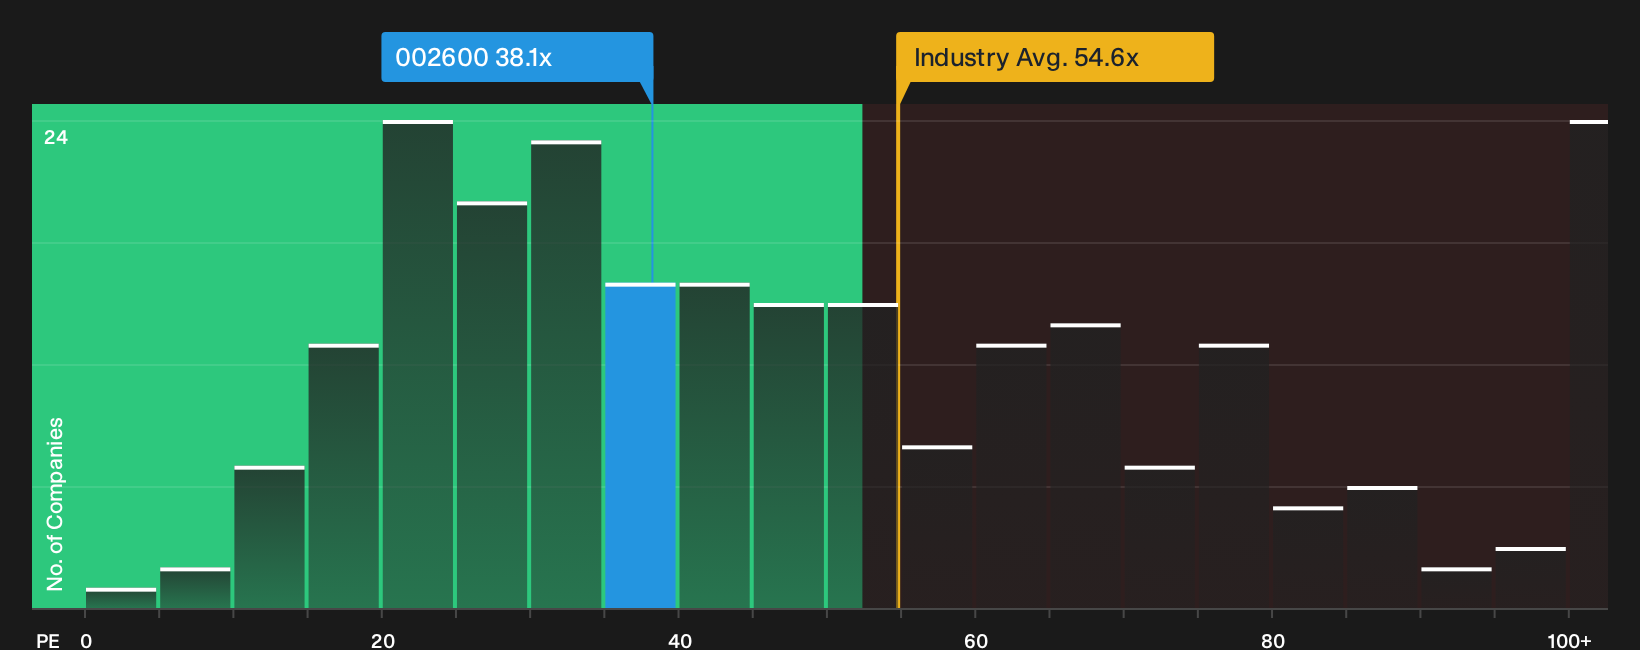
Lingyi iTech (Guangdong) participates in the same AI hardware tailwind as chipmakers by selling heat dissipation, liquid cooling and structural components into servers, robots and AI devices. Its 38.1x P/E sits below Chinese electronic peers, while its exposure to data-center related demand raises the question of how inflation driven input costs may affect future margins.
Those margin questions are exactly why the analysis report for Lingyi iTech (Guangdong) could be worth your time, as it presents the full thesis on how Lingyi iTech (Guangdong) might handle cost pressures.
Tripod Technology (TWSE:3044)
Overview: Tripod Technology produces a wide range of printed circuit boards used in servers, data center hardware, memory modules, and consumer electronics.
Operations: Tripod Technology generates almost all of its NT$84.2b revenue from printed circuit boards, with only NT$250m from other departments.
Market Cap: NT$307.0b
Tripod Technology provides direct exposure to the printed circuit boards that sit inside servers and AI data center hardware. Earnings and revenue were recently reported at strong levels for 2026. The combination of high ROE, a modest P/E against peers, and improving profitability may be appealing, although one unresolved pressure on its cash-funded dividend policy remains a key consideration.
That unresolved pressure is exactly why the 4 key rewards and 2 important warning signs (1 is major!) could sharpen your view of how Tripod Technology’s dividend, profitability and data center exposure really interact.

Seeking Fresh Alternatives Before They Fly
Momentum shifts fast and the earliest moves often come from corners the crowd has not fully watched yet. Scan these fresh ideas before the window drops and get in early.
- Hunt for robust income plays anchored by reliable cash generation as you run through the 214 dividend fortresses that aim to keep payouts flowing even when sentiment swings.
- Target resilient operators insulated from wild drawdowns by filtering the 233 resilient stocks with low risk scores that score well on balance sheet strength and business stability before others catch on.
- Track the infrastructure behind AI momentum by reviewing the curated 55 AI infrastructure stocks that connect directly to the servers, data pipes, and power systems doing the heavy lifting.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com