
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Iron Mountain (IRM) Fully Priced Following Its November 5 Earnings Update?
Iron Mountain (IRM) is heading into a key information moment, with third quarter 2026 results due before the market opens on Thursday, November 5. The company will also hold an investor conference call on the same day.
After a softer patch that saw the 90-day share price return decline 9.13%, Iron Mountain is still coming into this earnings update with strong momentum, supported by a 35.16% year-to-date share price return and a 5-year total shareholder return of 195.57%.
Look beyond Iron Mountain’s earnings moment and explore other potential breakouts in real estate and infrastructure with a curated shortlist of 55 AI infrastructure stocks.
Iron Mountain appears to be a solid operator with long relationships, global reach and expanding digital services. However, the share price has already risen significantly this year. Is the current valuation still providing enough potential return for that level of quality?
Most Popular Narrative: 22% Undervalued
On the most followed view, Iron Mountain’s fair value sits at $144.91, comfortably above the recent $112.51 close. This view places more weight on long-term cash generation than on the latest share price move.
Use of cash flow from the physical records management business, which management describes as highly cash generative with stable to slightly rising volumes and consistent pricing, together with net lease adjusted leverage of about 4.8x and a US$1.5b senior notes issue maturing in 2035, underpins continued funding of growth projects in data centers, ALM and digital without relying on equity issuance, which can support future AFFO per share and dividend capacity.
See why 48 investors see Iron Mountain as 22% undervalued.
Result: Fair Value of $144.91 (UNDERVALUED)
Still, the Iron Mountain story can break if physical records storage weakens faster than expected, or if data center build outs encounter power, equipment, or leasing delays.
Find out about the key risks to this Iron Mountain narrative.
Another View: What Iron Mountain’s P/E Is Telling You
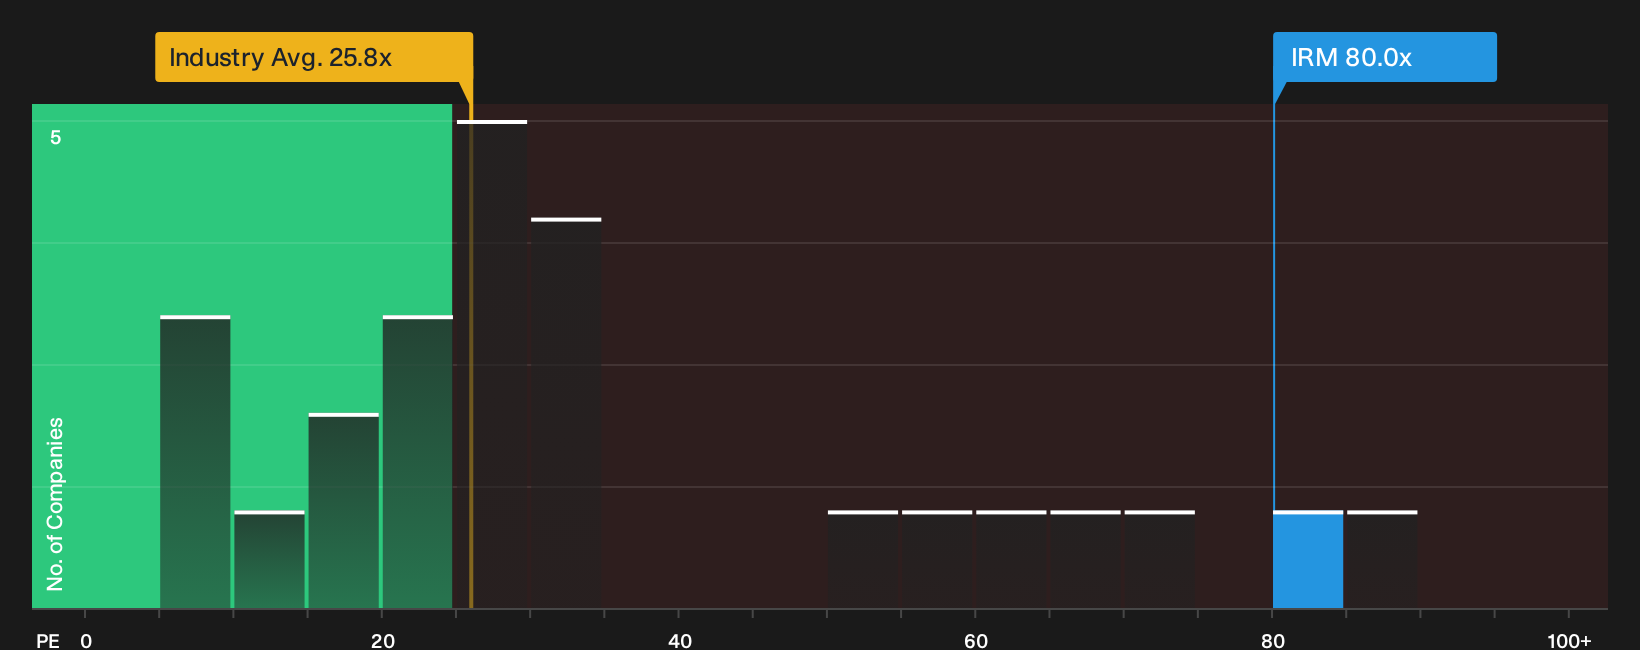
The first narrative leans on cash flows and long contracts to argue Iron Mountain is 22% undervalued. A simple earnings multiple paints a very different picture. The stock trades on a P/E of 80x, while the fair ratio sits at 41.8x and the Specialized REITs industry averages 25.4x. Peer companies are closer to 17.7x. That gap suggests investors are already paying a heavy premium for Iron Mountain’s story, so the real question is how comfortable you are owning a business that may already be priced for a lot to go right.
To see how that premium lines up against the underlying numbers and sector benchmarks, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Iron Mountain story. Use the data, weigh both sides quickly and ground your own view with 4 key rewards and 4 important warning signs
Looking for more investment ideas beyond Iron Mountain?
Iron Mountain might be your starting point, but you do not want to stop there. Broader idea flow often separates prepared investors from everyone else.
- Target resilient cash generators backed by strong finances and filter for a list of solid balance sheet and fundamentals (25 results) that can better handle tough conditions.
- Hunt for mispriced quality and scan the 33 high quality undervalued stocks that combine fundamentals with potential upside before the crowd pays attention.
- Dial back portfolio stress and focus on stability by reviewing a 32 resilient stocks with low risk scores that aims to limit nasty surprises.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com