
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Reece (ASX:REH) Gains On Digital And US Growth, Is The Upside Already Priced In?
Reece (ASX:REH) has drawn fresh attention after a strong share rally this year, as investors react to improved net income, firmer margins, and ongoing digital and US expansion efforts.
The recent move to A$17.35 follows a year-to-date share price return of 30.06%, with a 6.38% 3 month gain that suggests momentum has been building as investors focus on Reece's digital push and US footprint, supported by a 46.17% 1 year total shareholder return.
Scan how Reece compares to other potential breakouts by lining it up against 4 high quality undervalued stocks with solid cash flows and balance sheets already on investors' radar.
After a 46.17% 1 year return and a price now above some analyst targets, the question is straightforward: Is Reece’s real opportunity still ahead, or has most of the upside already played out in the share price?
Most Popular Narrative: 16.6% Undervalued
On the most followed narrative, Reece’s fair value of A$20.80 sits above the last close at A$17.35, which puts the focus firmly on whether its US network and digital investments can translate into higher quality earnings rather than just more branches.
The decision to keep investing in network, people and digital while holding capex close to 2 to 3% of sales leaves headroom for operating leverage if volumes improve, which could translate into a more pronounced recovery in EBIT and free cash flow than current models assume.
See why 6 investors see Reece as 17% undervalued.
Result: Fair Value of A$20.80 (UNDERVALUED)
Still, the bullish Reece story can crack if US branch rollout keeps adding immature sites in a soft residential market and if operating costs stay structurally higher.
Find out about the key risks to this Reece narrative.
Another View: Reece Looks Expensive On Earnings
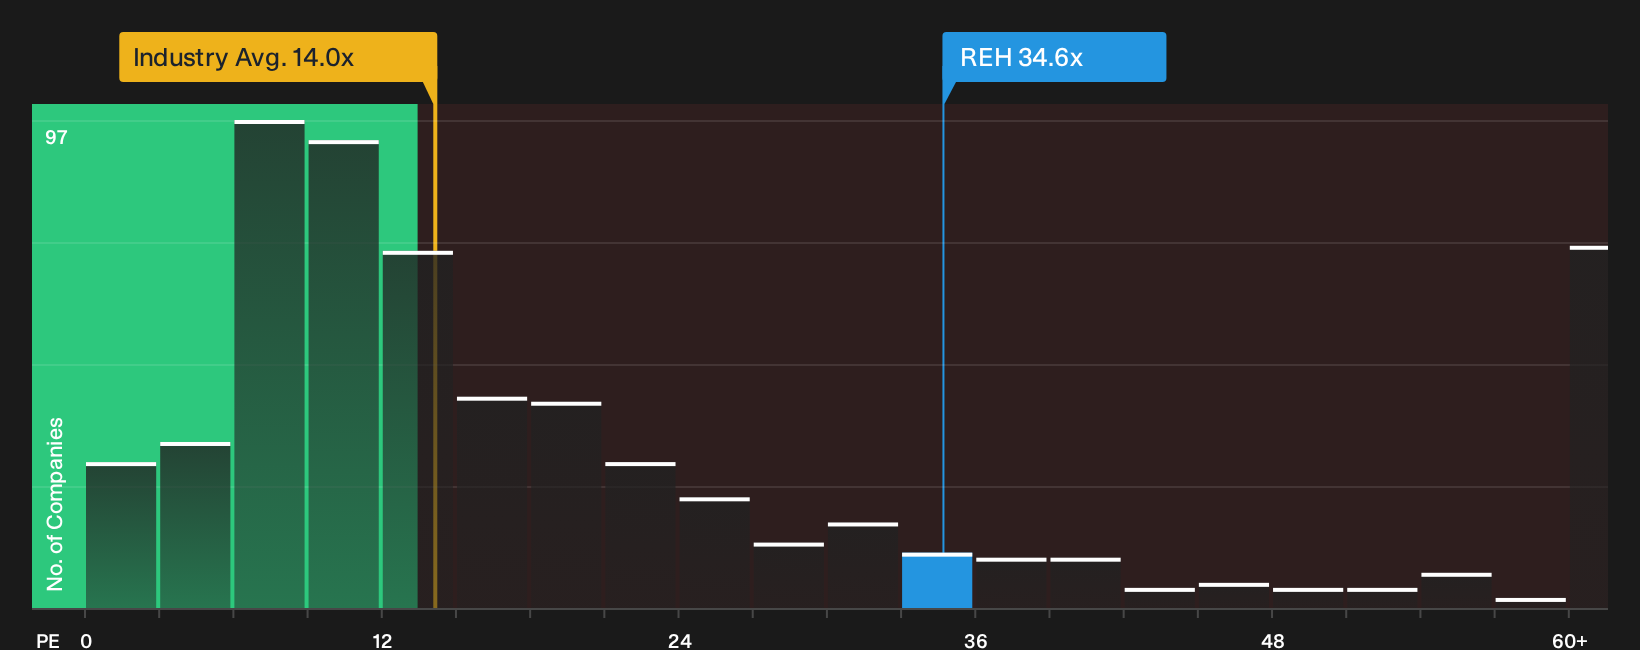
That A$20.80 fair value hinges on bullish analyst assumptions. On simple earnings maths, Reece trades on a P/E of 34.6x, which is far richer than the Global Trade Distributors average at 14.1x, its peer group near 18.1x, and even its own fair ratio of 27.9x.
This gap implies investors are already paying a premium for execution on US growth and digital delivery rather than getting in at a clear discount. The question is whether you see that premium as justified upside potential or valuation risk if the story takes longer to play out.
For a closer look at how this earnings multiple stacks up against the rest of the market, and what that might mean for future re rating risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the split views on Reece leave you unsure, that is the cue to stress test the numbers yourself and move quickly from headline to conviction. A useful place to start is by weighing the upside signals picked up in our reward checks through 1 key reward.
Looking for more investment ideas beyond Reece?
If Reece has sharpened your focus, use the same energy to scan wider opportunities where price, quality and income all pull in the same direction.
- Target potential upside by lining up Reece against 15 high quality undiscovered gems that may not yet be crowded with institutional money.
- Strengthen portfolio resilience by comparing your current holdings with a list of solid balance sheet and fundamentals (12 results) that already screens for financial durability.
- Boost income potential by weighing Reece alongside 4 dividend fortresses that combine higher yields with an emphasis on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com