
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Rubicon Research And 2 Indian Insider Stocks To Watch
Oil just pushed past US$100 after fresh disruptions near the Strait of Hormuz, and that kind of energy shock often separates fragile businesses from those that can adapt. Indian growth companies where insiders hold big stakes can be especially interesting when costs and policies feel unpredictable. This article walks through three such high-conviction stocks from our screener so you can judge which stories deserve a closer look.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where insiders are heavily invested alongside you. However, if you want the names that matter most, these 40 high growth high conviction stocks are the strongest companies we've found.
Rubicon Research (NSEI:RUBICON)
Rubicon Research is a specialty pharma player that leans on its RubiReten and RubiSRL drug delivery platforms to create higher value formulations, with all of its ₹19,358 million revenue coming from pharmaceutical products and related services and a market cap around ₹249.7b.
Rubicon Research fits this fast growth, high insider ownership theme because its proprietary platforms are not just science projects. They are the engine management is using to push into more complex, higher value formulations and to back that ambition with real capital on the ground.
"Expansion of US manufacturing capacity through the New Jersey facility and preparation of the Pithampur site in India is expected to support a higher own manufacturing share and can support gross margin resilience and operating EBITDA over time."
The real swing factor is how one pressure on its premium product mix ultimately feeds through to pricing power and long term profitability.
That pricing power question is exactly what the full narrative for Rubicon Research unpacks, highlighting where capacity, mix and insider alignment could be quietly accelerating or stalling the edge of Rubicon Research.

Atlanta Electricals (NSEI:ATLANTAELE)
Atlanta Electricals manufactures power and special duty transformers used in transmission, solar and infrastructure projects, tying it to India’s grid buildout. It generates about ₹20,027 million from transformer manufacturing within India and carries a market value near ₹130.4b.
Atlanta Electricals is linked to the fast growth, high insider ownership theme, with transformer manufacturing positioned within India’s power and solar expansion. Current projections indicate earnings growth of 29.35% a year on 23.2% revenue growth. A P/E of 59.9x and significant external borrowing place greater focus on how this transformer cycle develops.
That mix of growth and leverage makes it even more important to read the 2 key rewards and 1 important warning sign before this transformer cycle surprises you for better or worse.

Bajel Projects (NSEI:BAJEL)
Bajel Projects focuses on EPC work for extra high voltage transmission lines and turnkey power transmission and distribution projects, which neatly matches the growth and insider ownership theme. It generated about ₹27,508 million from power transmission and distribution and carries a market cap near ₹19.4b.
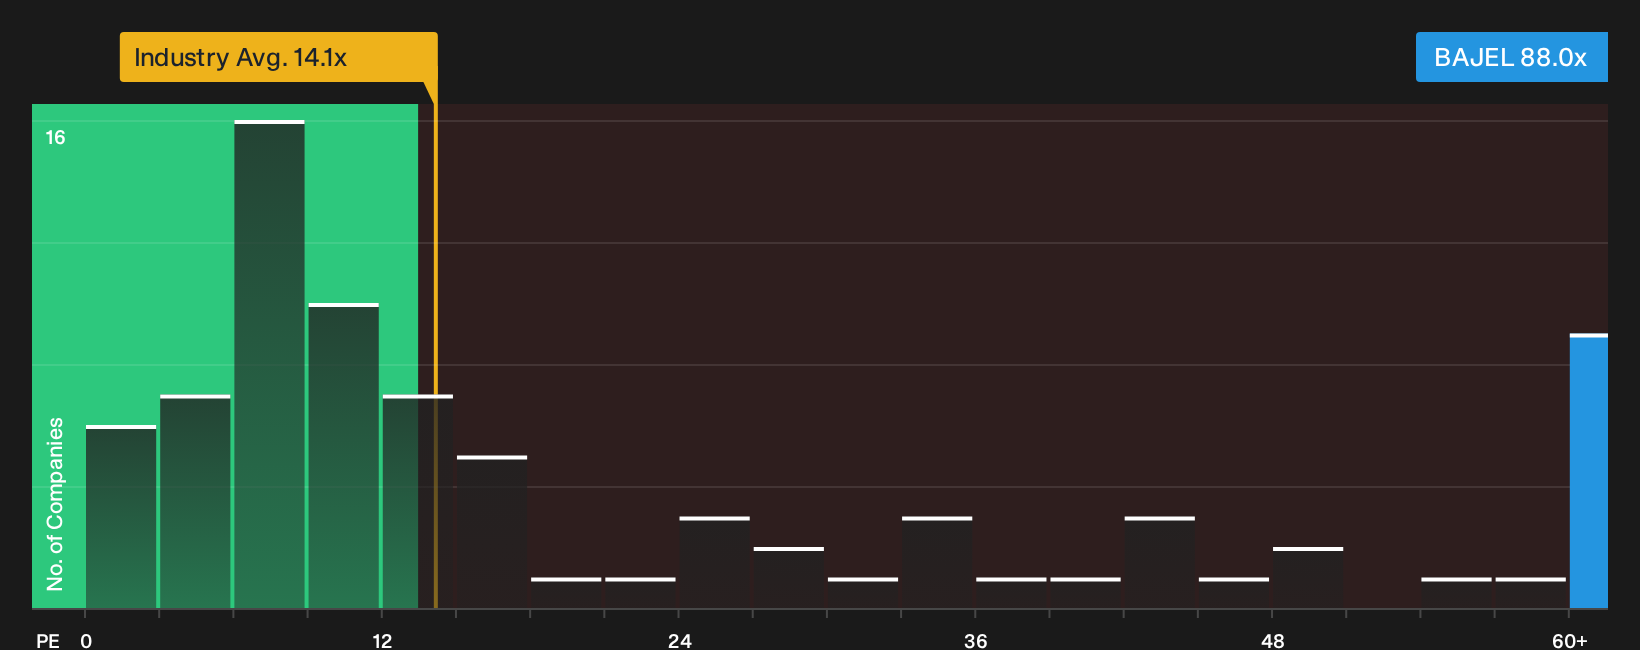
Bajel Projects has grown earnings about 71% in the past year. Analysts expect around 57.7% annual profit growth and 27% revenue expansion, yet the stock trades on a rich 88x P/E. That mix of rapid grid EPC order wins and stretched valuation places significant attention on how pressure on future execution and margins resolves.
That kind of execution test is exactly where the 2 key rewards and 1 important warning sign can show whether Bajel Projects’ rich multiple is masking resilience or stretching the story too far.
Curious About High Conviction Alternatives
Fresh ideas move first, and when momentum picks up, attractive entry points can disappear. Look under the radar now, before the crowd, and consider acting sooner rather than later.
- Identify stronger balance sheets before they attract broad attention and compare how each business holds up using the list of solid balance sheet and fundamentals (203 results).
- Explore early-stage AI momentum while it is still less widely followed and review the 38 profitable AI stocks that aren't just burning cash that are already generating real profits.
- Evaluate opportunities related to potential future power buildouts and assess grids, turbines, and more through the curated 41 power grid technology and infrastructure stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com