
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What’s Going On With Walker & Dunlop (WD)?
Recent financing deals put Walker & Dunlop’s capital markets engine in focus
Walker & Dunlop (WD) has been busy arranging large real estate loans, including fresh bridge financing for high profile mixed-use properties. That deal activity gives investors a concrete look at how the capital markets segment operates.
Despite arranging these high profile financings and scheduling third quarter 2026 results for early November, Walker & Dunlop’s share price has retreated, with the stock down 16.8% on a 30 day share price basis and the 1 year total shareholder return declining 57.5%. This signals fading momentum as investors reassess both growth potential and risk around its capital markets exposure.
Contrast Walker & Dunlop’s recent bridge and agency financings with other real estate lenders by scanning a curated set of list of solid balance sheet and fundamentals (25 results).
Bulls view Walker & Dunlop’s deal pipeline and recent earnings growth as undervalued, while bears focus on the steep share price decline. Which perspective is better reflected in the current valuation?
Most Popular Narrative: 43% Undervalued
Against a last close of $32.66, the most followed narrative anchors Walker & Dunlop’s fair value at $57, which frames the recent share price slump in a very different light for anyone focused on longer term cash flows rather than short term sentiment.
Ongoing refinancing and construction activity in a higher rate setting, including recent large multifamily, mixed use, office and workforce housing deals in Miami, Manhattan, Jersey City and other markets, keeps Walker & Dunlop well positioned to generate fee income from a sustained recapitalization cycle that can support revenue and earnings.
See why 1 investors see Walker & Dunlop as 43% undervalued.
Result: Fair Value of $57 (UNDERVALUED)
Still, the Walker & Dunlop story can break if high interest costs keep transaction volumes muted or if underwriting missteps on complex projects erode profitability.
Find out about the key risks to this Walker & Dunlop narrative.
Another View: Walker & Dunlop Looks Expensive On Earnings
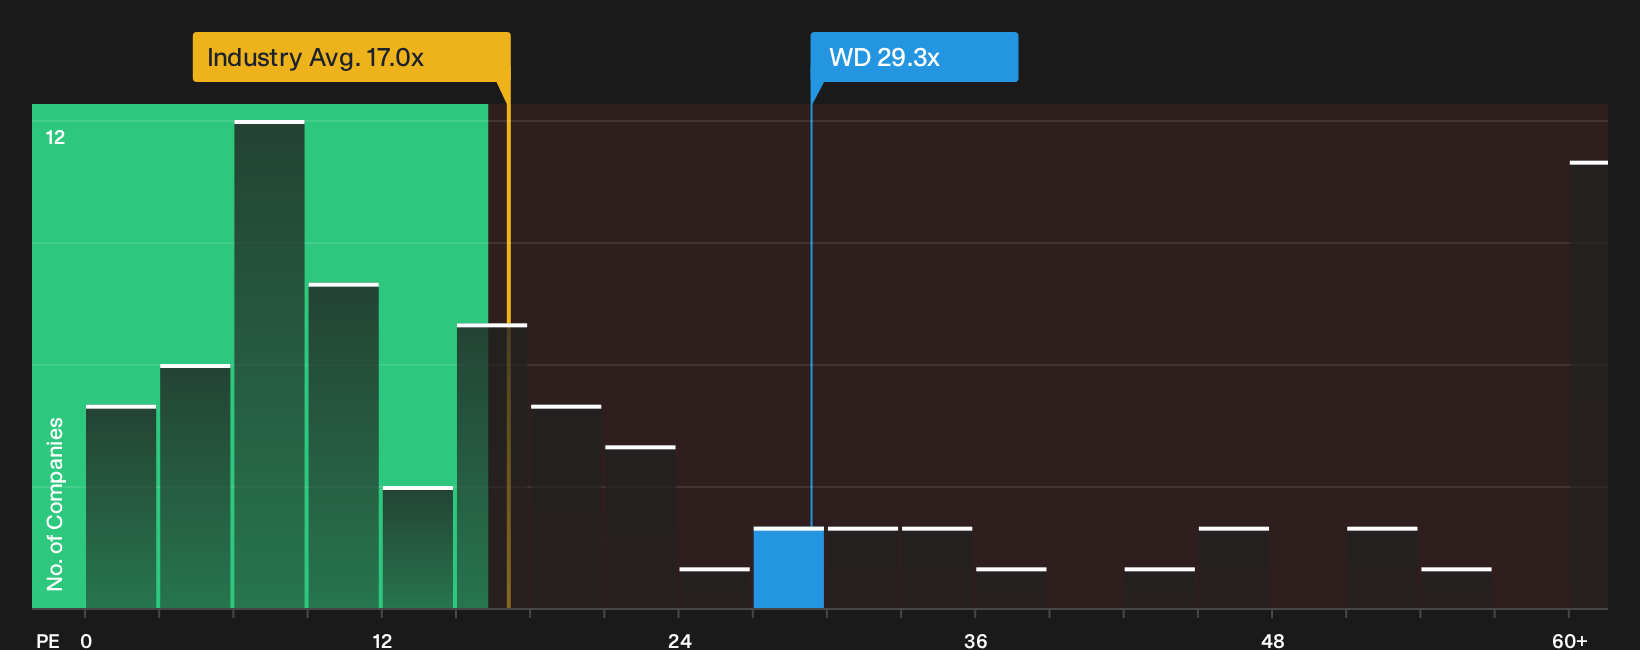
The 43% undervalued narrative leans heavily on future cash flows. A quick check of today’s P/E points in the opposite direction. Walker & Dunlop trades at 29.3x earnings, compared with 17.2x for the US Diversified Financial industry, 10.1x for peers, and a fair ratio of 18.8x.
That is a wide gap. It suggests the market is already paying a premium multiple even after the share price slide, which raises a simple question for investors: Is the current optimism about future profit recovery strong enough to justify paying above both peers and the fair ratio today?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Walker & Dunlop feels split, treat it as a prompt to move quickly and stress test your own thesis using the 2 key rewards and 4 important warning signs.
Looking for more Walker & Dunlop style investment ideas?
If Walker & Dunlop’s mixed signals have sharpened your thinking, do not stop here. Broaden your watchlist with fresh ideas sourced directly from focused screeners.
- Target resilient balance sheets and consistent fundamentals by reviewing the list of solid balance sheet and fundamentals (25 results).
- Hunt for quality at sensible prices with the 33 high quality undervalued stocks.
- Prioritise stability and cash returns by scanning the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com