
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Taiheiyo Cement (TSE:5233) Fairly Valued Following Its ¥130b Bond Shelf Filing?
Taiheiyo Cement (TSE:5233) has filed a shelf registration in Japan to issue up to ¥130b in bonds, putting its funding plans and balance sheet choices in sharper focus for shareholders.
The bond shelf lands at a time when Taiheiyo Cement’s share price has climbed to ¥4,210, supported by a 7.37% 90-day share price return and a 16.88% 1-year total shareholder return. This suggests investors have been rewarding the story while recent momentum has cooled slightly.
Scan how Taiheiyo Cement’s funding move compares with other balance sheet focused opportunities using our hand picked list of solid balance sheet and fundamentals (21 results).
Taiheiyo Cement’s fresh ¥130b bond headroom could signal management leaning into a solid operating base, or it might mark a sentiment driven stretch. The valuation now has to show which story fits.
Price-to-Earnings of 17x: Is it justified?
The market is currently paying a P/E of 17x for Taiheiyo Cement at a share price of ¥4,210, which sits above both industry and peer averages and points to investors paying more for its earnings profile than for many alternatives.
The P/E ratio compares what you pay per share with the profit generated per share. For a mature materials group like Taiheiyo Cement, it is a quick way to see how heavily the market is charging for each yen of current earnings.
Against the JP Basic Materials industry on 9.9x and a peer average of 10.5x, the 17x tag is materially higher. This indicates the stock is being valued more expensively than many sector rivals on today’s profits. The fair P/E estimate of 18.6x suggests a level the market could gravitate toward that is even higher than the current multiple, so the present premium aligns more closely with that fair ratio than with sector benchmarks.
Explore the SWS fair ratio for Taiheiyo Cement.
Result: Price-to-Earnings of 17x (OVERVALUED)
Still, Taiheiyo Cement depends heavily on cement demand and construction activity, so weaker project pipelines or pricing pressure could quickly challenge that premium multiple.
Find out about the key risks to this Taiheiyo Cement narrative.
Another view of Taiheiyo Cement’s value
The P/E premium paints Taiheiyo Cement as expensive, yet the SWS DCF model points to a share value of ¥4,309.75 against a market price of ¥4,210. That 2.3% gap suggests a slight undervaluation. So which story do you trust more: earnings multiples or cash flows?
Look into how the SWS DCF model arrives at its fair value.
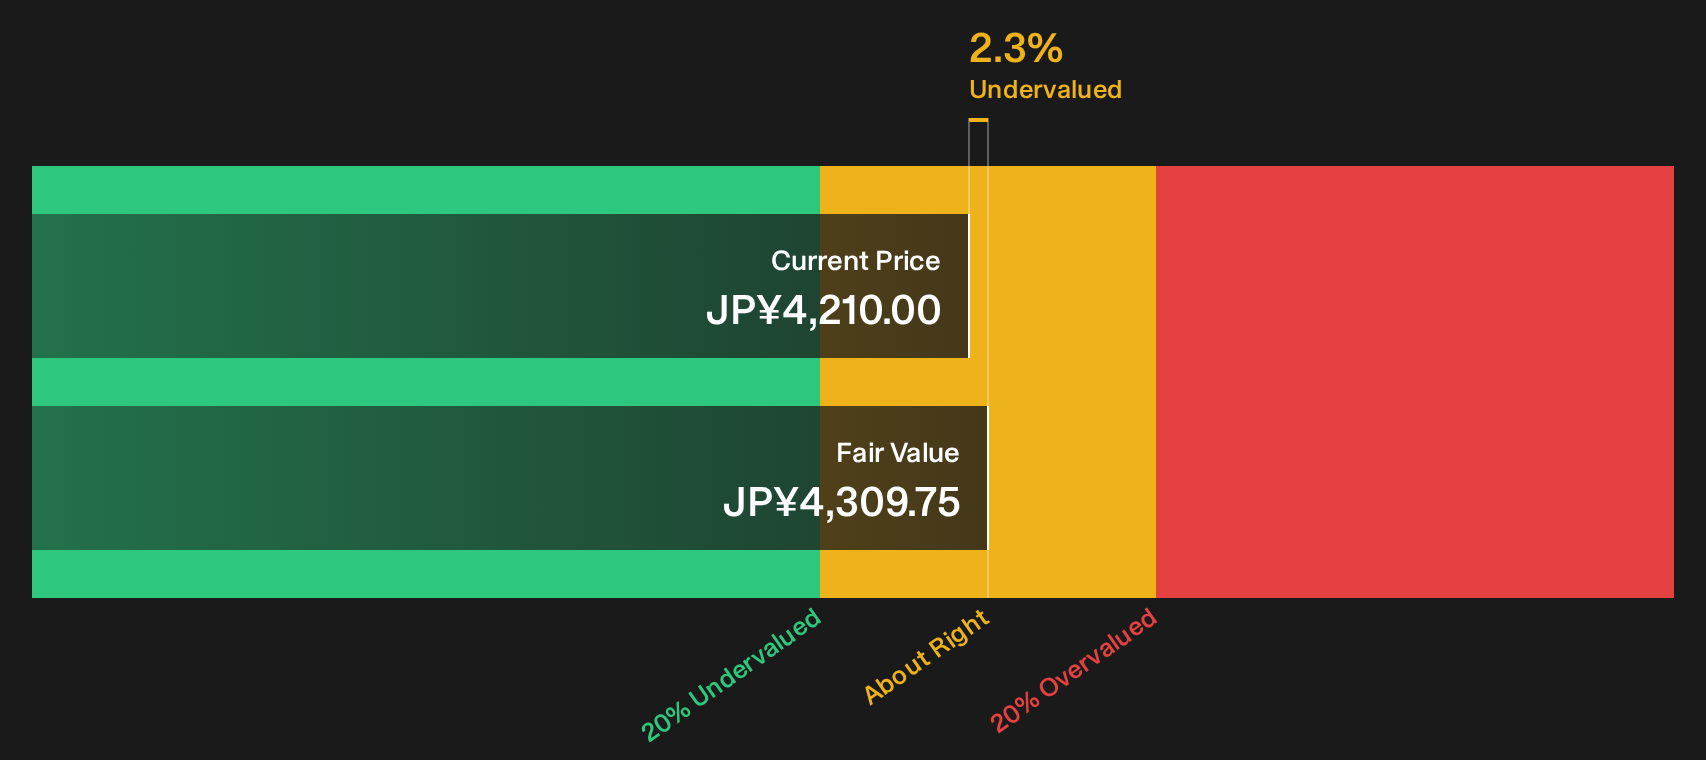
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Taiheiyo Cement for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Taiheiyo Cement’s valuation and bond capacity make this a moment to move quickly and test the story against your own framework and risk tolerance, starting with the balance of 2 key rewards and 4 important warning signs
Looking for more Taiheiyo Cement sized ideas?
If Taiheiyo Cement has sharpened your focus on valuation and risk, use this momentum to scout other opportunities before they move without you.
- Target resilient balance sheets first and scan companies with a list of solid balance sheet and fundamentals (21 results) that may better fit your risk comfort.
- Hunt for quality at a discount by reviewing 14 high quality undervalued stocks that combine robust fundamentals with more modest pricing.
- Strengthen your income lineup and check out 29 dividend fortresses that aim to deliver reliable cash returns alongside capital exposure.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com