
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
CSSC Offshore & Marine Engineering (Group) (SEHK:317) Could Be 29% Undervalued On 2026 Profit Guidance
CSSC Offshore & Marine Engineering (Group) (SEHK:317) drew attention after issuing earnings guidance for the first three quarters of 2026, indicating a significantly higher estimated net profit compared with the same period last year.
The earnings guidance lands after a volatile stretch for CSSC Offshore & Marine Engineering (Group), with the share price at HK$14.0, a 1-day share price return of 3.70%, a 30-day share price return that is slightly down, and a 90-day share price return of 26.93%.
Over a longer horizon, momentum has been building, with total shareholder returns of 70.63% over three years and 108.88% over five years, even though the 1-year total shareholder return is slightly down by 1.82%.
Scan beyond CSSC Offshore & Marine Engineering (Group) and compare this earnings guidance story with a curated 191 high quality undervalued stocks that also pairs solid balance sheets with meaningful cash generation potential.
Bulls point to CSSC Offshore & Marine Engineering (Group)'s upbeat 2026 profit guidance and strong multi year returns. Bears focus on the recent share price wobble. Which side does the current valuation actually support?
Price-to-Earnings of 12.8x: Is it justified?
On the latest numbers, CSSC Offshore & Marine Engineering (Group) trades on a P/E of 12.8x, which screens as good value against an estimated fair P/E of 22.8x, even though it sits above both the Hong Kong Machinery sector and its peer group averages.
The P/E ratio links the share price to earnings per share, so it gives a quick sense of how much investors are paying for each unit of profit. For a capital goods business with sizeable marine and defense operations, earnings tend to be cyclical and project driven, so a single year of strong profit does not always justify a very high multiple on its own.
Here, the picture is mixed. The stock is described as expensive relative to the Hong Kong Machinery industry average P/E of 11.1x and also pricier than the peer average of 9.4x, which suggests the market is paying a premium versus near neighbours. At the same time, a fair P/E estimate of 22.8x implies the current 12.8x level sits well below where the valuation could migrate if earnings quality and growth expectations hold up.
Explore the SWS fair ratio for CSSC Offshore & Marine Engineering (Group).
Result: Price-to-Earnings of 12.8x (UNDERVALUED)
Still, the recent 1-year return that is slightly down and the shorter-term price softness could quickly challenge confidence if earnings guidance disappoints.
Find out about the key risks to this CSSC Offshore & Marine Engineering (Group) narrative.
Another View: What Does The DCF Say About CSSC Offshore & Marine Engineering (Group)?
The P/E work points one way, yet the SWS DCF model offers a tougher cross check. At HK$14, CSSC Offshore & Marine Engineering (Group) trades below an estimated future cash flow value of HK$19.63, which frames the shares as undervalued on this second lens. Which signal do you trust more when earnings are as cyclical as shipbuilding and defense?
Look into how the SWS DCF model arrives at its fair value.
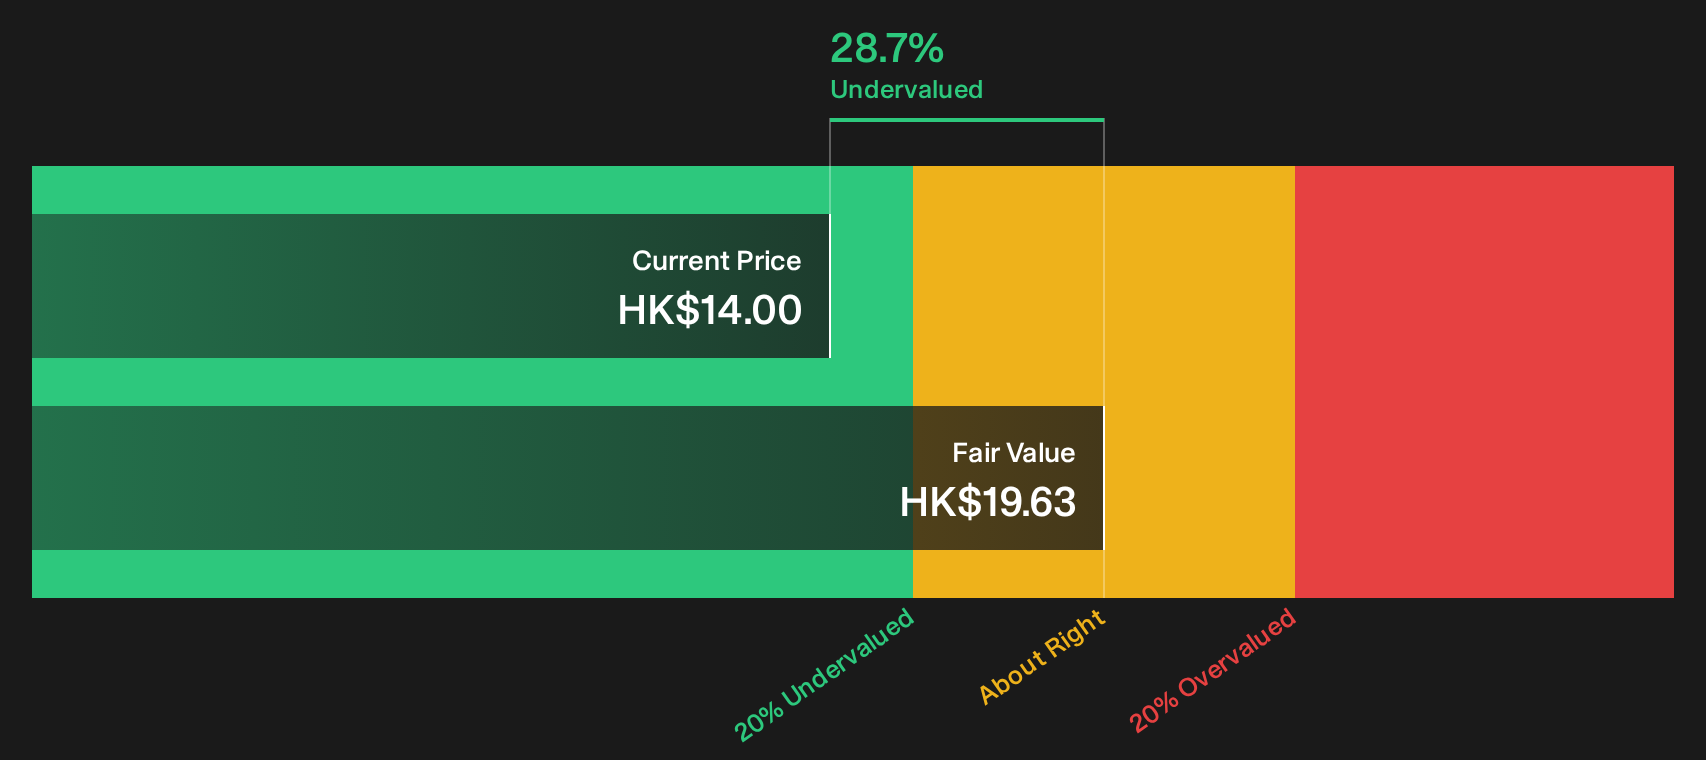
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out CSSC Offshore & Marine Engineering (Group) for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or clear opportunity, either way CSSC Offshore & Marine Engineering (Group) now has investors debating what the reward potential really looks like. Act quickly, review the full picture, and judge the upside for yourself through the 3 key rewards
Looking for more investment ideas beyond CSSC Offshore & Marine Engineering (Group)?
Do not stop with CSSC Offshore & Marine Engineering (Group). Use the Simply Wall St screener to scan fresh ideas that match your risk, income, and value preferences.
- Target resilient balance sheets by reviewing companies in the list of solid balance sheet and fundamentals (203 results) that pair financial strength with consistent fundamentals.
- Hunt for potential value opportunities through the 191 high quality undervalued stocks that highlight quality businesses trading below their estimated worth.
- Lock in income focused ideas by assessing the 213 dividend fortresses that feature higher yielding payouts alongside stability filters.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com