
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Australian Undervalued Stocks Trading Up To 37% Below Fair Value
Oil has pushed back above US$100 as conflict around key shipping routes heats up, and higher energy costs are feeding into broad inflation gauges. That kind of cost pressure often hits weaker balance sheets first, which can push solid Australian businesses to trade below what their future cash generation suggests. This article highlights three undervalued Australian stocks that may be mispriced based on discounted cash flow analysis for patient value hunters.
The three stocks below are only a sample of what surfaces when discounted cash flow models meet rising energy costs and tighter margins. The full screen highlights 8 more Australian companies where cash generation potential and current pricing tell an equally compelling story. To go beyond this snapshot and identify, compare, and analyze those extra opportunities directly, head into the Undervalued Stocks Based On Cash Flows screener
Greatland Resources (ASX:GGP)
Overview: Greatland Resources is a gold and copper miner whose Havieron project in Western Australia underpins its long term cash flow potential.
Operations: Greatland Resources generates about A$2.26b in revenue from its Telfer Havieron segment, with sales mainly into China and wider Asia.
Market Cap: A$6.69b
Greatland Resources matters to this cash flow focused screen because the Havieron project is moving from promise toward production, which makes the timing and reliability of future mine cash generation the key variable for investors to watch.
"The primary driver of Greatland’s future is the gold price. As a single asset developer moving toward production, it offers significant operational leverage to gold."
What happens when one stubborn cost line shifts could decide how much of that hoped for cash actually reaches the bottom line.
That cash conversion question is exactly what the full narrative for Greatland Resources unpacks in detail, including how cost pressures could accelerate or stall Greatland Resources from this point.
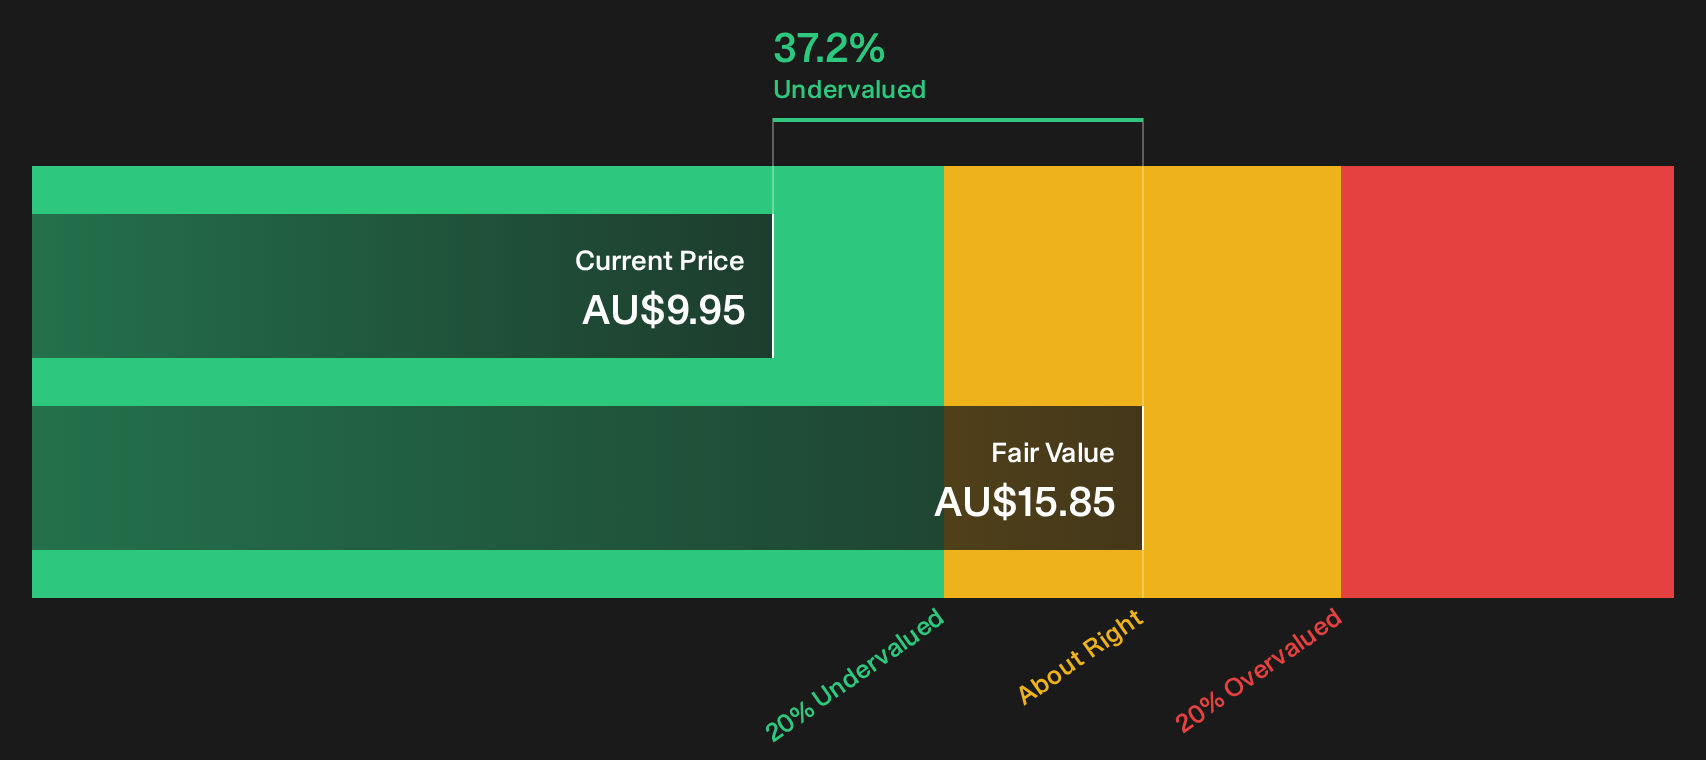
Ansell (ASX:ANN)
Overview: Ansell is a global personal protective equipment supplier, with its Healthcare gloves portfolio generating recurring cash flows tied to medical and safety use.
Operations: Ansell generates about US$1.19b from Healthcare and US$947 million from Industrial protection solutions across North America, Europe, Asia Pacific, Latin America, Australia and the Middle East.
Market Cap: A$6.41b
Ansell matters for this cash flow focused screen because its Healthcare gloves business sells essential, repeat purchase products into hospitals and workplaces, giving the valuation model a tangible, contract backed source of future cash that can be compared with where the stock currently trades.
"Ansell is well placed to capture increased structural demand in PPE, driven by tightening workplace-safety regulation, rising healthcare and hygiene standards, and accelerating industrialisation in emerging markets."
What happens if one quiet shift in how those essential products are priced filters through to earnings could materially change the cash flow story.
That quiet repricing risk is exactly what the full narrative for Ansell unpacks, revealing where accelerating PPE demand, contract structures, and input costs could be masking upside for Ansell.
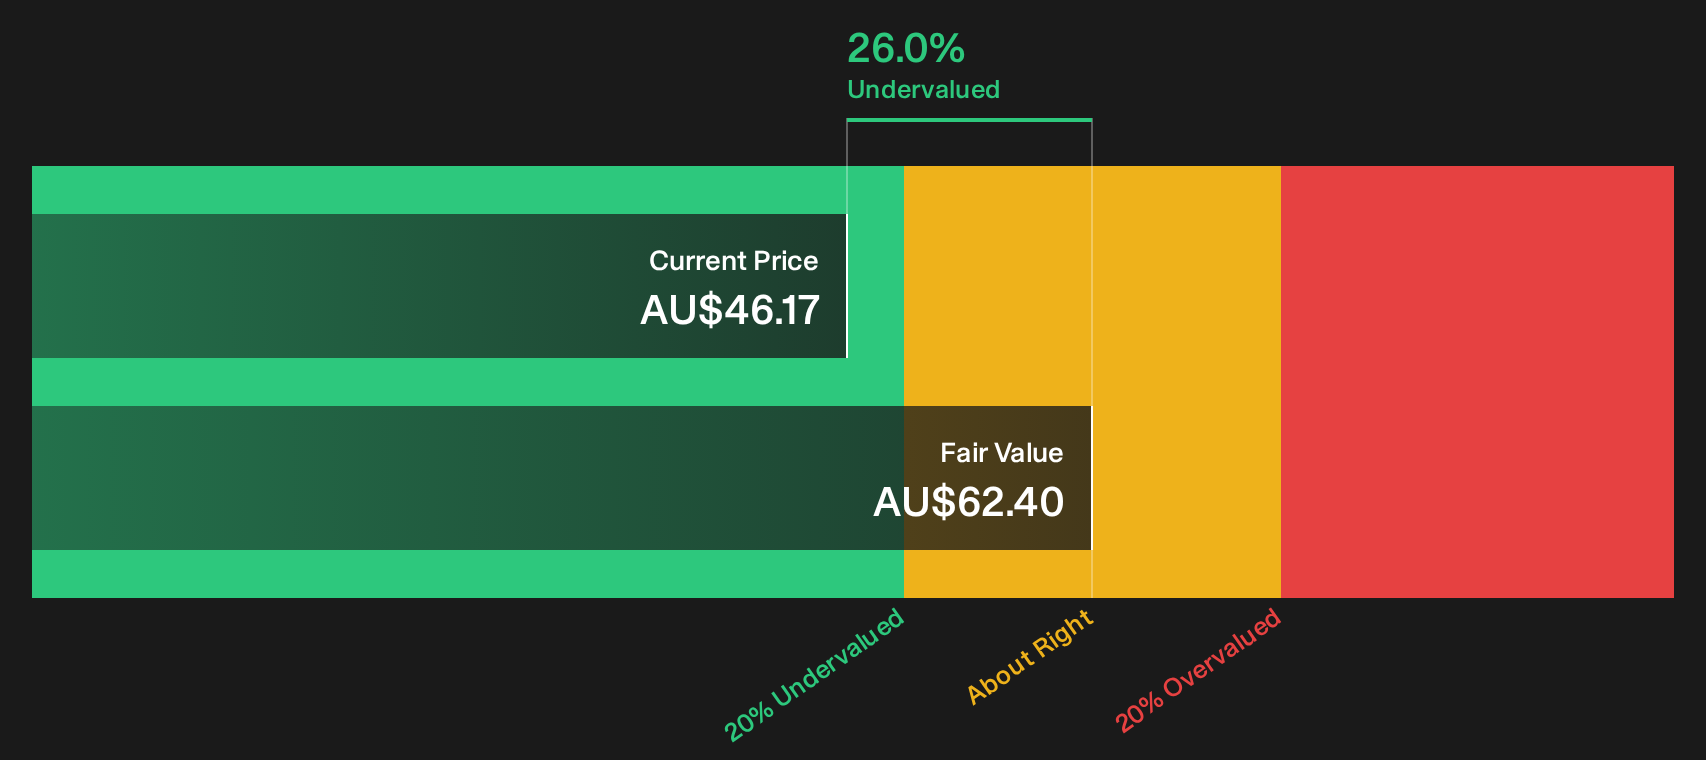
Life360 (ASX:360)
Overview: Life360 runs a subscription-led safety platform that helps families track people, pets, and possessions, generating recurring cash flows.
Operations: Life360 generates about US$573 million from Software & Programming, with revenue reported across Europe, the Middle East, Africa and other international markets.
Market Cap: A$5.0 billion
Life360 matters for this cash flow focused screen because its subscription tiers turn everyday family safety into recurring, contract-like revenue that can be mapped into long term cash flow forecasts.
"New premium services and integrated hardware (for example, unified Tile and forthcoming GPS pet tracker) deepen Life360's value proposition, increase member engagement, and create higher conversion to paid tiers; these ecosystem enhancements reinforce recurring revenue growth and could further expand net margins over time as premium offerings scale."
One quiet shift in how subscribers are retained and monetised, if it flows through to margins, could meaningfully reshape Life360’s cash flow story.
If that shift in retention is the real unlock, the full narrative for Life360 maps where Life360’s cash engine could be quietly accelerating beyond headline subscriber trends.

Seeking Alternatives Before Opportunity Flies Past
Fresh stock ideas can change quickly. Breakout stories gain momentum, quiet winners attract more attention, and mispriced assets may stop falling sooner than expected. Scan the next wave and consider your options promptly.
- Look for potentially reliable income streams by reviewing hand picked companies in the 4 dividend fortresses before yields change and the most resilient payers attract more attention.
- Identify high conviction growth stories early by checking the curated 15 high quality undiscovered gems while they may still sit under the radar and attention has not fully arrived.
- Evaluate financially strong operators in the 41 power grid technology and infrastructure stocks before more capital focuses on the same limited set of infrastructure stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com