
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Black Stone Minerals (BSM), Why Is It Getting Attention Now?
Black Stone Minerals (BSM) surprised the market with Q2 revenue of $149 million, beating analyst expectations by 40.9%, alongside stronger than expected EBITDA and EPS, yet the stock has slipped about 1.8% since.
That post earnings pullback sits against a stronger backdrop, with the share price up 11.3% year to date and a 5.0% share price return over 90 days, while total shareholder return over the past year sits at 30.6%. This hints at momentum that has cooled slightly in the very short term as expectations adjust to Black Stone Minerals’ recent beat.
Compare Black Stone Minerals' post earnings reaction with a curated group of income focused operators by scanning the 8 dividend fortresses that pair elevated yields with robust fundamentals.
Black Stone Minerals is trading about 6% below the average analyst target and at a far steeper discount to some fair value estimates. Is that gap in caution well placed after the recent rally, or an overreaction to short term hesitation?
Most Popular Narrative: 6% Undervalued
Black Stone Minerals last closed at $15.03, while the most followed valuation framework pegs fair value at $16.00. This leaves a modest gap that hinges on how future drilling and acquisitions convert into cash generation.
The expansion of the Shelby Trough and new development agreements, now covering about 500,000 gross acres with minimum drilling obligations ramping to 50 gross wells per year by 2031, continue to tie Black Stone Minerals to Gulf Coast natural gas demand and could support higher royalty revenue and distributable cash flow.
See why 18 investors see Black Stone Minerals as 6% undervalued.
Result: Fair Value of $16.00 (UNDERVALUED)
Still, the current fair value case for Black Stone Minerals rests on drilling and acquisition plans. These plans could disappoint if EBITDA margins stay under pressure or if recent Haynesville and Shelby Trough spending fails to translate into stronger cash generation.
Find out about the key risks to this Black Stone Minerals narrative.
Another View: Black Stone Minerals Through The P/E Lens
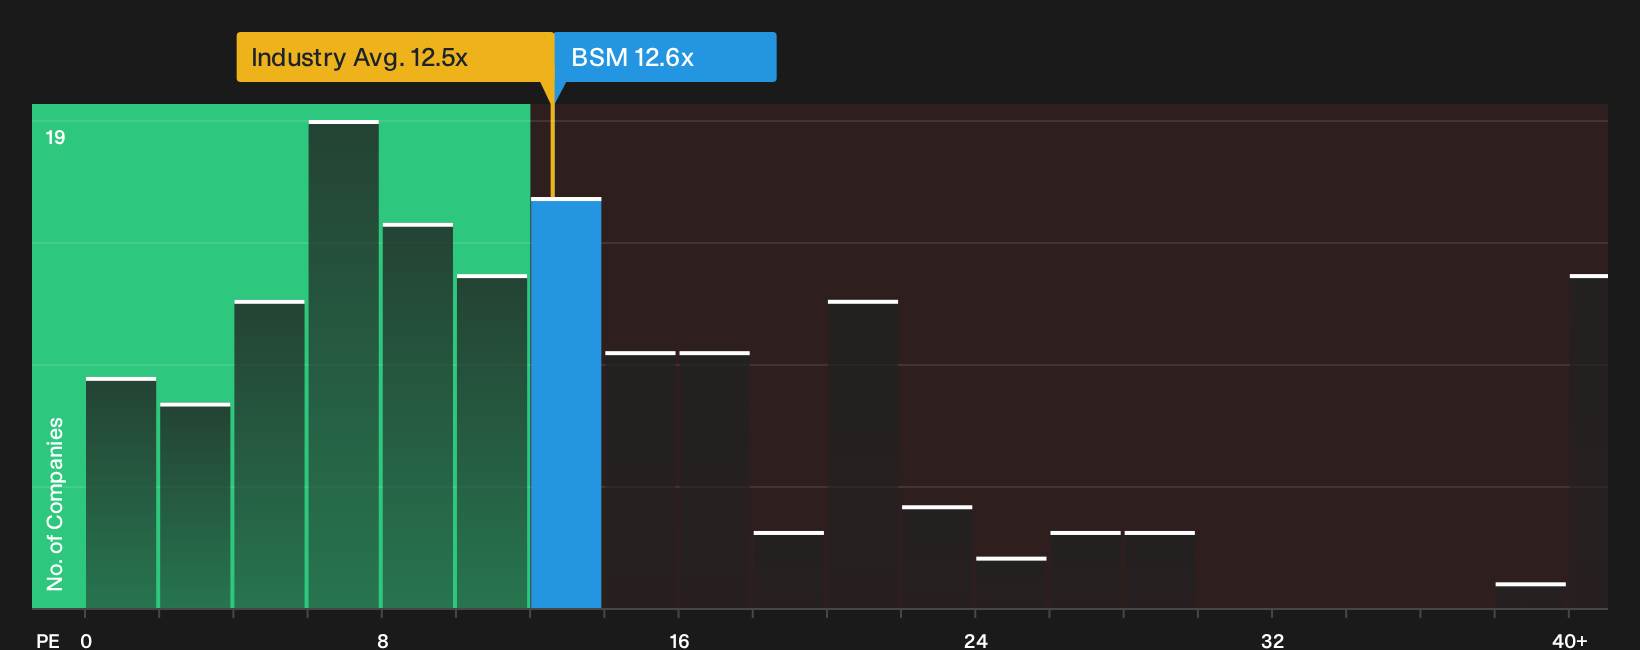
The SWS DCF model flags Black Stone Minerals as trading well below an estimated future cash flow value of $57.92 per unit, which points to a large upside gap. The P/E picture looks far more restrained. At 12.6x earnings, BSM trades slightly above both the US Oil and Gas industry on 12.3x and its peer group on 11x, while the fair ratio sits higher at 15.5x. That mix of a rich sector comparison but discounted fair ratio leaves a simple question for investors to answer: is the risk in the DCF assumptions, or in the market being too cautious on the cash flows?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Black Stone Minerals can be useful if you use them. Act quickly, pull up the full picture, and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Black Stone Minerals?
If Black Stone Minerals has sharpened your focus, do not stop here. Put a few minutes into fresh watchlist candidates and avoid leaving better fits undiscovered.
- Target potential mispricing by scanning companies that screen as high quality yet priced cautiously through the 33 high quality undervalued stocks.
- Strengthen your foundation by reviewing businesses that carry resilient finances in the list of solid balance sheet and fundamentals (25 results).
- Get ahead of the crowd by searching for future leaders hiding in plain sight with the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com