
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
HighPeak Energy (HPK) Jumped, So What Is Behind The Move?
HighPeak Energy (HPK) has jumped onto investor watchlists after analysts raised their earnings expectations, just as the company lined up a US$450m private placement of perpetual convertible preferred shares.
Recent trading shows that momentum around HighPeak Energy has been building, with a 30 day share price return of 34.05% and a year to date share price gain of 136.02% as investors respond to the upgraded earnings outlook and the US$450m preferred equity deal. That short term strength sits against a mixed longer record, including a 59.04% total shareholder return over one year but a total shareholder return decline of 38.40% over three years. This helps explain why sentiment can shift quickly as new capital and earnings expectations reshape the risk and reward balance.
Scan for other energy names showing similar earnings momentum and capital moves by running the curated 20 high quality undiscovered gems together with HighPeak Energy on your watchlist.
After a 136% year to date surge and a sizeable US$450m preferred issue now in play, the question around HighPeak Energy is simple: Does the current price still leave enough upside for the risks involved?
Most Popular Narrative: 5.5% Overvalued
Against HighPeak Energy's last close at $10.55, the most followed narrative pegs fair value at $10.00 using an 8.0% discount rate, which puts the market price slightly ahead of that benchmark and turns attention to what has to go right to justify it.
The combination of more than 2,600 drilling locations with over 100 rig years of Spraberry and Wolfcamp opportunities, including a large set of locations that target sub US$50 per barrel breakevens, together with reported unsolicited interest from larger acquirers in September 2026, underlines an inventory depth that could attract a higher takeout valuation and crystalize the value of future production and cash flow in a single transaction.
See why 6 investors see HighPeak Energy as 6% overvalued.
Result: Fair Value of $10.00 (OVERVALUED)
Still, the HighPeak Energy story can change quickly if hedge losses persist or if equity issuance under the at the market program leads to meaningful dilution.
Find out about the key risks to this HighPeak Energy narrative.
Another View: HighPeak Energy Through Market Ratios
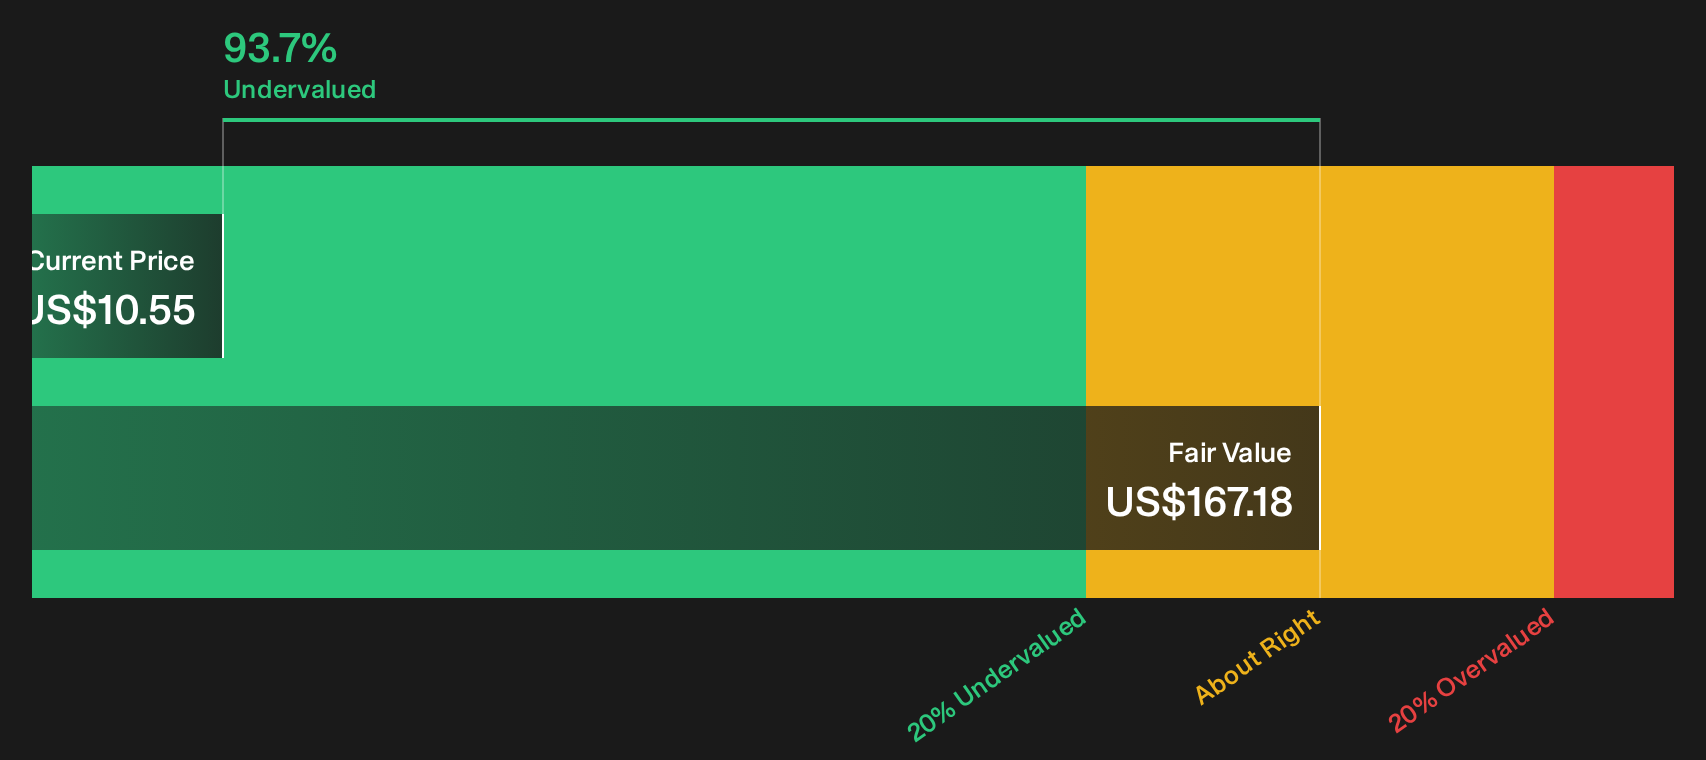
The SWS DCF model flags HighPeak Energy as trading very far below an estimated future cash flow value of $167.18, which clashes with the consensus fair value of $10.00. One framework calls the stock overvalued at $10.55, the other suggests deep undervaluation. Which story do you think holds up better under your own assumptions?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around HighPeak Energy is split, and that is exactly when doing your own homework matters most. Move quickly through the numbers, stress test the bullish and cautious arguments, then ground your decision in the 2 key rewards and 2 important warning signs.
Looking for more HighPeak Energy style ideas?
If HighPeak Energy has grabbed your attention, do not stop here. Broaden your watchlist with other high conviction setups sourced directly from the Simply Wall St screener.
- Target potential mispricings by scanning a curated pool of quality candidates using the 33 high quality undervalued stocks.
- Zero in on resilience and sleep better at night by filtering for companies in the 32 resilient stocks with low risk scores.
- Hunt for future market favourites early by spotting under-followed opportunities through the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com