
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Evercore (EVR) Earnings Estimates Cut
- Evercore recently added three senior managing directors, including aerospace and defense specialists John Song and Jean Stack in Washington, D.C., and Philip von Malsen Plessen in Frankfurt, expanding coverage in national security and the DACH region.
- These hires deepen Evercore’s access to defense, space and European large-cap clients at a time when analysts are questioning earnings durability and cost pressure.
- We will look at how Evercore's investment narrative is pressured by weaker earnings sentiment as the firm invests in senior advisory talent.
Evercore Investment Narrative Recap
To own Evercore, you need to believe the advisory engine can keep converting large-cap M&A, AI transformation and non M&A mandates into steady fees that cover a rising cost base. The short term swing factor is how Q3 and Q4 deal completions hold up while earnings sentiment softens and Treasury yields stay elevated.
Higher non compensation expenses and investment in senior talent remain the biggest swing risk to margins if activity cools. The latest hires add to that expense pressure but also broaden sector reach in aerospace, defense and Europe. If revenue timing disappoints, the cost stack becomes more visible very quickly.
The most relevant update here is Evercore bringing in John Song and Jean Stack as senior managing directors in aerospace and defense, plus Philip von Malsen Plessen in Frankfurt. Their track records in national security and European large caps plug directly into the firm’s existing focus on large corporate transactions and cross border work.
For you, the question is whether these hires help convert the stated advisory backlog into realized fees fast enough to offset higher non compensation spending and any weaker near term earnings prints. Analyst estimates have already been trimmed, so execution on these new sector and regional relationships will be watched closely around upcoming quarters.
Evercore Earnings Setup Behind The New Hires
Evercore's analyst playbook is fairly precise at the moment. Consensus models point to revenue growing by 2.4% a year over the next three years, while profit margins are expected to decline from 15.8% today to 14.3% by 2029. This indicates a softer earnings profile at the same time the firm is paying more for senior advisers like Song, Stack and von Malsen Plessen.
On the earnings line, forecasts land at US$721.7 million by 2029 versus US$745.0 million today. That is a projected decline of US$23.3 million, before taking into account any additional compensation or non-compensation costs required to integrate new sector teams and deepen European coverage.
Revenue expectations appear more upbeat than the profit picture. Analysts link their valuation work to 2029 revenue of US$5.1 billion and assume a P/E of 23.4x on forecast earnings of US$721.7 million, compared with about 13.7x on current earnings. If these numbers materialize, this would mean investors paying a higher multiple for a smaller earnings pool.
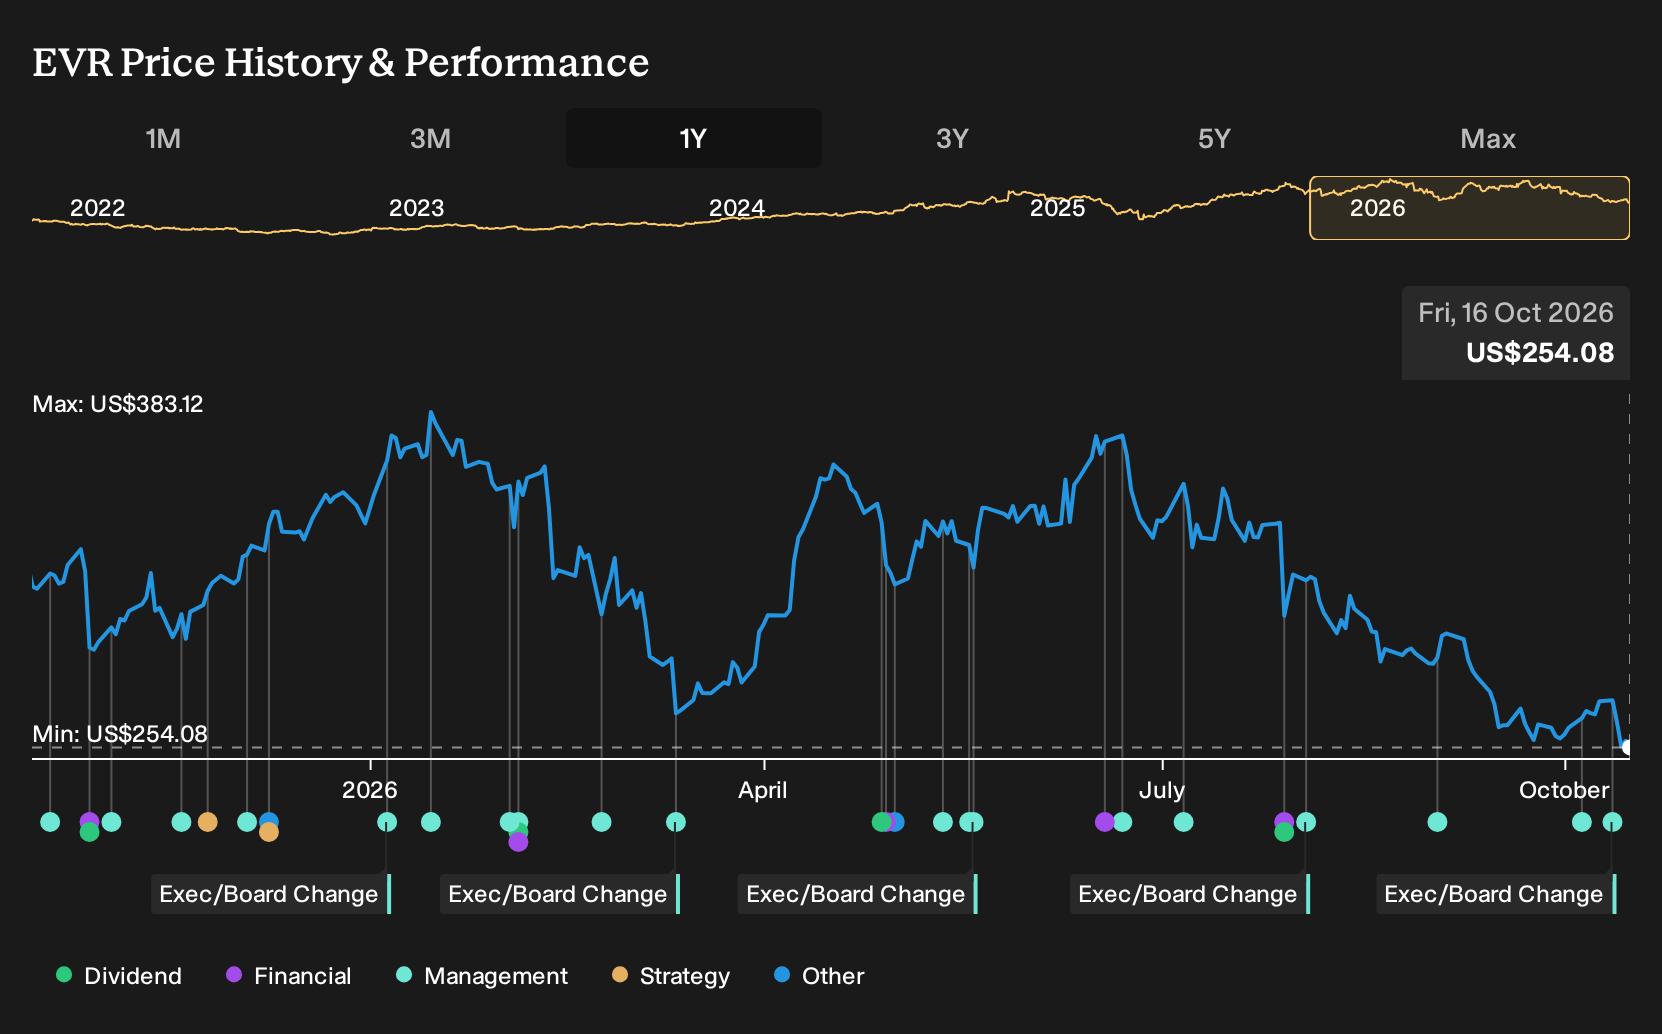
At the share price level, the consensus target is US$354.70 versus a current quote of US$265.35. The 25.2% gap reflects the view that Evercore can convert record advisory pipelines and new hires into sufficient activity to offset slimmer margins and support the heavier cost base associated with its expanded platform.
Evercore's narrative projects US$5.1 billion of revenue and US$721.7 million of earnings by 2029. This is based on 2.4% yearly revenue growth and a decline in earnings of US$23.3 million from US$745.0 million today.
Uncover why Evercore's fair value indicates a 40% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
One bullish perspective on Evercore focuses on the potential upside from this senior hiring. The most optimistic analysts were already penciling in revenue of US$6.6b and earnings of US$1.0b by 2029 before these appointments. That is far above the US$5.1b and US$721.7m consensus view. Use that gap as a prompt to compare different scenarios and decide which story you find more convincing, especially now that the aerospace, defense and DACH hires are public and forecasts may shift.
Explore 2 other Evercore fair value estimates, including one that suggests up to 54% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Evercore research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Evercore. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Evercore's overall financial health at a glance.
Looking For More Investment Ideas Beyond Evercore?
If Evercore has sharpened your thinking about earnings quality, adviser productivity and valuation, it can be useful to line it up against a wider watchlist. The Simply Wall St Screener lets you filter for different traits so you can focus on businesses that actually fit your risk appetite instead of scrolling through tickers at random.
- If capital preservation sits near the top of your priorities, start with companies that screen as more resilient and see which ones show up in our 32 resilient stocks with low risk scores.
- For investors hunting for cash generative businesses at what analysts view as attractive prices, check out the 33 high quality undervalued stocks and see which tickers match your approach.
- Income focused portfolios might benefit from a starting universe that already clears a higher yield bar, so scan the 8 dividend fortresses and test which payouts look sustainable after fees and taxes.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com