
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
NGL Energy Partners (NGL) Sells 18 Propane Terminals, Is The Valuation Discount Justified?
The sale of 18 propane terminals to Alliance Energy Services has put NGL Energy Partners (NGL) in the spotlight, as unitholders reassess how this reshapes propane logistics exposure and long term cash generation.
At a latest unit price of US$15.20, NGL Energy Partners has posted a 1-day share price return of 2.63% and a 7-day share price return of 3.12%. The 30-day share price return is down 6.92% as the market digests the propane terminal sale, while the very strong 1-year total shareholder return and multi year total shareholder return figures suggest momentum over the longer run remains firmly positive despite recent volatility.
Scan how other energy players are reshaping their asset mix after transactions like NGL Energy Partners' terminal sale by reviewing our curated list of list of solid balance sheet and fundamentals (25 results)
NGL Energy Partners has reshaped its propane footprint and delivered very strong multi year returns. The key decision now is whether that history reflects a robust business or a unit price that already assumes too much.
Preferred Price-to-Sales Multiple of 0.5x: Is it justified?
NGL Energy Partners changes hands at a P/S ratio of 0.5x, which points to a unit price that looks low relative to peers given the latest close at $15.20.
The P/S multiple compares the partnership's market value to its revenue. For midstream and logistics focused energy partnerships like NGL Energy Partners, investors often use P/S when earnings are volatile or negative, because it centers the discussion on top line activity rather than current profitability.
At a P/S of 0.5x, the market is assigning a sales based valuation that is well below both the US oil and gas industry average of 2.1x and the peer group average of 2.2x. The estimated fair P/S ratio of 0.7x also sits well above where the units trade today, suggesting the current multiple reflects a heavy discount that the valuation model indicates could narrow over time.
Explore the SWS fair ratio for NGL Energy Partners.
Result: Price-to-Sales of 0.5x (UNDERVALUED)
Still, falling annual revenue and a recent net loss of US$351 million leave NGL Energy Partners exposed if energy logistics volumes or contract terms weaken further.
Find out about the key risks to this NGL Energy Partners narrative.
Another View: What the SWS DCF Model Says About NGL Energy Partners
The low 0.5x P/S ratio flags potential value, but the SWS DCF model adds another layer. On that framework, NGL Energy Partners is trading at $15.20 against an estimated future cash flow value of $22.40, which presents the units as undervalued on cash generation potential.
Two different tools now point in the same direction on NGL Energy Partners. The question for you is which risk matters more: weak recent revenue trends, or the possibility that the market closes this pricing gap.
Look into how the SWS DCF model arrives at its fair value.
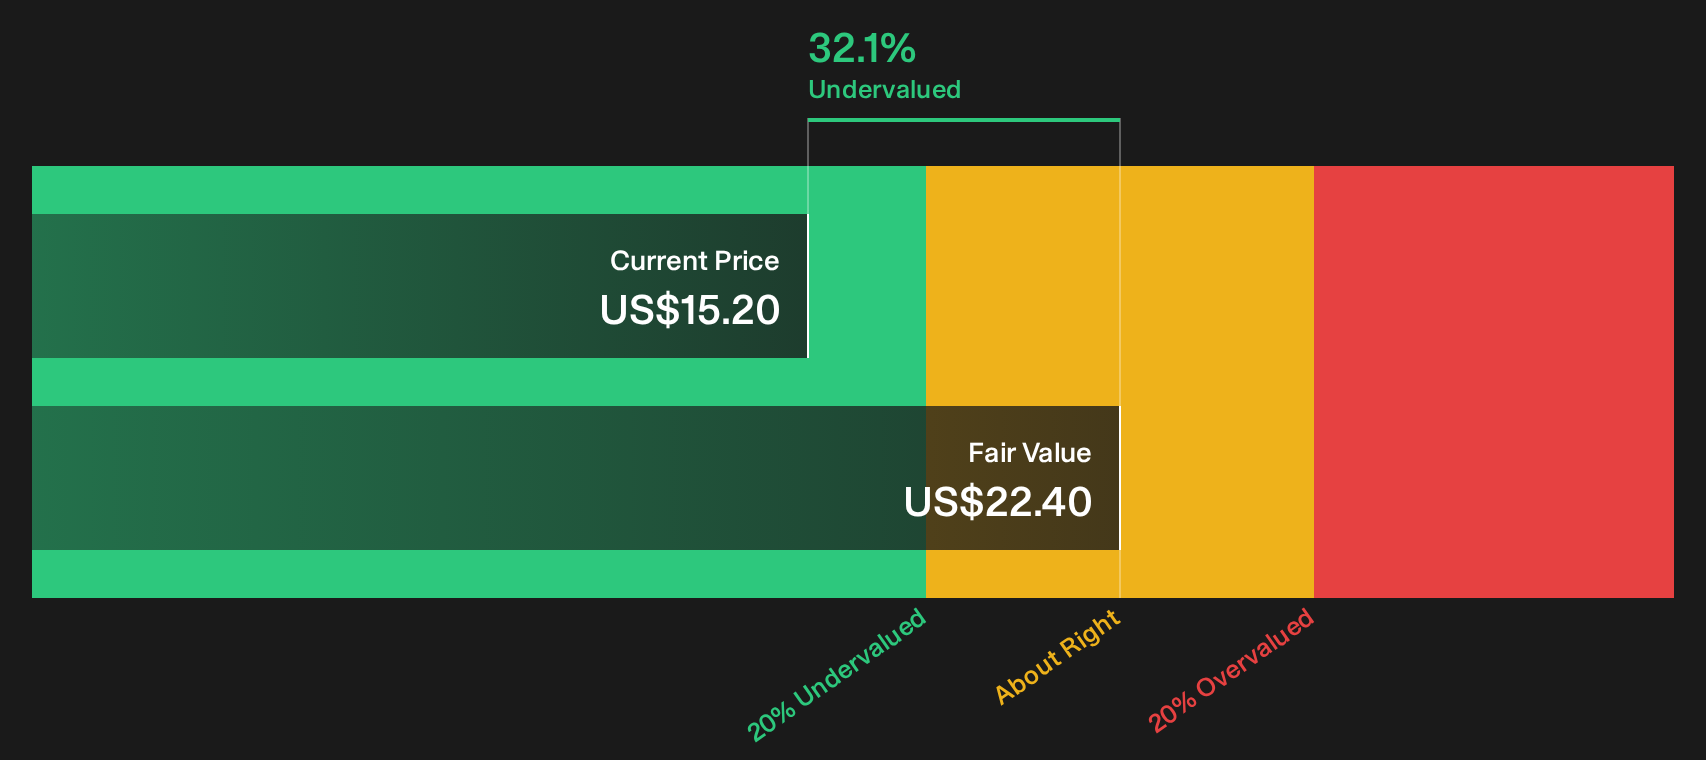
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NGL Energy Partners for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment looks mixed around NGL Energy Partners after the terminal sale, which is exactly why you should move quickly and run the numbers yourself. To see what the optimism is about, review the 3 key rewards
Looking for more investment ideas beyond NGL Energy Partners?
Do not stop with NGL Energy Partners. Broaden your watchlist now, because the next opportunity that fits your style might already be on the radar.
- Target underpriced quality by scanning companies that combine resilient balance sheets with appealing valuations using the 33 high quality undervalued stocks.
- Prioritize sleep-at-night stability and steady income by reviewing a curated group of high yield payers through the 8 dividend fortresses.
- Limit downside shocks by focusing on resilient businesses with relatively low overall risk scores via the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com