
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Anpario And 2 Other British Penny Stocks To Watch
British micro caps with strong balance sheets look more interesting when the domestic tax system is under fire for holding back growth. The warning from the Institute of Chartered Accountants hints that well run smaller businesses could benefit if future reforms simplify life for companies. This article picks out three lowly priced UK shares from our high quality penny pool that combine resilience, limited dilution and analyst forecasts that point to growth.
The three stocks below are just a sample from this theme, and the full screen surfaced 13 more UK micro caps with similarly tight balance sheets, limited dilution and grounded stories that are not covered here.
If you want to move straight from idea to action, use the Elite Penny Stocks screener to identify, filter and analyze the highest conviction penny stock candidates that match your own risk limits.
Anpario (AIM:ANP)
Overview: Anpario manufactures specialist animal gut health and feed additives that support nutrition, health and biosecurity, matching the screener’s focus on scalable, higher margin growth lines.
Operations: The business generates about £48.8 million from vitamins and nutrition products, with sales spread across Asia, Europe, the Americas and MEA.
Market Cap: £102.2 million
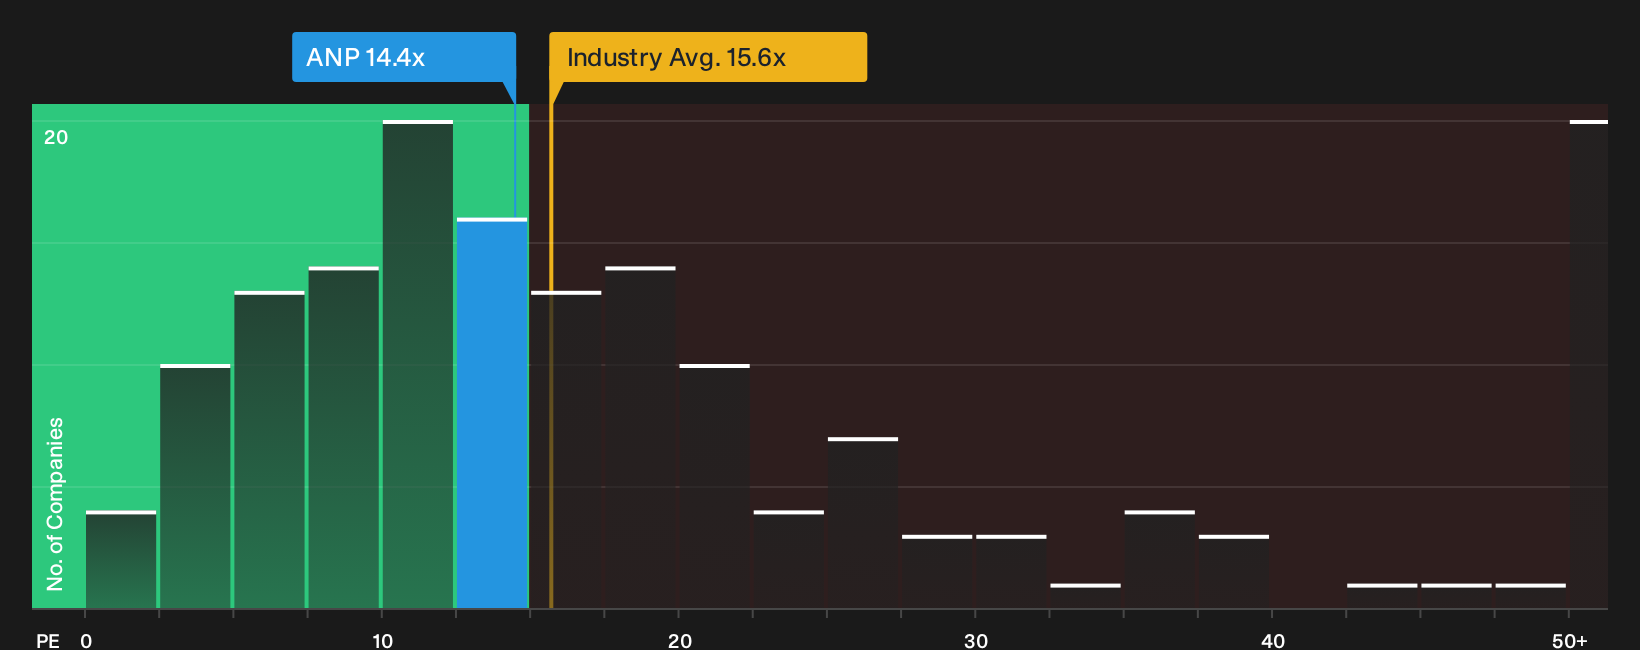
Anpario ties into the Elite Penny Stocks theme, with high margin gut health additives, a 37.7% earnings rise and a P/E of 14.4x against higher industry averages. Revenue of £24.3 million and net income of £3.08 million in H1 2026 support this profile. The impact on the 14.5% net margin if an unforeseen pressure were to emerge remains an open question.
That margin question is exactly what the 2 key rewards and 1 important warning sign is designed to examine. It can help you decide whether Anpario’s current profile matches your risk appetite.
Hochschild Mining (LSE:HOC)
Overview: Hochschild Mining runs underground and open pit gold and silver operations, with the Inmaculada mine anchoring its precious‑metals profile within the Elite Penny Stocks theme.
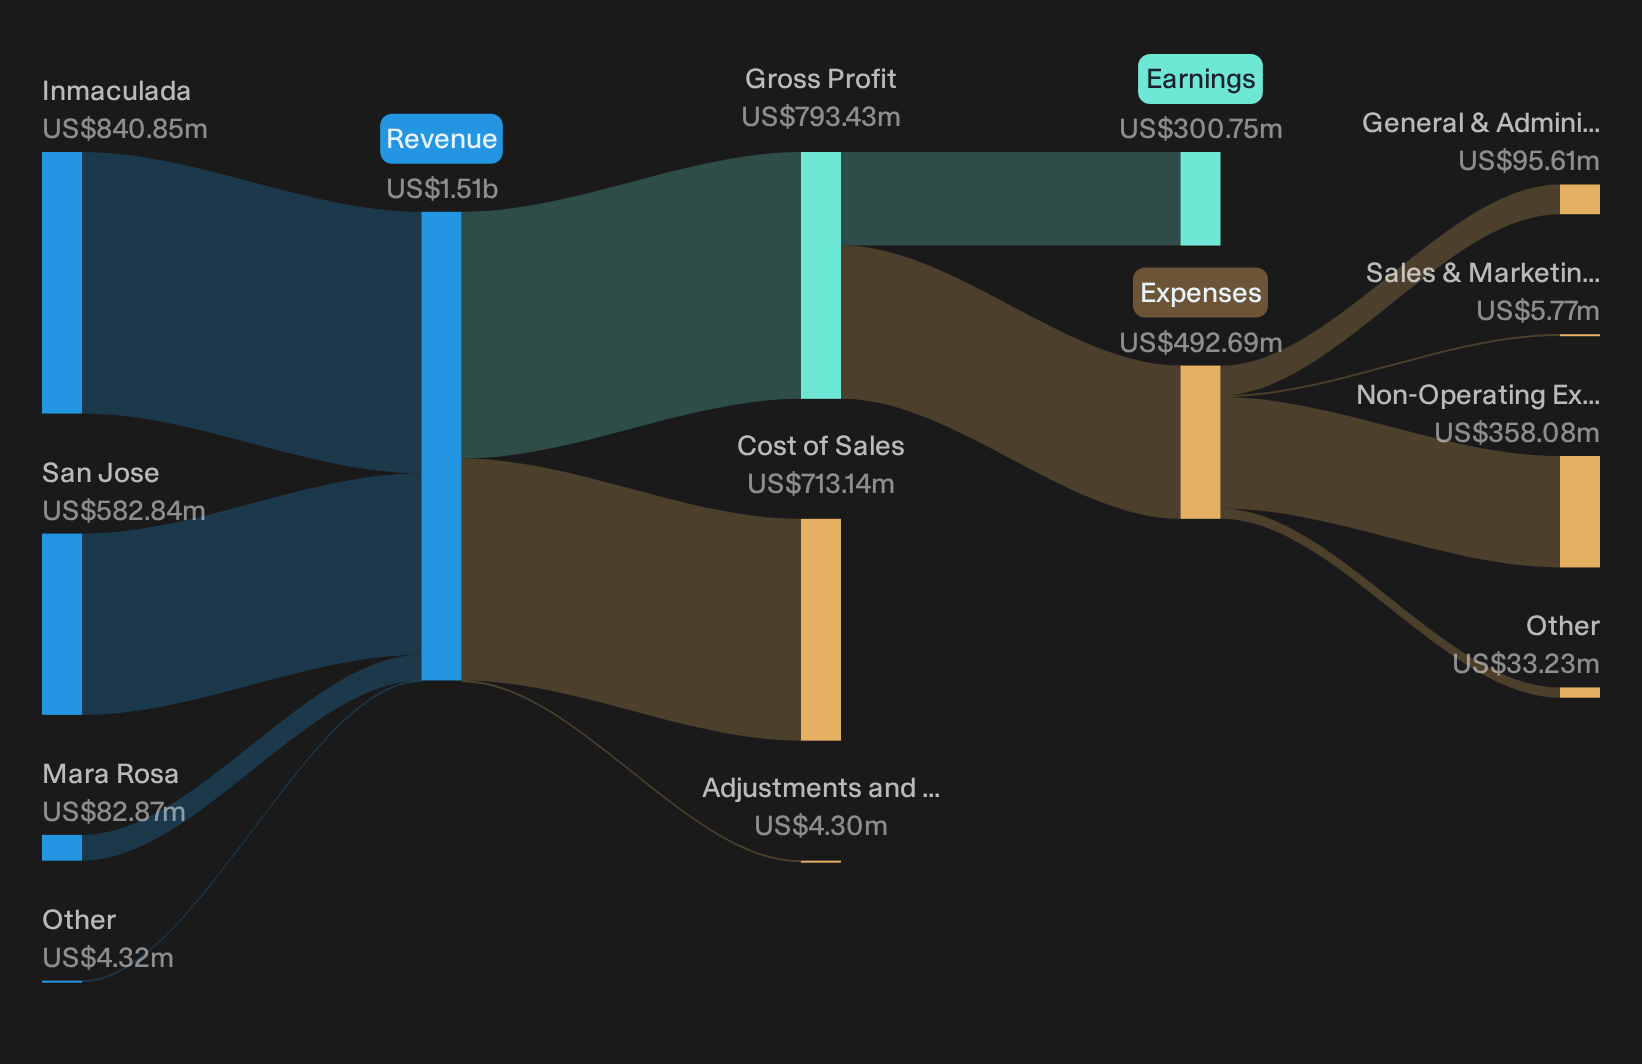
Operations: The group generates about $840.9 million from Inmaculada, $582.8 million from San Jose and $82.9 million from Mara Rosa.
Market Cap: £2.7b
Hochschild Mining fits this penny pool because its flagship Inmaculada complex links real producing assets to a balance‑sheet focused, high growth story.
"Mara Rosa depends on resolving filtration, tailings handling and rainy season disruptions. Any prolonged technical setbacks or delays to installing the new thickener and filtration roofs could keep all in sustaining costs elevated and limit volumes, putting pressure on group margins and earnings."
What matters now is how one unresolved operational fix ripples through cash generation, reinvestment headroom and the valuation gap investors care about.
That pressure is exactly why reading the full narrative for Hochschild Mining can help you judge whether Hochschild Mining’s operational fixes are masking or priming the next phase of value creation.
QinetiQ Group (LSE:QQ.)
Overview: QinetiQ Group provides test, training and mission support services for defense customers, using long term government contracts to anchor cash flow.
Operations: QinetiQ Group generates about £1.53b from EMEA Services and £393 million from Global Solutions, with most income coming from the UK.
Market Cap: £2.6b
QinetiQ Group fits this Elite Penny Stocks theme because long duration defense service contracts help support a strong balance sheet and controlled dilution.
"The extension of the long term partnering agreement to 2033, worth £1.5b, together with record order intake of £3.6b and a £4.8b backlog that covers 67% of the next year’s revenue, reflects a base of long duration contracts that can support revenue visibility and operating margins."
What happens to that earnings profile if one carefully managed shift in the reshaped portfolio alters how much of that backlog converts?
That hinges on whether QinetiQ Group is quietly compounding or slowly decoupling from its own backlog, which is exactly what the full narrative for QinetiQ Group unpacks for patient investors.

Seeking Fresh Alternatives Before They Fly
Fresh opportunities move quickly. Breakout stories gain momentum, prices move, and the quiet under the radar phase fades before the crowd catches on, so consider acting promptly.
- Scan for resilient cash generators before momentum traders arrive by running the list of solid balance sheet and fundamentals (9 results) that filters for robust finances and disciplined capital allocation.
- Spot dividend engines while yields are still holding up and prices have not fully adjusted by reviewing the 2 dividend fortresses built around higher income potential.
- Track early robotics momentum while adoption trends are still forming by using the curated 92 robotics and automation stocks that focuses on automation leaders with real-world exposure.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com