
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Investors Got Wrong About Catena Before The Drop
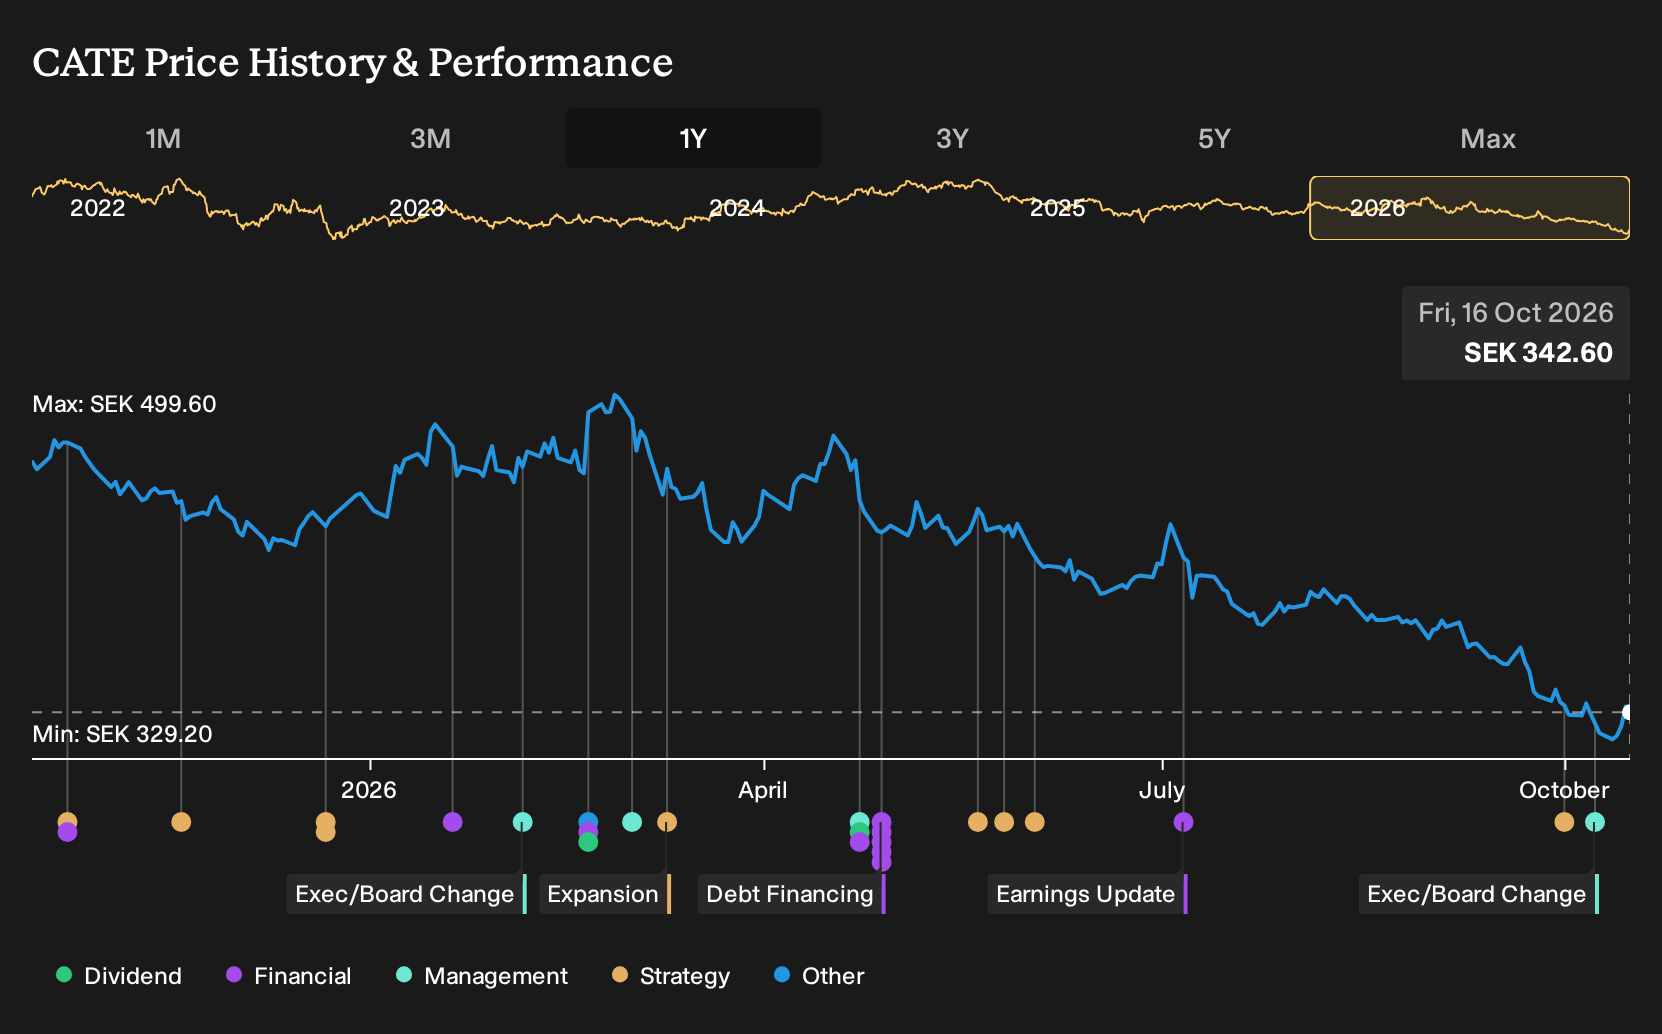
If you had looked at Catena in October 2025 and decided to sit it out while others debated Danish expansion, e-commerce tailwinds, and oversupply risk, the outcome might surprise you. For Catena shareholders, the loss over the past year was 24.5%, including dividends. With rental income, profit expectations, and occupancy risks all on record back then, which assumption would you have challenged before committing long term capital to this logistics landlord?
If the move has made Catena harder to judge, start where the gap is still open and scan 191 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On Catena
The shares cost SEK466 at the start of the period, and Catena sat between two very different stories about what its logistics footprint might be worth.
On the optimistic side, the bullish view saw a Fair Value of SEK508. This price was implied by assumptions that Danish expansion, extra square meters and a 7% yield on cost would support future earnings despite oversupply risk.
The cautious narrative pointed to a Fair Value of SEK229. This was based on expectations of 8.0% revenue growth, a 45.0% profit margin and a future P/E of 20.0x that could still be hit by prolonged higher debt costs.
What The Evidence Around Catena Actually Tested
Catena reported Q2 2026 revenue of SEK806 million and net income of SEK712 million, well above the prior year, which supported the optimistic case that extra space could be filled at solid economics. The net margin moved from 38.2% to 88.3%. Occupancy slipping to 94.6%, with management only aiming just above 95%, challenged the idea of frictionless expansion. Overall, the evidence cut both ways.
The pivot here was not about e-commerce slogans. It was whether new Nordic projects converted into stronger rental income and higher net margin. When you assess another property stock, connect the story to those same figures in later reports and see if the promised yield and occupancy actually show up in the numbers.
What The Fall In Catena’s Price Now Asks You To Believe
Catena shares now trade at SEK343, after a loss of 24.5% over the past year from SEK466. The selected Narrative’s Fair Value sits above the current price and refers to Nordic expansion, full buildings, and relatively low leverage to justify that stance.
The focus is on whether added space and new markets can stay filled at solid yields while tenant caution, new competitors, and regional oversupply risks are contained. A buyer today would need to believe that expanded capacity and a higher loan to value ratio still support resilient rental income and earnings.
"Strategic acquisitions and new projects are driving revenue growth through increased rental income and expanded portfolio capacity. Low leverage and market expansion strategically position Catena for future growth in revenue and earnings."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Before The Next Story Makes Headlines
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 48% below our estimate - ramps modular housing and technical project work to secure longer contracts.
- Company 2 - 25% below our estimate - expands the sales force so maintenance contracts scale faster across territories.
- Company 3 - 28% below our estimate - shifts from pediatric probiotics toward broader retail positioning and adult health offerings.
That is three of the list. See all 203 companies with the balance sheet to back it up →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com