
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Leidos Stock After New Contract Wins
- Leidos Holdings recently secured a $56 million, 66 month behavioral health research contract with the Naval Health Research Center and obtained a one year extension of its LCST logistics agreement with the UK Ministry of Defence through June 2029.
- These long duration defense and health awards extend Leidos Holdings' visibility on funded work while reinforcing its role in complex military logistics and operational readiness research.
- We will now look at how Leidos Holdings' investment narrative interacts with this extended LCST logistics work and new Naval contract.
Leidos Holdings Investment Narrative Recap
To own Leidos Holdings, you need to believe in a long runway of mission critical work in defense, health and civil infrastructure, underpinned by contract visibility and a capital light model. The LCST extension and new Naval Health Research Center award support that view by lengthening funded backlog. In the near term, execution on large defense technology and munitions programs remains the key swing factor.
The biggest operational risk still sits with concentration in government budgets and pressure on Health margins from VBA incentive changes and vendor mix. These contracts do not remove that exposure. They slightly reduce short term volatility around utilization and cash generation but do not fundamentally change the main risk that funding priorities or pricing terms could shift.
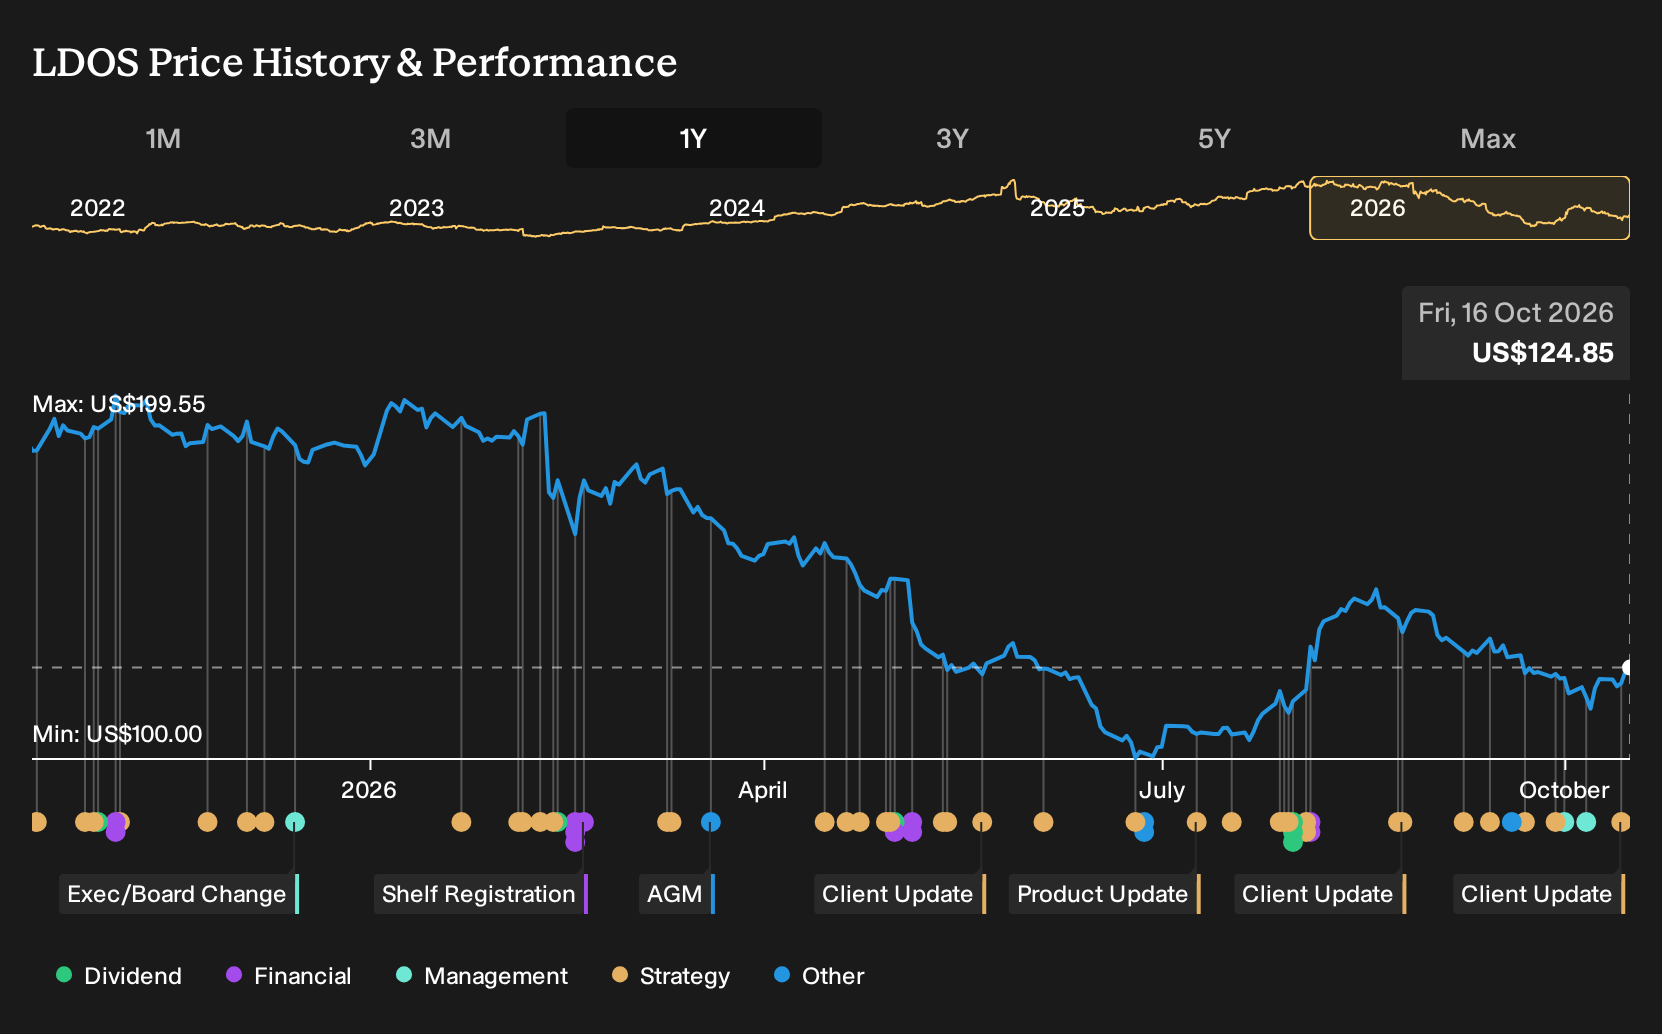
The most relevant development alongside the LCST and Naval research wins is the appointment of Stephen Vather as senior vice president of investor relations. This is not about changing the story. It is about how clearly Leidos Holdings translates its backlog, capital allocation and margin trajectory to the market at a time when the stock trades at an 11.4x P/E, well below both peer and industry averages.
Execution on defense tech, munitions and energy infrastructure programs will drive the real outcome. A seasoned IR lead with M&A and capital markets experience can help investors connect the dots between contract awards, cash generation and use of that cash for debt reduction, buybacks and dividends. That communication piece will matter if sentiment or sector valuation reset while earnings and free cash flow track current expectations.
Leidos Holdings' current analyst narrative points to revenues of US$20.0b and earnings of US$1.5b by 2029, based on assumed yearly revenue growth of 4.4% and an earnings increase of about US$0.1b from the US$1.4b reported today.
Uncover why Leidos Holdings' fair value indicates a 22% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
You can read the LCST extension and Naval health award as a direct challenge to the most pessimistic analysts. Their pre news view had Leidos Holdings' revenue reaching about US$19.8b with earnings of roughly US$1.3b by 2029. That stance assumes tighter margins. You may see these contracts and wonder whether that script now needs updating.
Explore 2 other Leidos Holdings fair value estimates, including one that suggests it could be worth just $151.73!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Leidos Holdings research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Leidos Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Leidos Holdings' overall financial health at a glance.
Looking for more Leidos Holdings sized ideas?
If this Leidos Holdings story has sharpened your thinking, use that same lens on a wider watchlist. The Simply Wall St Screener lets you zero in on companies that match your risk tolerance, income needs, and balance sheet preferences in a few focused steps.
- For investors who want steadier compounding with a valuation tilt, start with a curated set of resilient businesses trading below their estimated worth through the 33 high quality undervalued stocks.
- If income is your anchor, filter for companies offering stronger yields and robust payout histories by running a search across our 8 dividend fortresses.
- When capital preservation is your first question, not the last, build a shortlist of companies with stronger financial footing by screening the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com